


EN
Ball (BALL) Stock Looks About Right Following Its 34% Run
Ball has climbed 34.0% over the past year, which puts a bright spotlight on a simple question for investors who own the stock or are watching from the sidelines. Is the current share price, at around US$63, still in step with what the packaging group is actually earning?
- The 34.0% gain over the last 12 months places real weight on whether Ball's earnings story is strong enough to back up that kind of move.
- The business relies heavily on converting its metal packaging volumes into consistent profit margins, so any shift in input costs or pricing power can influence how much of each dollar of revenue turns into earnings.
- The analysts covering Ball have run their own numbers. See what analysts think Ball's shares could be worth.
The issue now is whether Ball's current share price is properly aligned with the earnings power that the company is generating today.
If you are questioning whether Ball's 34.0% one year gain is fully backed by its earnings, it can help to compare that performance against a wider set of 35 high quality undervalued stocks.
Is Ball Fairly Priced on Earnings?
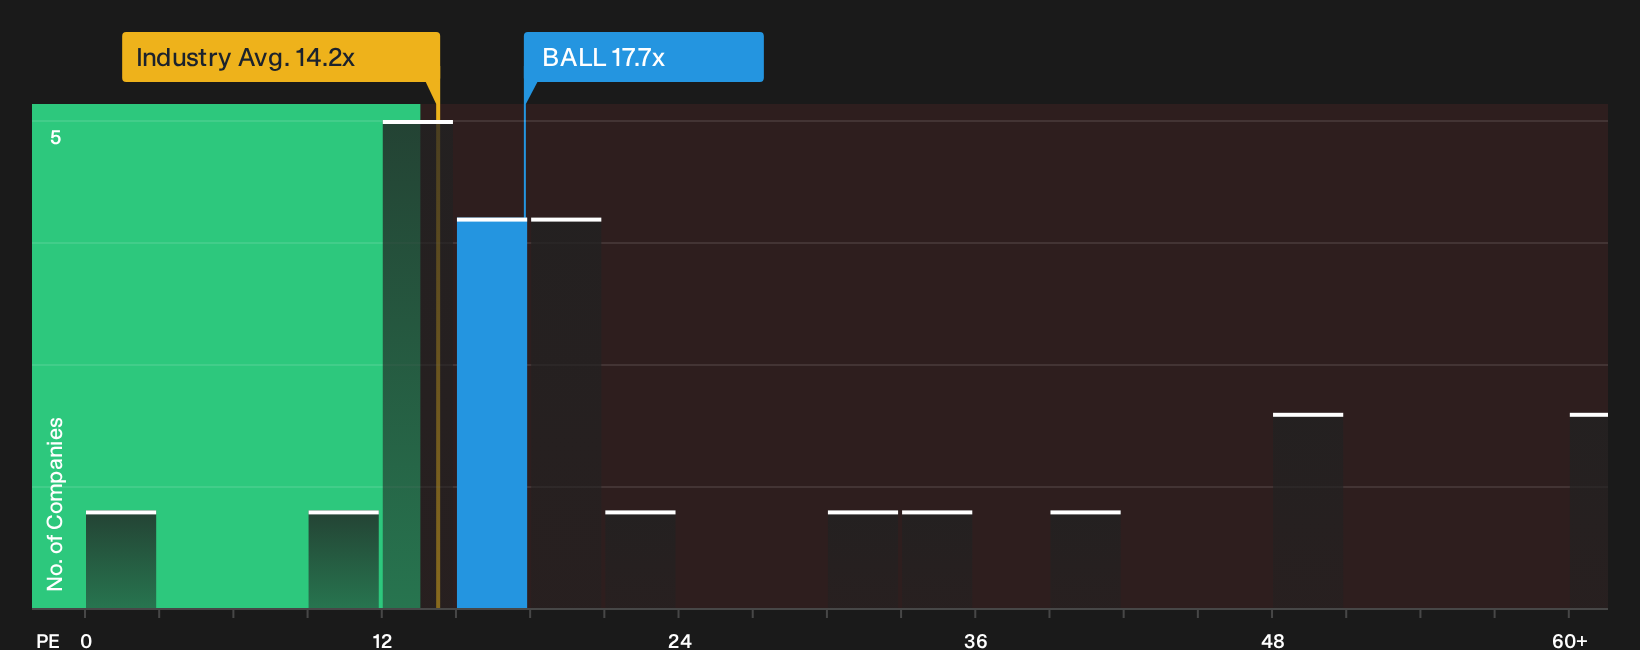
The P/E ratio is a useful shorthand here because Ball’s story is ultimately about how reliably it can turn its packaging volumes into earnings. On this yardstick, the stock trades at about 17.7x, which is below the broader packaging industry average of roughly 14.2x but also below a peer group that clusters nearer 21.7x. That mix suggests the market assigns Ball a premium over the sector as a whole, yet not the richest valuation inside its closer peer set.
A tailored fair P/E for Ball, which incorporates factors such as its profit profile, risks and scale, sits close to the current multiple. As a result, the price to earnings relationship appears balanced rather than stretched in either direction. Investors weighing this ratio now are essentially asking whether today’s earnings level and quality justify paying that kind of middle ground premium to the wider industry while leaving some headroom against higher rated peers. Explore the numbers behind Ball's P/E valuation.
The Ball Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ball are designed as the link between the valuation puzzle and the underlying assumptions about its future. They spell out what would need to happen with growth, profitability and earnings for the stock to be worth materially more or less than it is today on the screen. Each scenario ties a fair value estimate to a specific mix of potential catalysts and risks, so you can track over time which version of Ball's story appears to be unfolding.
One of the top community narratives on Ball: 13% undervalued
"Post divestiture focus on core aluminum packaging and the roll out of the Ball Business System, which now targets $500 million of gross productivity savings by the end of 2026…"
Discover why this Narrative puts Ball at 13% undervalued.
The Ball share price is only one part of the puzzle
Price and P/E tell only part of the Ball story, because the research also flags specific risk checks that could matter just as much to your decision. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com