


EN
Smurfit Westrock (SW) Could Be 20% Undervalued After Q3 Results And Dividend Reaffirmation
Smurfit Westrock (NYSE:SW) has investors’ attention after releasing third quarter 2026 results along with a fresh dividend decision, combining an earnings update with a reaffirmed cash payout to shareholders.
Those updates landed after a mixed year for the stock, with a 9.65% year to date share price gain and a 24.66% total shareholder return over 12 months. This came despite the share price declining about 10.42% over the past quarter as enthusiasm cooled from earlier levels.
Scan beyond Smurfit Westrock and compare its latest earnings and dividend profile with a curated 4 dividend fortresses that shares a similar focus on income.
The recent pullback in Smurfit Westrock after steady 1 year gains leaves a simple tension: Is the share price now tracking weaker earnings or short term sentiment while the dividend stays unchanged?
Most Popular Narrative: 20.4% Undervalued
At a last close of $43.42 against a narrative fair value of $54.57, Smurfit Westrock is framed as materially undervalued, with that gap depending on how far margins and cash generation can be improved over the next few years.
Ongoing realization of at least US$400 million in identified synergies, together with additional commercial and operational improvements highlighted by management, continues to offer room for higher operating leverage, which can support future EBITDA growth and stronger net margins.
See why 14 investors see Smurfit Westrock as 20% undervalued.
Result: Fair Value of $54.57 (UNDERVALUED)
Still, the narrative can unravel if freight and energy costs continue to pressure margins, or if pushback on containerboard price rises limits Smurfit Westrock’s pricing power.
Find out about the key risks to this Smurfit Westrock narrative.
Another View: What Smurfit Westrock’s P/E Is Telling You
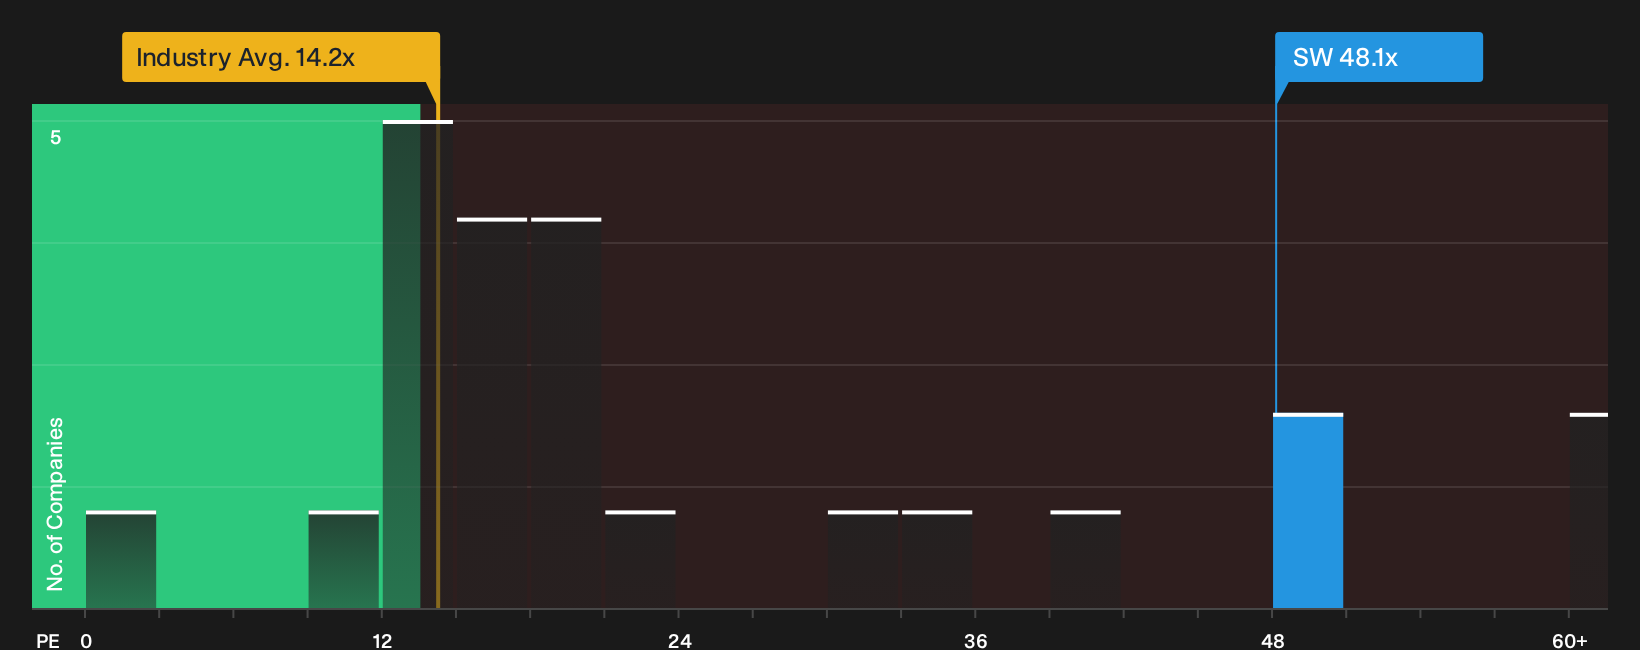
The fair value narrative paints Smurfit Westrock as undervalued, yet the share price trades on a P/E of 48.1x. That is more than triple the Global Packaging industry on 14.1x and above an estimated fair ratio of 42.9x, which points to meaningful valuation risk if expectations cool.
The current setup leaves investors weighing a discounted fair value story against a rich earnings multiple. The key question is whether you think the market moves closer to that fair ratio or keeps paying up at today’s level. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Smurfit Westrock’s valuation and earnings can pull you in opposite directions, so move quickly, stress test the data yourself, and weigh its 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Smurfit Westrock?
You do not need to stop with Smurfit Westrock. Use focused stock lists to pressure test your income plan, diversify risk, and spot fresh opportunities before others notice.
- Target resilient income by scanning a curated group of higher yield payers through the 4 dividend fortresses that filters for stronger dividend profiles.
- Hunt for potential mispricing by reviewing the 35 high quality undervalued stocks that narrows in on financially robust businesses trading below intrinsic estimates.
- Protect your downside by leaning on the 30 resilient stocks with low risk scores that spotlights companies with steadier fundamentals and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com