


EN
Is Verizon Fiber Deal Altering The Investment Case For Corning (GLW)?
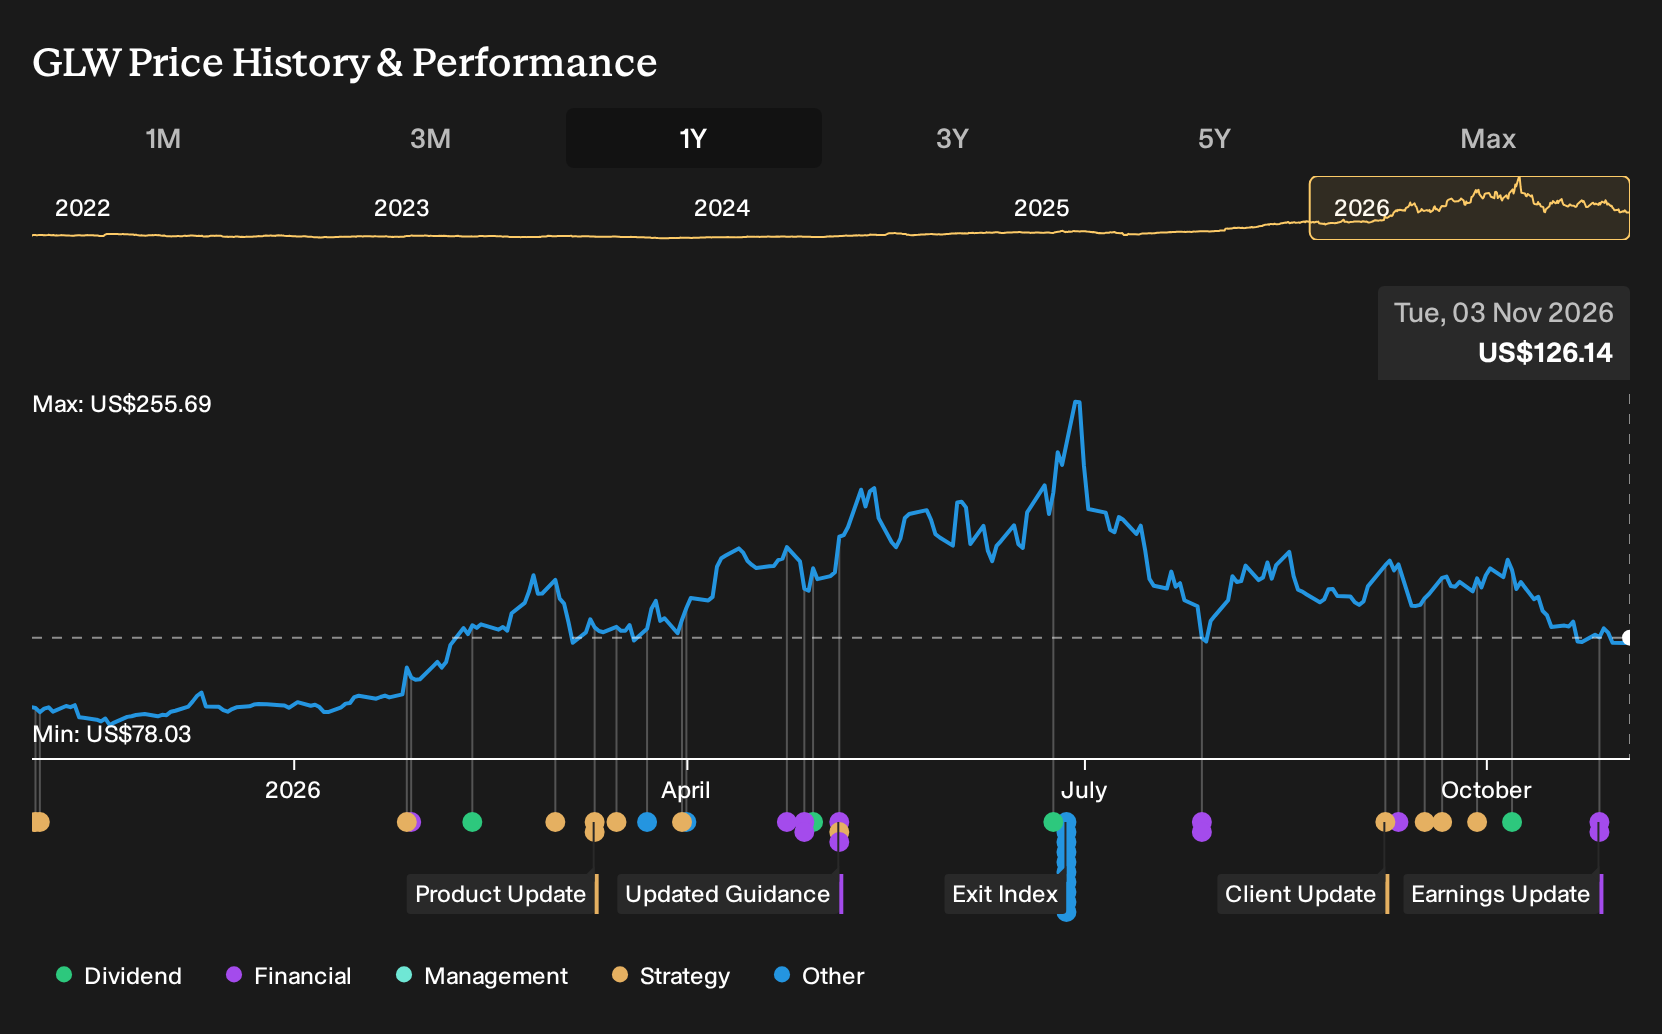
- Corning reported third quarter 2026 sales of US$4.855b and net income of US$680m, alongside nine month sales of US$13.504b and earnings growth compared with the prior year. Management also issued guidance for higher core sales and EPS in the fourth quarter.
- A multibillion dollar agreement to supply more than 80 million miles of optical fiber to Verizon highlights how Corning is tying its telecom manufacturing footprint directly to long duration demand for broadband and AI infrastructure, while also expanding roles in life sciences and advanced cell culture markets.
- We will now examine how Corning's multibillion Verizon fiber deal could reshape the investment narrative built around its Springboard targets.
Corning Investment Narrative Recap
Owning Corning means believing the company can convert its optical, solar and life sciences positions into the Springboard targets while keeping execution tight. The latest quarter delivered US$4.855b in sales and US$680m in net income, with nine month figures also higher than a year ago. That supports the idea that core businesses are scaling into demand for broadband, AI infrastructure and advanced lab consumables.
The short term swing factor is operational follow through on these orders and guidance, especially without leaning too heavily on equity issuance for funding. Risks sit around execution in newer areas such as solar, clarity between GAAP and core metrics, and managing dilution as capital projects ramp. The recent update does not remove those issues, but it gives more evidence that the current plan is being carried out.
The most relevant announcement tied to this earnings print is Corning's outlook for the fourth quarter of 2026. Management expects core sales of US$5.2b to US$5.3b, about 19% higher year over year, and core EPS of US$0.96 to US$1.00, about 36% higher year over year. That guidance matters because it connects the Verizon fiber agreement and other long duration contracts to near term execution.
For you as an investor, the key question is whether Corning can deliver that step up while controlling costs and avoiding fresh operational setbacks, especially in solar. Successful delivery would support confidence in the broader Springboard trajectory and the idea that multi year customer commitments in fiber and photonics can translate into higher margins. Any miss or renewed issues in newer segments would keep the current risk debate around funding, earnings quality and execution very much alive.
Corning's current analyst narrative points to forecast revenue of US$29.4b and expected earnings of US$5.7b by 2029. These figures are based on an assumed 20.1% yearly rise in revenue and an earnings increase of about US$3.8b from US$1.9b today.
Uncover how Corning's fair value indicates a 45% potential upside to its current price before the market closes the discount.
Exploring Other Perspectives
Not everyone reads Corning the same way. The most cautious analysts focus on the risk that new equity issuance keeps earnings per share muted even if revenue grows. Their pre news models pointed to about US$29.6b of 2029 sales and US$4.9b of earnings. You should treat the latest Verizon fiber deal and guidance as new information that could eventually shift those expectations, and compare both stories before deciding which version you find more convincing.
Explore 6 other Corning fair value estimates, including one that suggests it could be worth just $129.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Corning research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Corning. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corning's overall financial health at a glance.
Looking For More Investment Ideas Beyond Corning?
If Corning is on your radar because of its role in broadband and AI infrastructure, it can help to line it up against other opportunities with clear financial traits. The Simply Wall St Screener lets you filter the market by balance sheet strength, income potential or mispriced quality, so you can build a watchlist that fits how you like to invest.
- Prefer companies that aim to combine strong finances with sensible valuations, rather than chasing hype alone, then review the 35 high quality undervalued stocks that match those filters.
- If steady income is a priority, consider stocks that target higher yields and resilient cash generation through the 4 dividend fortresses.
- When capital preservation matters most, focus on businesses with robust financial foundations by scanning the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com