


EN
What’s Going On With United Parcel Service (UPS)?
United Parcel Service (UPS) just packed several updates into its 27 October release, including US$182 million of goodwill and asset impairment charges, along with raised 2026 earnings guidance and affirmed dividend plans.
The share price response has been swift. United Parcel Service has a 30 day share price return of 17.36% and a year to date share price return of 8.07%. The 1 year total shareholder return of 24.76% contrasts with a 5 year total shareholder return that has declined 34.13%, suggesting that short term momentum is improving even as longer term holders are still recovering from earlier weakness.
Scan how other logistics and income-focused stocks are reacting to similar earnings guidance and dividend stories by running the curated 4 dividend fortresses alongside United Parcel Service in your watchlist.
United Parcel Service has reminded investors it is a large, profitable logistics engine, and the past month’s rally has priced in some of that story in a hurry. Is the stock already charging a full premium for it?
Most Popular Narrative: 3% Undervalued
Against the last close at $109.17, the most followed narrative pegs United Parcel Service's fair value around $112.54 using an 8.49% discount rate, leaving a narrow gap that still matters for anyone trying to judge how much is already priced in.
The current valuation implies that United Parcel Service's share price does not fully reflect the earnings power investors infer from the shift to premium volumes, healthcare growth and the cost savings tied to the Amazon glide down and automation program.
See why 222 investors see United Parcel Service as 3% undervalued.
Result: Fair Value of $112.54 (UNDERVALUED)
Still, that story can unravel if the planned 150 building closures and 25 million fewer operating hours disrupt service, or if rising labor pressure limits future efficiency gains.
Find out about the key risks to this United Parcel Service narrative.
Another View: United Parcel Service Through The P/E Lens
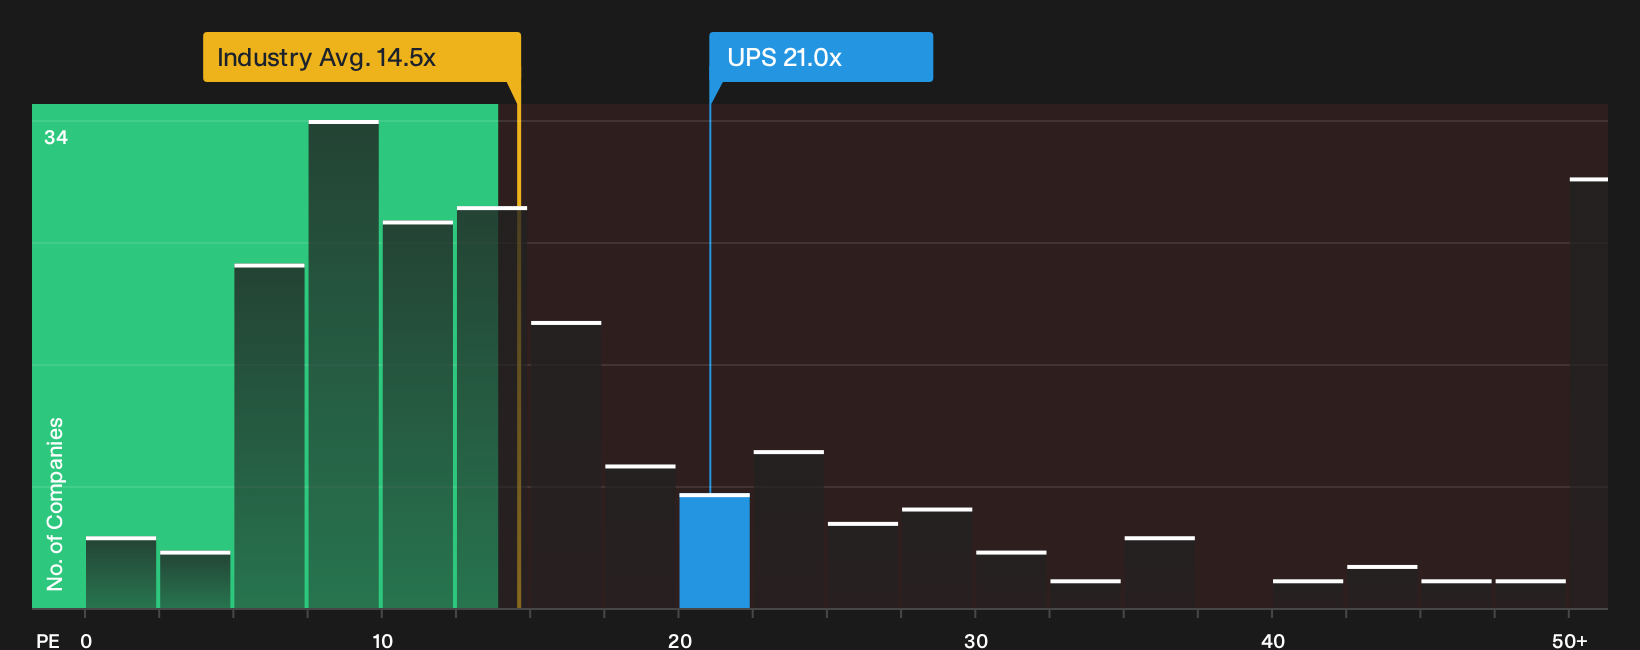
There is a second message hiding in plain sight. United Parcel Service trades on a P/E of 21x, which is higher than the global logistics average of 14.5x and above the peer group on 19.7x. That signals investors are already paying a premium relative to similar stocks.
The fair ratio for UPS is estimated at 26x, which leaves a gap that could either close through earnings catching up or the share price adjusting. For anyone weighing that 3% undervalued narrative, the question is simple: Is this a reasonable premium for the quality on offer, or a thinner margin of safety than it first appears?
See what the numbers say about this price in the fuller valuation workup, including how that fair ratio was calculated, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early reset? If you want to move faster than the next headline and weigh United Parcel Service on your own terms, start by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond United Parcel Service?
If you stop at UPS, you miss the fuller opportunity set. Apply a few well chosen filters and let the data surface ideas for you.
- Target resilient balance sheets that can handle shocks by scanning the list of solid balance sheet and fundamentals (23 results) for candidates that pair financial strength with fundamental support.
- Hunt for mispriced quality and pressure test your valuation skills with the 35 high quality undervalued stocks that highlights companies the market may be overlooking.
- Lock in steadier income streams by reviewing the 4 dividend fortresses that focuses on higher yield payers with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com