


EN
SpaceX Stock Can Get a Lift From the Anthropic IPO, but SPCX Remains Unappealing
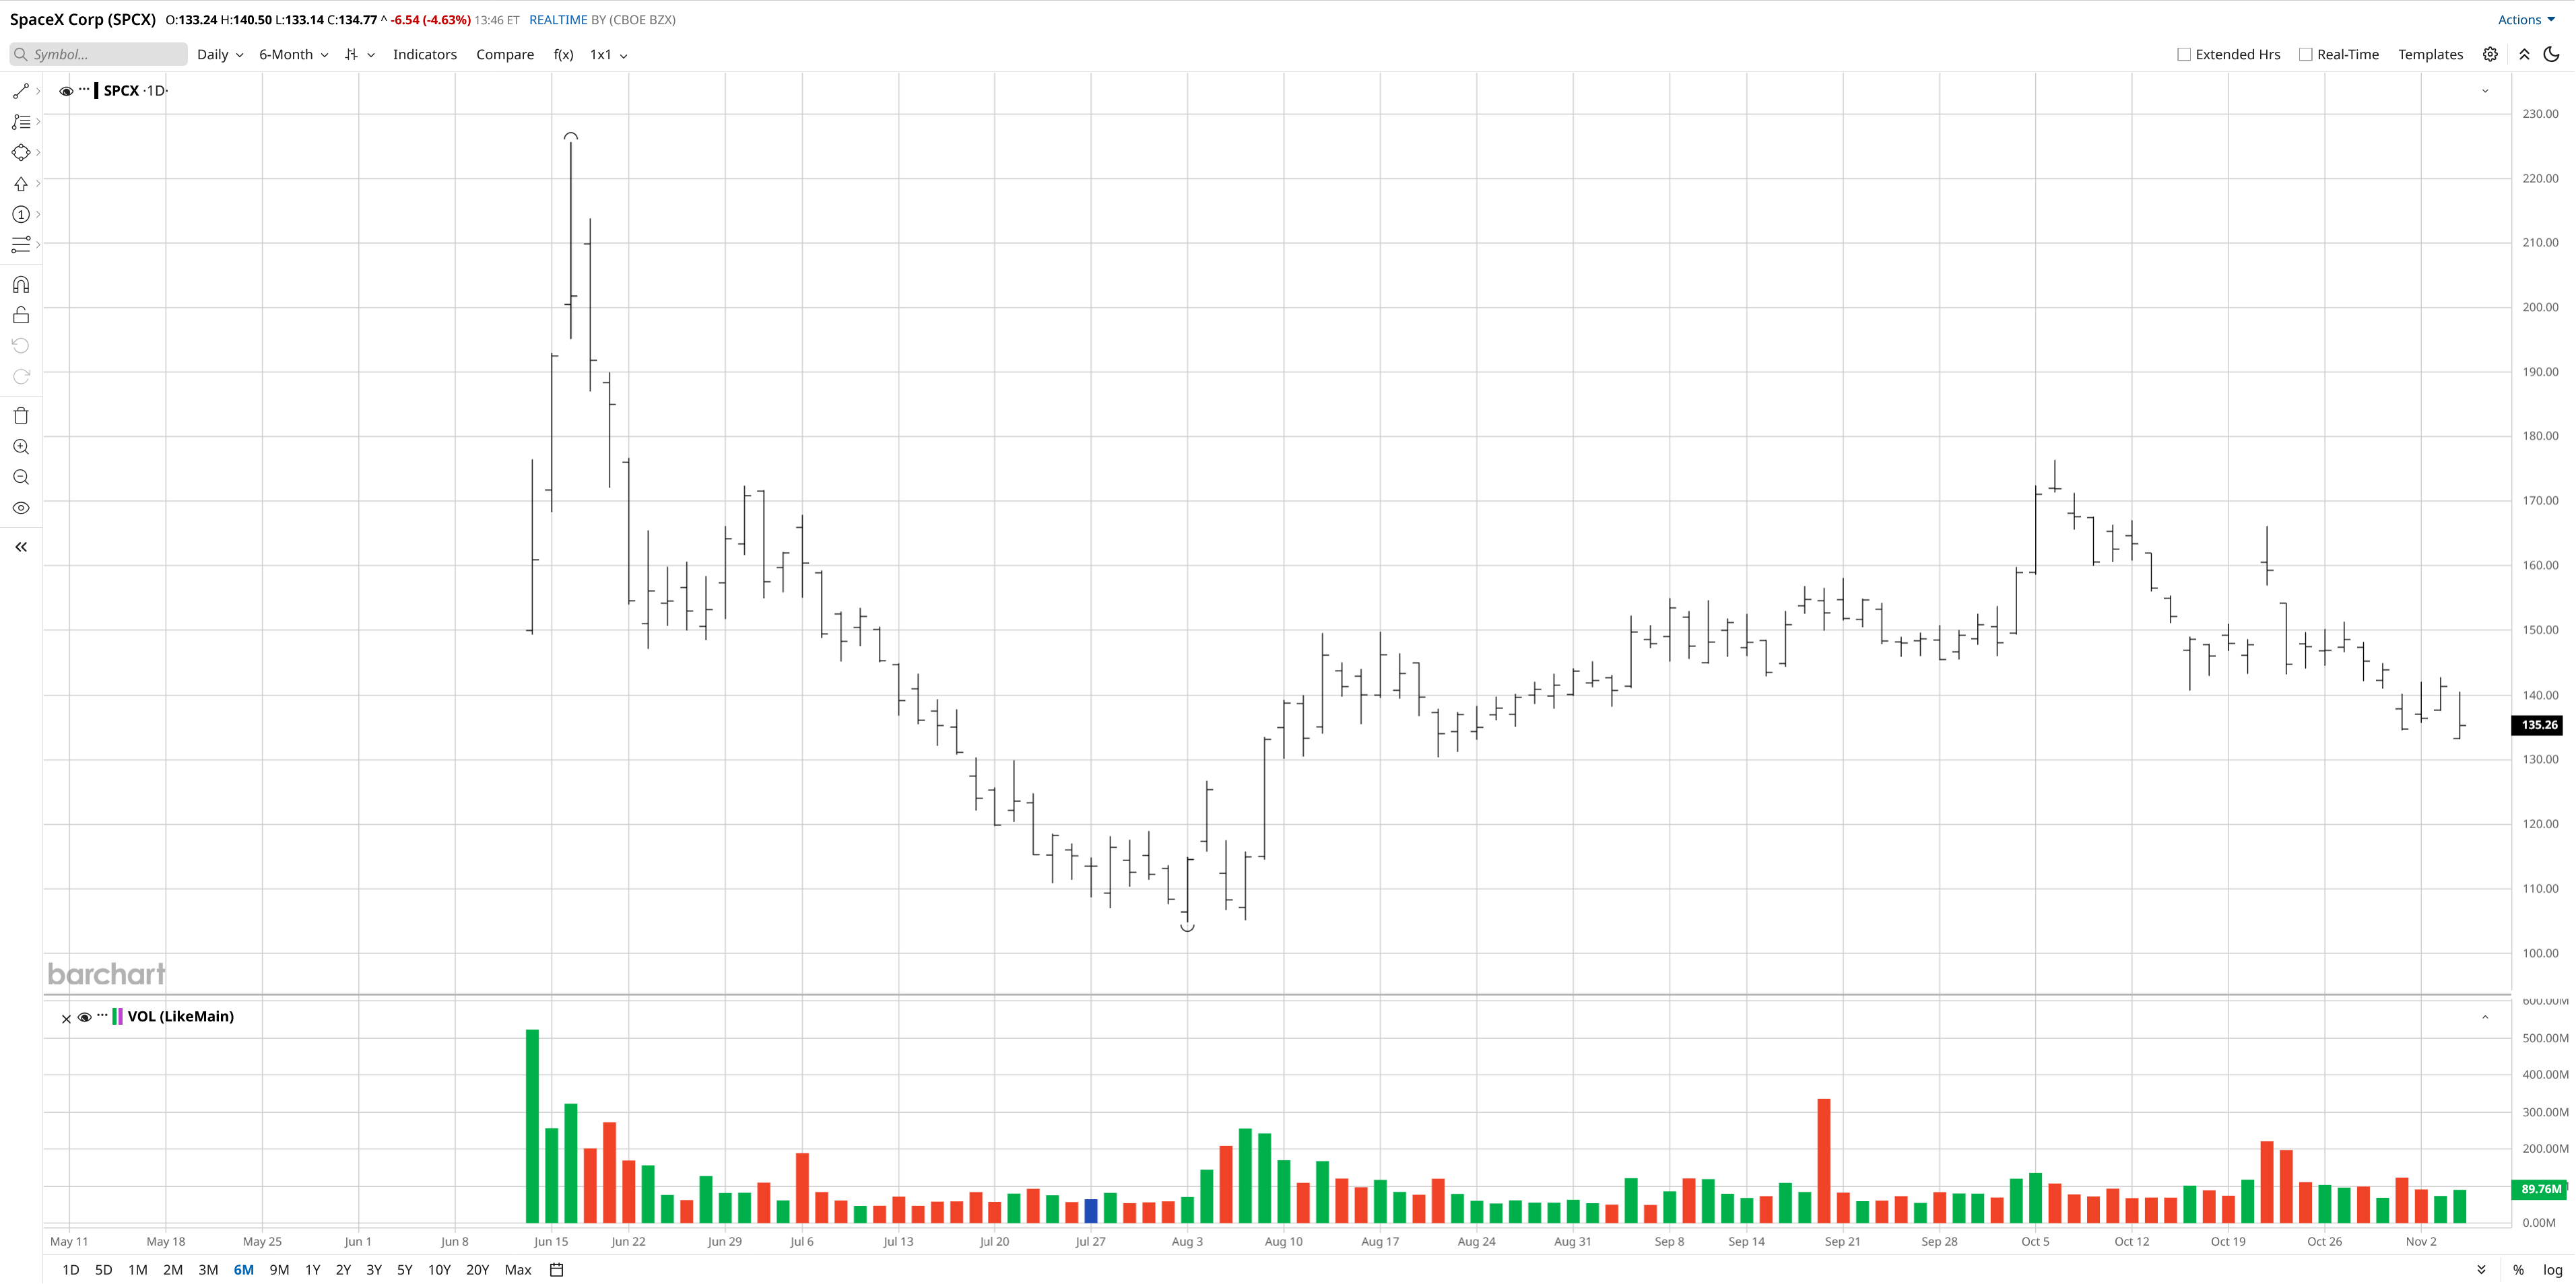
SpaceX (SPCX) generated over a third of its revenue last quarter from Anthropic (ANT). With the huge AI start-up poised to rake in a great deal of money from its upcoming IPO, it may spend much more on SpaceX's data centers going forward, giving SpaceX stock a potential positive catalyst. Still, building data centers that are equipped with Nvidia's (NVDA) chips, as SPCX is doing, is a very expensive undertaking that takes a long time, and it will be significantly over a year before they start generating profits for Elon Musk's firm. What's more, SpaceX will have to periodically and perpetually buy or provide costly AI chips for its data centers.
Also importantly, SpaceX's tremendous reliance on Anthropic does meaningfully increase the risk posed to SPCX stock. On the other hand, with Anthropic growing at a blistering pace and already generating a profit, it could turn out to be a gold mine for SpaceX in the long term.
Still, given the significant period before SpaceX can generate positive ROIs from its data centers, the high cost of providing AI chips, the sizeable risk that its data center strategies pose, and the massive valuation of SPCX stock, SpaceX does not appear to be a good choice for investors at this point.
Anthropic's IPO Could Boost SpaceX's Top Line
Anthropic is reportedly looking to obtain $100 billion from its IPO, and it could spend a sizeable amount of those funds on SpaceX's data centers. In Q3, SpaceX's top line came in at $14.6 billion. So if the IPO allows Anthropic to spend $15 billion more per year on the data centers of Elon Musk's firm, SpaceX's revenue could be boosted by 25% annually.
SpaceX's Data Centers Will Be Very Expensive for the Firm
It costs SpaceX about $50 billion to build each gigawatt of computing power, according to John Foley of The Financial Times. And Anthropic is reportedly paying $1.25 billion per month for about 300 megawatts of SpaceX's computing capacity. (The firm reportedly received a discount for the first two months, but we'll exclude that from the calculations). Based on Foley's estimate, 300 gigawatts could cost SpaceX 30% of $50 billion or $15 billion. And the company will collect $15 billion annually from Anthropic. But Foley's estimates presumably do not include maintenance expenses, electricity costs, and the interest fees associated with the debt that SPCX is paying in order to obtain the funds needed to build the facilities. My estimates suggest that those costs are likely to add another $2.2 billion per year onto SpaceX's bill. So it will take about 14 months before the Anthropic deal starts to generate a positive ROI for SpaceX.
One could think, “OK, but after that, SpaceX will really start to rake in huge profits from the data centers.”
But that may not be the case. That's because it appears that the majority of the cost of the data centers involves buying Nvidia's pricey AI chips, while SpaceX will probably have to purchase new chips at least every two years. According to an analyst, 10 gigawatts of Nvidia's processors may cost SpaceX over $400 billion, or $40 billion per gigawatt. Nvidia updates its AI chips annually; Anthropic can cancel its contract with SpaceX any time starting in early 2027 with just 90 days' notice, and the giant startup will have to keep up with its competition. Further, other companies will be looking to take Anthropic's business from SpaceX. Consequently, Musk may be on the hook for a vast number of Nvidia chips every year or two.
To counter this dynamic, SpaceX is trying to launch its own chip factory. But that facility is not expected to be completed until the end of 2028, and the timetable could easily stretch into at least 2029 or 2030. Plus, the plant is expected to cost as much as $119 billion, excluding interest on associated loans and the substantial licensing fees that SpaceX will probably have to pay its tech partner on the project, Intel (INTC). And there's no assurance that SpaceX's chips will be nearly as good as those of Nvidia.
Not to mention Musk's technically dubious and shockingly expensive 5-trillion-per-gigawatt space-based data center plans that would take even longer to see any potential returns.
Put it all together, and it's clear that the firm's profits from the endeavor may not be very high and that the company's strategy is moderately risky.
SpaceX's Risks, Its Difficult Telecom Venture, and Its Massive Valuation
SpaceX's overreliance on Anthropic does increase the risk posed to SPCX stock. If the AI model maker's business slows or it locates a source of cheaper computing power, SpaceX could lose a large percentage of its revenue.
Data centers aren't the company's only expensive and risky venture either, as it attempts to expand into the telecom industry. With such well-entrenched competition, this expansion will be quite difficult, and expensive, and success is far from guaranteed.
Further, as I've pointed out in past columns, Tesla (TSLA) has had more than its share of missed targets and technical problems, so SpaceX's execution risk is already starting relatively high.
Finally, SPCX stock is changing hands at a huge price-sales (P/S) ratio of 54x.
On the date of publication, Larry Ramer did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.