


EN
Chefs' Warehouse (CHEF) Lifted Its Outlook, Is The Stock Still A Bargain?
Why Chefs' Warehouse stock is back in focus
Chefs' Warehouse (CHEF) moved back onto investor watchlists after the company raised its full year 2026 earnings outlook and paired that update with fresh third quarter results.
Management now projects full year 2026 net sales between US$4.56b and US$4.61b. That new range arrived alongside the latest quarterly report, which gives you more detail on how the business is tracking against those goals.
Chefs' Warehouse shares have cooled off recently, with the price down 13.29% over the past month and 6.99% over ninety days, even though the year to date share price return is 61.80% and the three year total shareholder return is over 3x. This suggests that investors may be pausing after a strong multi year run to reassess how the new 2026 guidance and latest earnings shape the risk and growth profile from here.
Scan how Chefs' Warehouse compares to other food and consumer names on our hand-picked list of 19 high quality undiscovered gems before the next round of guidance shifts attention again.
Chefs' Warehouse has paired a strong multi year share run with fresh guidance and higher recent earnings, yet the stock has pulled back. This raises a key question for potential investors: does that reset leave more upside than downside for new buyers now, based on valuation?
Most Popular Narrative: 17.3% Undervalued
On the most followed view, Chefs' Warehouse screens as undervalued, with a fair value estimate of $122 against the latest close at $100.95. This puts the current pullback in a different light for anyone focused on long term cash generation.
Disciplined capital allocation, with approximately US$270m of free cash flow generated since early 2024, a net leverage ratio around 1.6x, and guidance for 40% to 60% free cash flow conversion and Capex near 1% of revenue, supports the case that Chefs' Warehouse can fund growth initiatives, manage refinancing, and return capital to shareholders while supporting earnings and free cash flow per share.
See why 6 investors see Chefs' Warehouse as 17% undervalued.
Result: Fair Value of $122 (UNDERVALUED)
Still, the Chefs' Warehouse story can change quickly if structural cost inflation squeezes margins or if supply chain disruptions push up logistics and sourcing costs again.
Find out about the key risks to this Chefs' Warehouse narrative.
Another View: What Chefs' Warehouse’s P/E Is Telling You
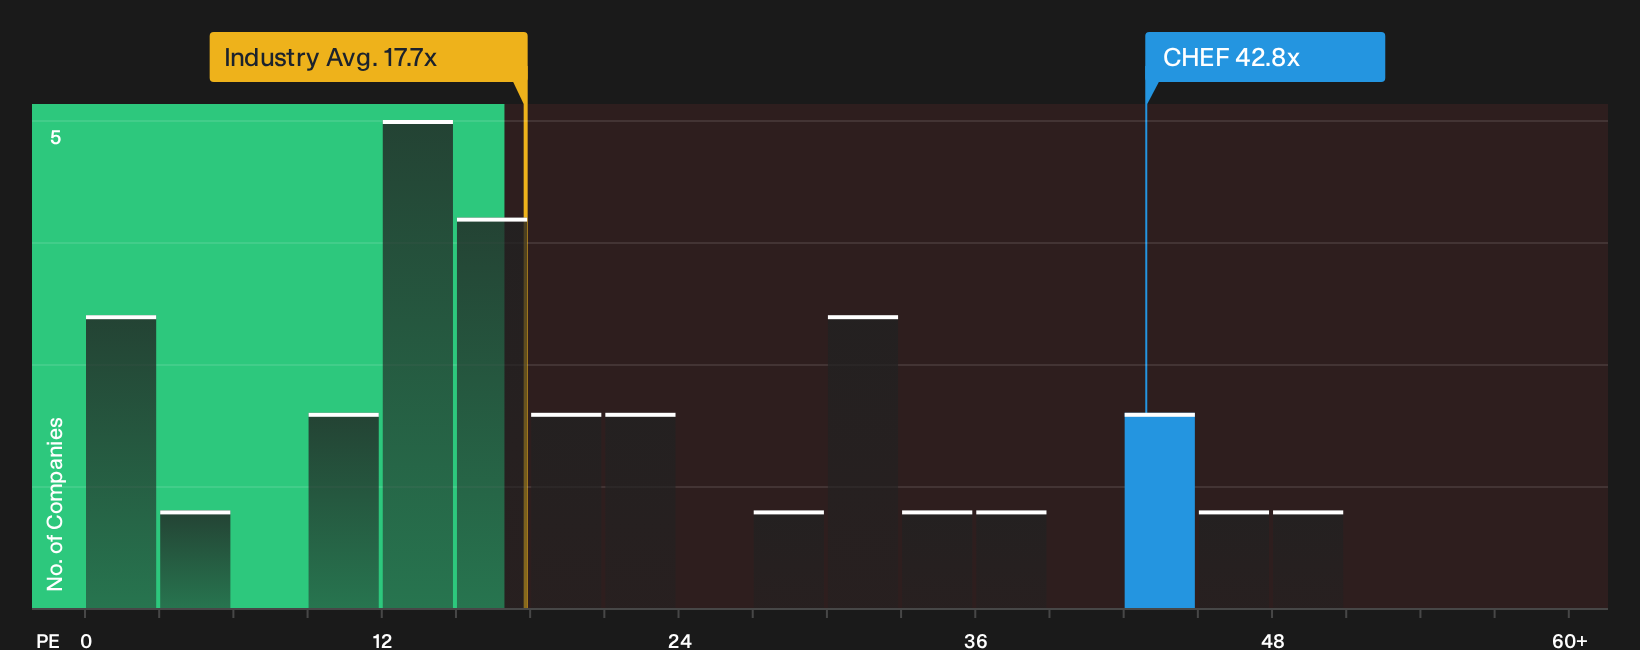
The first take paints Chefs' Warehouse as undervalued on cash flow and fair value estimates. The P/E story looks very different. CHEF trades on a 42.8x P/E, compared with 17.8x for the US Consumer Retailing group and a fair ratio of 23.6x. That is a sizeable premium. It suggests less of a simple bargain and more of a bet that current earnings power is only part of the story.
For anyone weighing position size and risk, the key question is simple. Does that valuation gap reflect staying power in Chefs' Warehouse’s growth and profitability, or is it room for disappointment if expectations cool?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Chefs' Warehouse story looks promising, yet the mix of flagged risks and potential rewards is what really matters for your decision. To weigh that balance quickly and build your own view, start with the 4 key rewards and 2 important warning signs.
Looking for more Chefs' Warehouse style ideas?
If Chefs' Warehouse has your attention today, do not stop here. A few minutes with a focused screener could surface the next idea on your shortlist.
- Target resilient balance sheets and steady fundamentals by running the list of solid balance sheet and fundamentals (23 results) screener that filters for financial strength upfront.
- Hunt for mispriced opportunities by scanning the 35 high quality undervalued stocks screener that highlights quality companies trading below their assessed worth.
- Prioritise sleep at night holdings through the 30 resilient stocks with low risk scores screener that concentrates on businesses with lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com