


EN
The Call Soriana Bulls Got Right
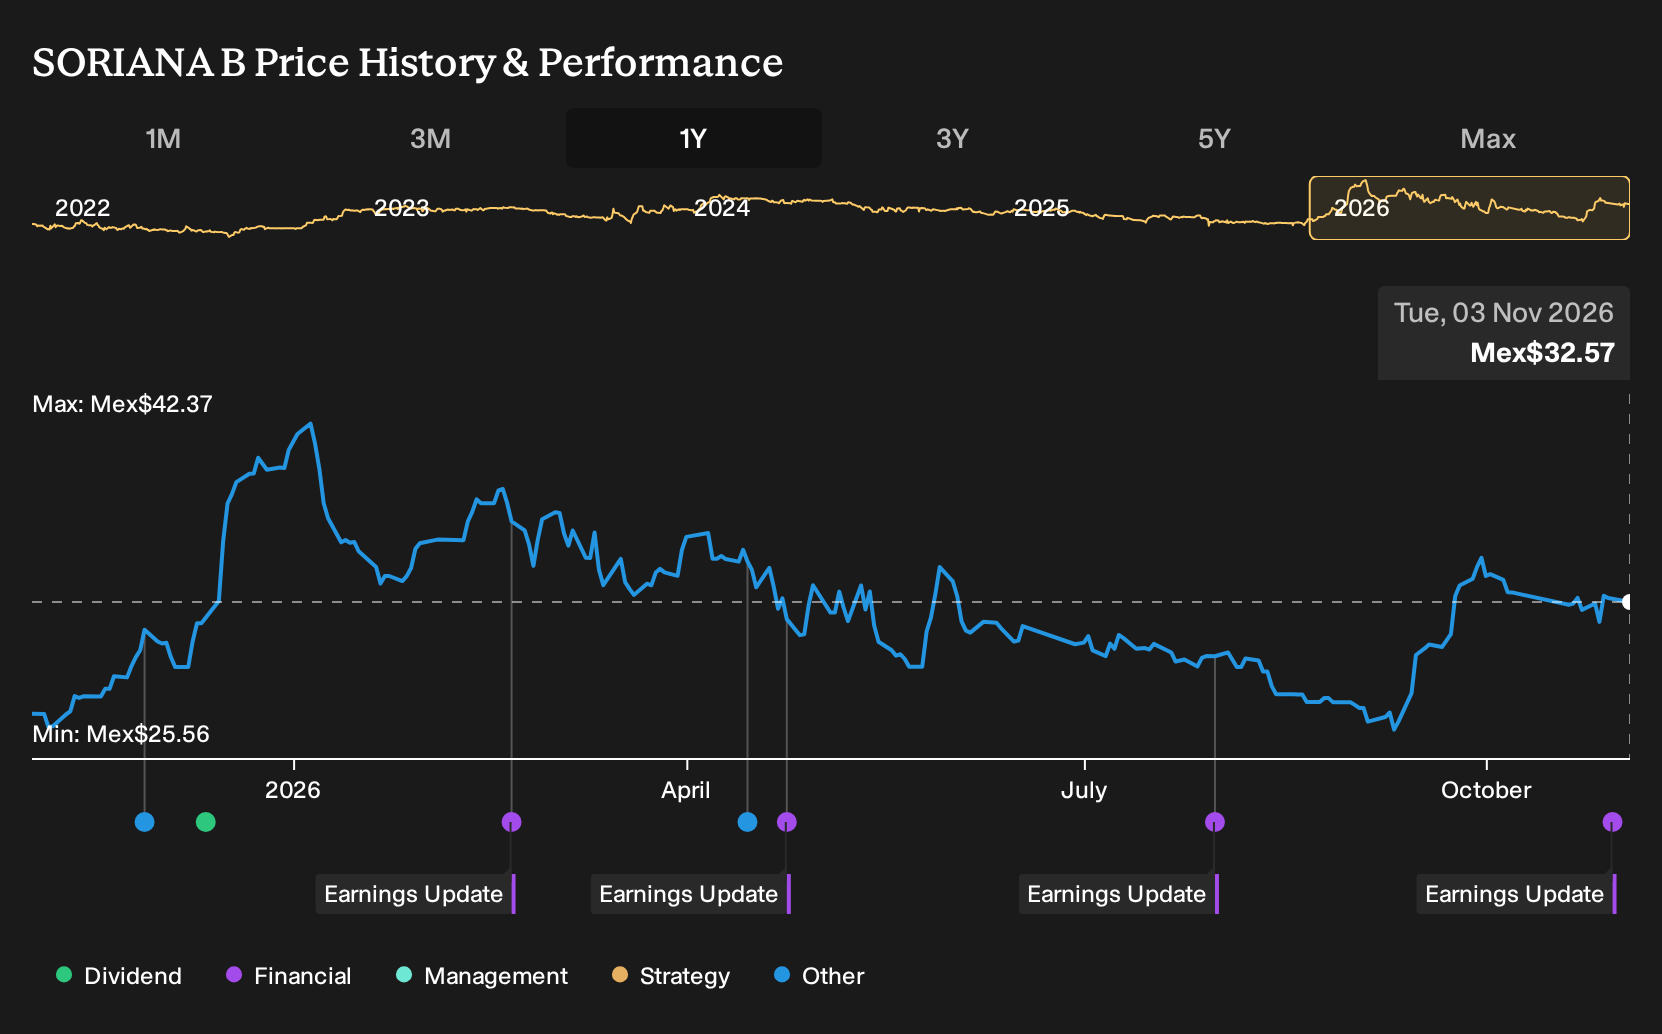
If you only saw Organización Soriana S. A. B. de C. V’s latest quarterly report, with revenue and profit both lower than a year earlier and net margin thinner, you might not expect much from the share price. For Organización Soriana S. A. B. de C. V shareholders, the return over the past year was 24.9%, including dividends. If you were weighing an investment in November 2025, how would the combination of optimism and clear risks have framed that outcome?
Organización Soriana S. A. B. de C. V has already moved. See which of 196 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On Organización Soriana S. A. B. de C. V
The shares cost MX$26.5 at the start of the period. Anyone looking at Organización Soriana S. A. B. de C. V then had to choose between two very different stories about where that price belonged.
On the bullish side, the optimistic Narrative pointed to a Fair Value of MX$33, a level implied by its own forecasts rather than a hard fact. Supporters leaned on rising private label penetration, digital sales and loyalty programs as potential drivers of better net margins and revenue.
The bear case put Fair Value nearer MX$23.43 and focused on weak store traffic and intense competition from both international and regional rivals. That cautious view also highlighted pressure from Mexico’s softer consumer backdrop as a key risk to future earnings.
What The Results Changed For Organización Soriana S. A. B. de C. V
The clearest new fact was weaker profitability. Organización Soriana S. A. B. de C. V reported Q3 2026 revenue of MX$40,833m and net income of MX$466m, both below Q3 2025, and net margin slipped from 1.4% to 1.1%. That undercut the more optimistic margin story and lent weight to the cautious case that competitive and cost pressures would be hard to shrug off.
The key lesson is simple. When a thesis leans heavily on margin improvement, treat net margin as the checkpoint. For another retailer, compare the forecast margin path with the one reported each quarter and decide whether you are paying for efficiency gains that have yet to appear.
What Soriana’s Current Price Already Assumes
Organización Soriana S. A. B. de C. V now trades at MX$32.57. The selected Narrative views its Fair Value as sitting below that level, since it argues the market already credits Soriana for progress in private labels, digital channels, loyalty programs and real estate income.
In practical terms, a buyer today is assuming those margin and earnings pillars keep holding up. The question is how that assumption lines up with the Narrative’s concern about recent pressure on revenue and same store sales.
"The current valuation implies the share price already prices in successful execution on private label, digital, loyalty and real estate initiatives even though recent revenue and same store sales trends have been weak, which supports a view that Soriana may be overvalued."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Before The Next Story Makes Headlines
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 38% below our estimate - helps clients tackle complex technical, safety and regulatory issues through specialist expertise.
- Company 2 - 18% below our estimate - adds sales headcount to pursue maintenance contracts and strengthen regional customer density.
- Company 3 - 34% below our estimate - expands digital capability and store rollout to convert traffic into higher-margin omnichannel sales.
That is three of the list. See all 196 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com