


EN
Western Digital (WDC) Could Be 5% Overvalued After Strong Results And Dividend Hike
Western Digital (WDC) just paired strong fiscal Q1 2027 results with a higher payout, reporting US$4,381 million in sales, US$1,779 million in net income and lifting its quarterly dividend by nearly 17%.
Western Digital’s recent results arrive after a sharp reset in the chart, with the share price down 16.36% over 30 days and 33.10% over 90 days, yet still showing an 85.06% year to date share price return and a very large 3 year total shareholder return that points to momentum built over a longer stretch rather than the last few weeks.
Scan how Western Digital’s earnings and dividend reset compares with peers leaning into AI and cloud capacity by reviewing the hand picked 53 AI infrastructure stocks.
Western Digital now trades at a steep discount to both analyst targets and some intrinsic value estimates after a sharp pullback. Is that a simple mispricing, or a signal that the market’s caution on this HDD focused story has merit?
Most Popular Narrative: 5.3% Overvalued
Western Digital last closed at $347.35, a touch above the narrative fair value of $329.76, so the story currently prices in a premium that asks investors to judge how durable today’s profitability really is.
Which brings the whole debate down to a single assumption. This narrative assumes net margins settle near 23% over the next 10 years. That is well below today's flattered 54%, and below the true underlying peak too, but it is still far above the roughly 7% the wider tech hardware industry earns. In plain terms, it assumes WDC keeps most, but not all, of its newfound pricing power. The market is already paying up for the optimistic end of that range, so the margin you believe in is, more or less, the valuation you believe in. Trust the oligopoly to hold, and 23% may prove conservative. Trust Bezos, and it may prove generous.
See why 40 investors see Western Digital as 5% overvalued.
Result: Fair Value of $329.76 (OVERVALUED)
Still, Western Digital’s story could unravel quickly if hyperscaler AI spending cools faster than expected or if an aggressive rival adds capacity and undercuts pricing power.
Find out about the key risks to this Western Digital narrative.
Another View: Western Digital On Earnings Multiples
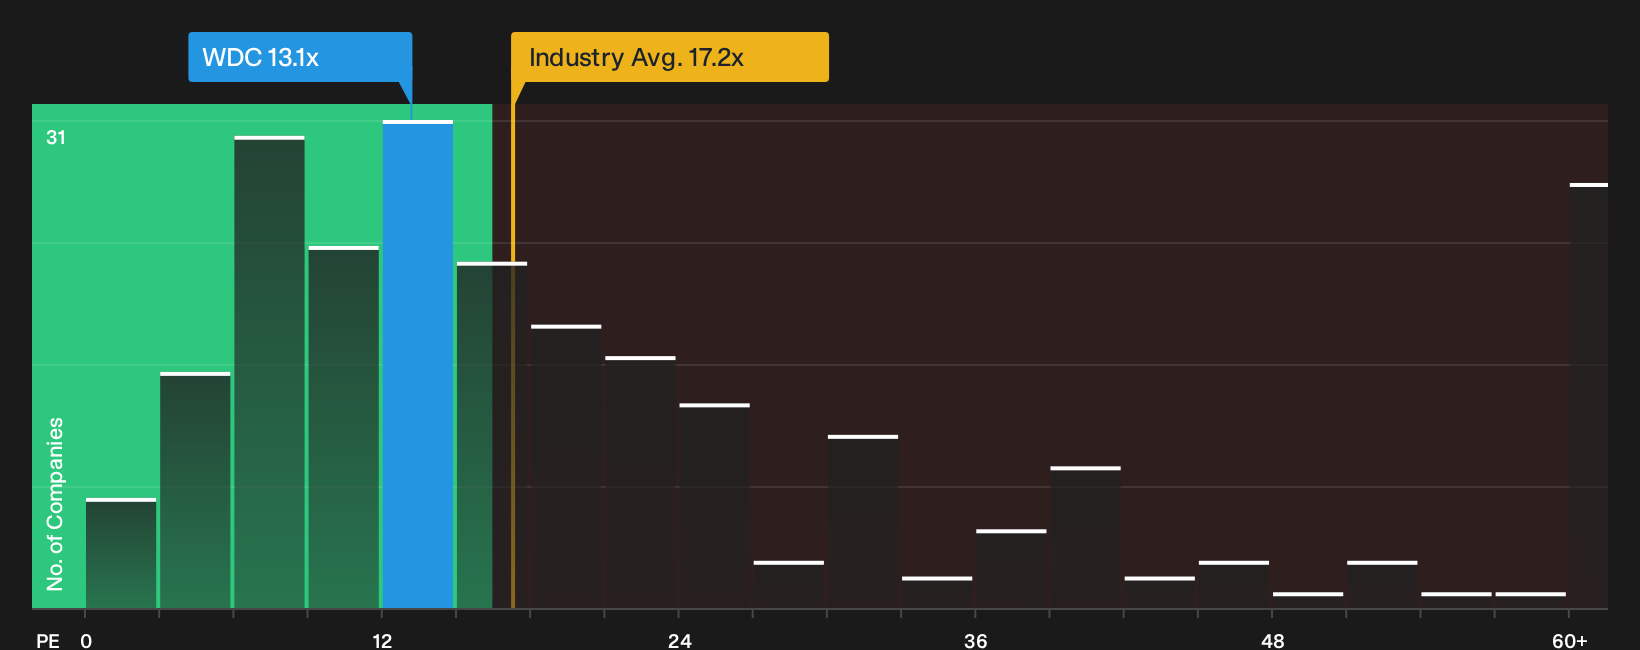
The narrative calls Western Digital about 5.3% overvalued at $347.35, yet the market is pricing the shares at a P/E of 13.1x. That is well below both the global tech sector at 17.2x and direct peers at 22.3x, and far under a fair ratio of 39.1x that the market could move toward.
Such a wide gap between a modest premium to narrative fair value and a low P/E against sector, peers, and fair ratio points to a different kind of risk. Is the crowd still anchored to old HDD fears while the earnings base has already reset?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of investors are split on Western Digital after this reset, so move quickly, look through the numbers yourself, and weigh the competing signals on risk and upside by reviewing the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Western Digital?
If Western Digital has you thinking harder about risk, reward, and timing, do not stop there. Use targeted screens to surface other opportunities that fit your style.
- Target resilient wealth builders by reviewing a 4 dividend fortresses that focuses on income potential supported by substantial cash payouts.
- Hunt for mispriced quality by checking a 35 high quality undervalued stocks that blends solid fundamentals with pricing that still looks conservative.
- Prioritise capital protection by focusing on a 30 resilient stocks with low risk scores that scores well on financial strength and volatility control.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com