


EN
Newell Brands (NWL) Stock May Trade At A Discount On Raised 2026 Outlook
Newell Brands has rallied hard over the past year, and with the stock now trading around US$5.63, the key question is whether that climb is supported by its sales base. After a period of heavy long term share price pressure, investors are again weighing what the current market value really says about the underlying revenue engine.
- The share price is up 91.6% over the past 12 months, which puts more focus on whether the business performance justifies that kind of reset.
- Recent updates pointed to rising sales and improved profitability, which can reshape how investors think about the link between Newell Brands' revenue line and the value they are placing on the stock.
- Your read on Newell Brands is one view; the desks covering it have another. See what analysts think Newell Brands's shares could be worth.
The stock's next move may depend on whether Newell Brands' current share price still lines up with what its sales suggest the business is worth.
If you want a wider lens on stocks where price is being weighed directly against sales, a focused screen of 35 high quality undervalued stocks is a useful next step for research.
Is Newell Brands a Bargain on Sales?
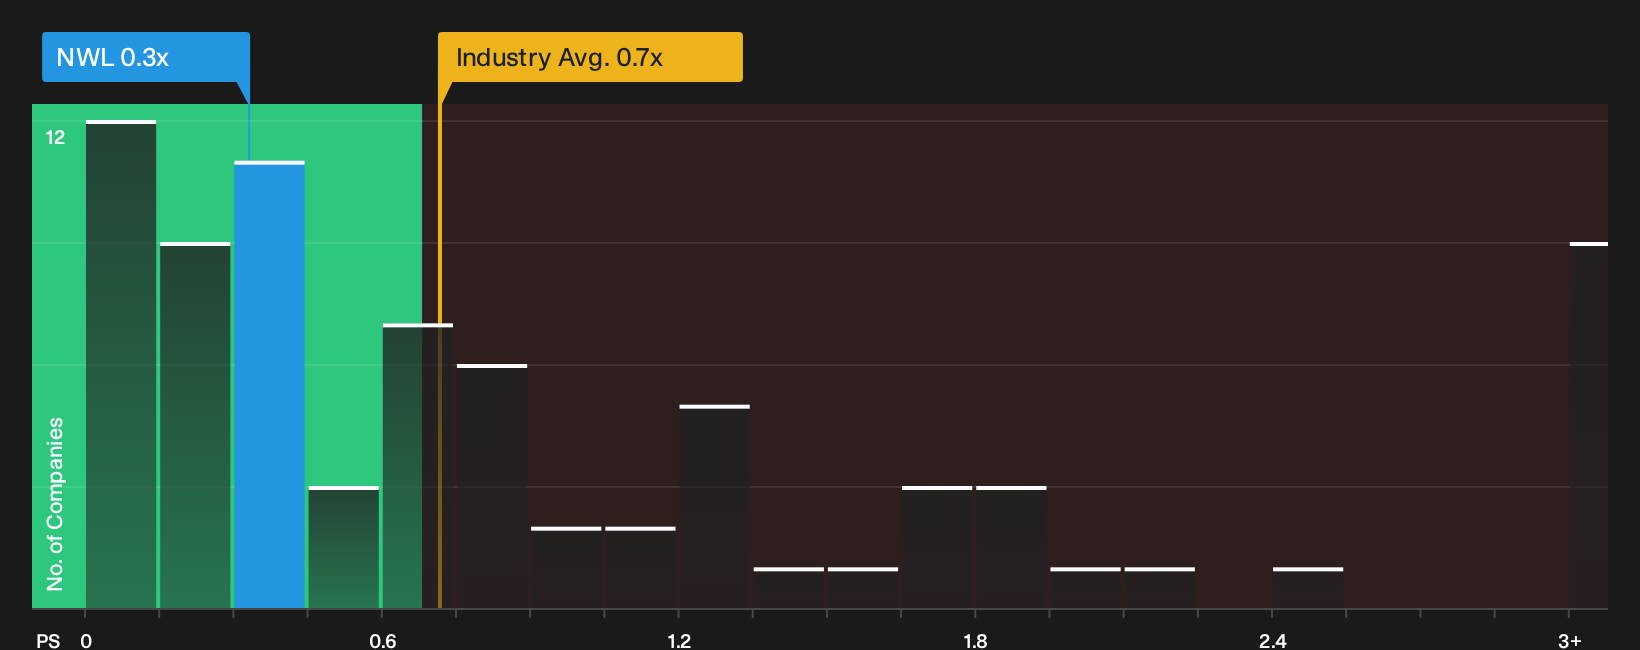
P/S is a useful yardstick for Newell Brands because investors are weighing the share price directly against its sales base rather than current earnings. On this measure, the stock trades on a P/S of about 0.3x, which is below both the Consumer Durables industry average of roughly 0.7x and the peer group at around 0.6x. The gap to a tailored fair multiple, which blends the company’s growth profile, margins, size and risk, also points to the shares pricing in a lower valuation than that framework would suggest.
Because Newell Brands recently beat Q3 2026 expectations and lifted its 2026 sales growth outlook, the current P/S discount indicates the market is still cautious despite those updates. For anyone comparing the share price to the revenue line, this multiple signals that the market is not paying as much for each dollar of sales as both the sector yardsticks and the fair value model might imply. Explore the numbers behind Newell Brands's P/S valuation.
The Newell Brands Narrative: What Would Justify Today's Price?
Newell Brands' valuation puzzle sets up the role of Simply Wall St Narratives. These map out the specific paths on growth, margins and earnings that would need to hold for the shares to be worth materially more or less than the current price. Each one anchors an estimate of fair value to a clear story about potential catalysts and risks, so you can track over time which version of events seems to be taking shape on the Community page.
Newell Brands splits opinions, with some community analysts leaning toward a reset story and others seeing fragile progress that is already priced in.
Bull case: 45% undervalued
"The surge in demand for the Coleman Snap 'N Go cooler, where 2026 revenue is tracking about 10x above the original forecast and the supply plan increased sixfold in a few months, hints at a wider playbook for Newell Brands to build repeatable hit products that can lift revenue growth and mix through premium pricing and higher volumes…"
Discover why this Narrative puts Newell Brands at 45% undervalued.
Bear case: 13% overvalued
"Although Newell Brands reports several years of gross margin expansion supported by productivity programs, the nearly US$126 million of IEEPA tariff recoveries booked in 2026 are explicitly one time…"
Explore why this Narrative puts Newell Brands at 13% overvalued.
One more Newell Brands signal worth checking before you move on
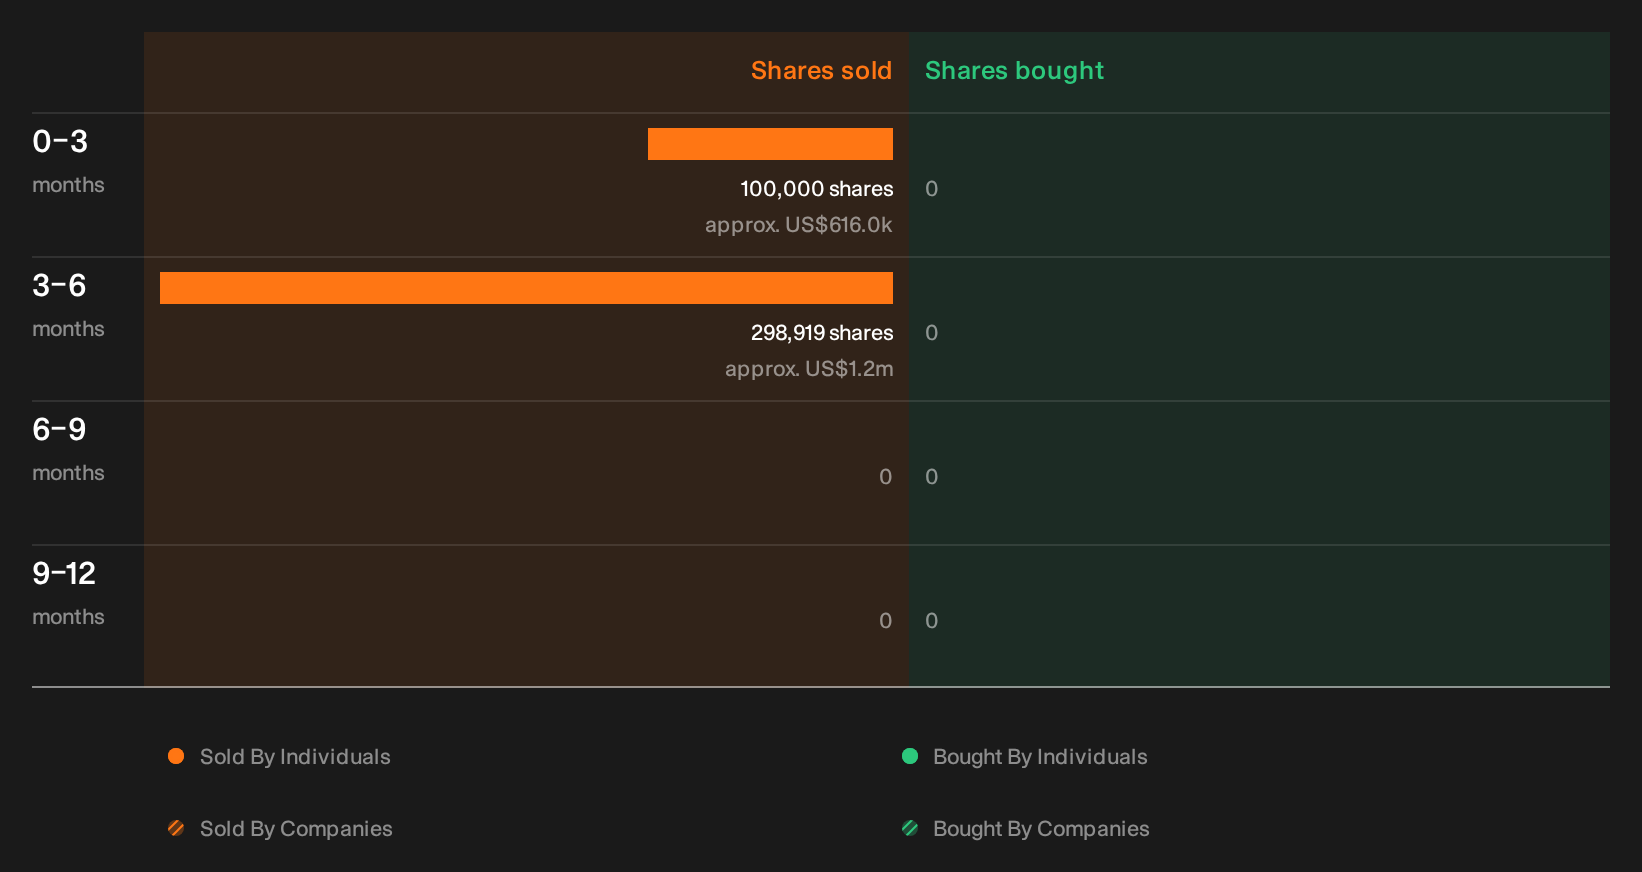
Before you close the book on Newell Brands, it is worth knowing that recent trading by people inside the business has been flagged by our checks and the sellers, sizes and potential read-throughs are all there for you to review. See the recent insider selling flagged for Newell Brands.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com