


EN
Learn Why The Bull Case For Cencora (COR) Could Change Following Strong Annual Earnings
- Cencora reported fourth quarter sales of US$88,354.53 million and net income of US$519.4 million, with full year revenue of US$337,397.3 million and profit of US$3,483.9 million. Basic and diluted earnings per share from continuing operations were sharply higher versus the prior year.
- The move from a net loss in last year’s fourth quarter to positive earnings per share this year indicates a meaningful swing in Cencora’s underlying profitability and operating execution.
- Investors can now consider how Cencora’s investment narrative might shift in light of its sharp full year earnings per share improvement.
Cencora Investment Narrative Recap
Cencora appeals to shareholders who believe a massive, low margin distribution engine can still compound value once operations are tuned and higher margin services scale. The step up in full year earnings per share to US$18.03, alongside US$337.4b in sales, reinforces that this model can translate very small margin shifts into large absolute profit.
In the near term, the key swing factor is whether specialty services, MSO platforms and international logistics keep offsetting pressure from generics, biosimilars and low profit GLP 1 volume. The main business risk remains mix shifts and contract changes that could dilute margin progress even if headline revenue stays healthy.
The most relevant data point right now is the latest full year earnings report to September 30, 2026. The company reported revenue of US$337.4b and net income of US$3.48b, compared with US$321.3b and US$1.55b a year earlier, with diluted EPS from continuing operations moving from US$7.96 to US$17.95.
This size of earnings step gives more room for Cencora to continue investing in digital tools and specialty platforms that analysts already highlight as important catalysts, while also addressing flagged issues such as high debt and contract exposure. It also raises the bar around execution risk if future quarters show slower contribution from those higher margin activities.
Cencora's current revenue trajectory is anchored by analyst assumptions of 5.7% yearly growth, with earnings today of US$2.6b expected to rise to US$3.4b by 2029. This US$0.8b increase underpins forecast revenue of US$393.3b and projected earnings of US$3.4b in that same year.
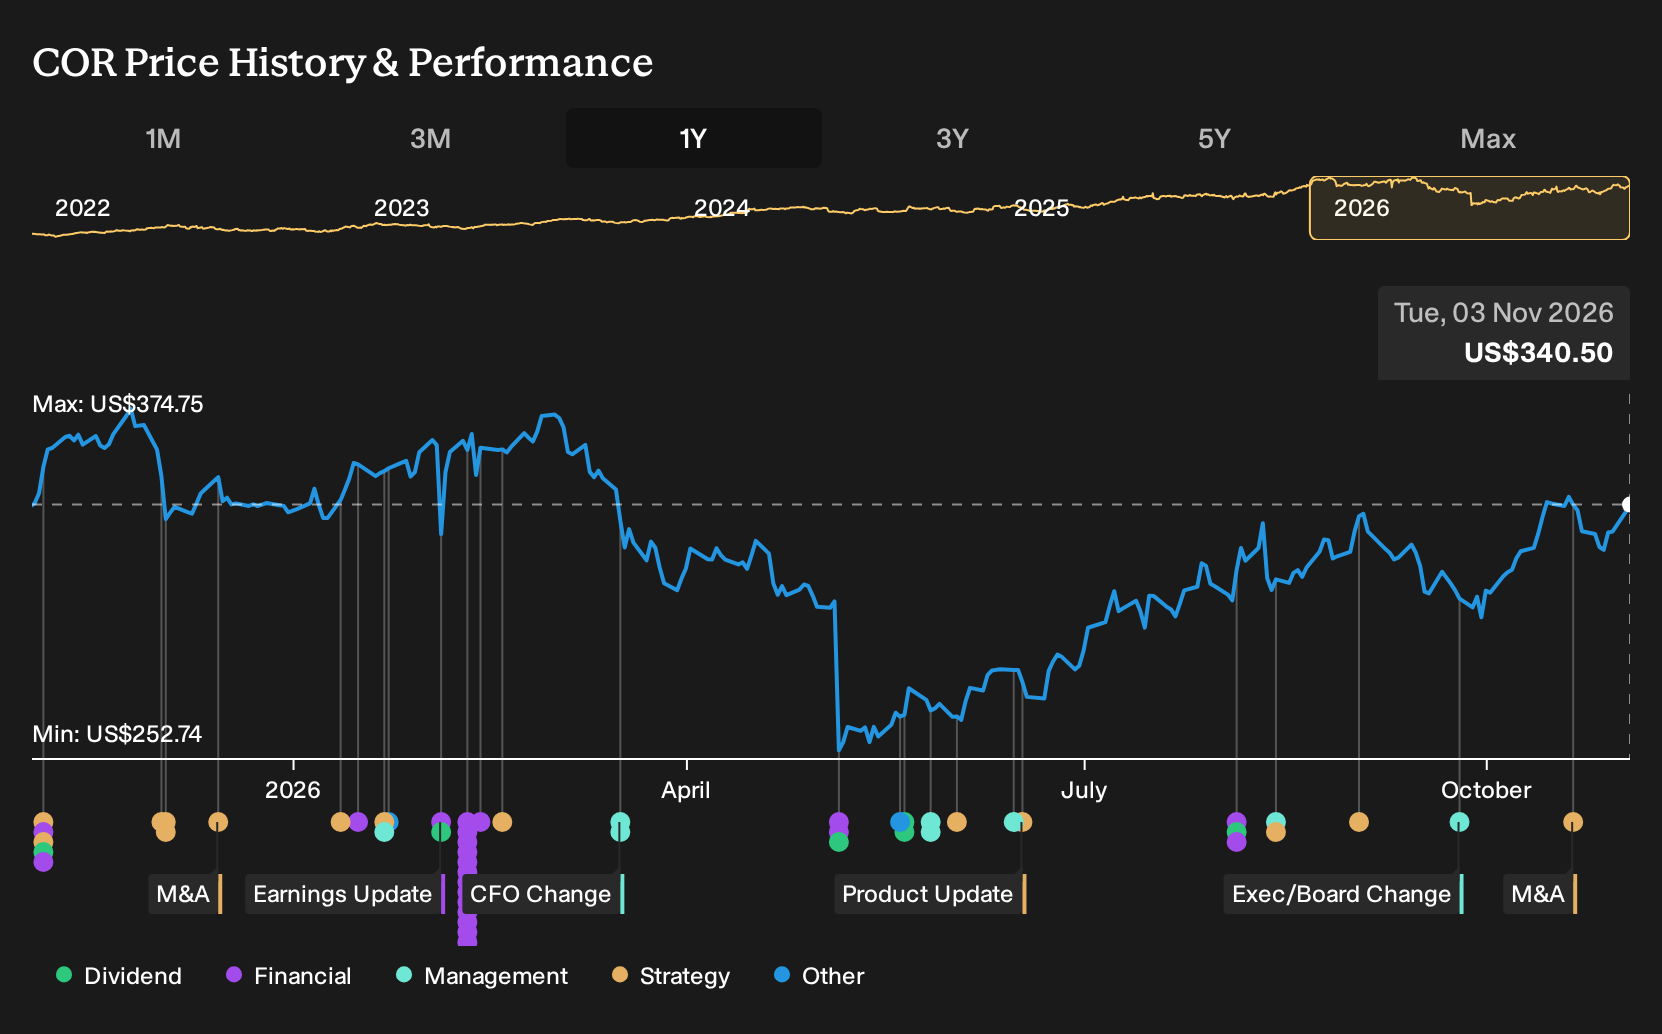
Uncover why Cencora's fair value indicates an 8% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on digital spending at Cencora. The most cautious analysts worried that heavy AI and automation costs could squeeze earnings, which is why they only pencilled in revenue of about US$372.4b and profit of roughly US$3.3b by 2029. Those estimates came before this earnings release, so their story may now evolve.
Explore 2 other Cencora fair value estimates, including one that suggests it could be worth just $369.31.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cencora research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cencora. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cencora's overall financial health at a glance.
Looking for more Cencora style investment ideas?
If Cencora's earnings swing has you rethinking what is possible when scale meets improving profitability, it can help to widen the lens and see which other businesses share similar traits using the Simply Wall St Screener.
- For investors hunting for mispriced quality, scan a curated set of companies that pair strong fundamentals with appealing valuations through 35 high quality undervalued stocks.
- If capital protection sits high on your list, filter for businesses with steadier profiles by running the 30 resilient stocks with low risk scores as a starting universe.
- When you want balance sheet strength to back up the story, focus your search using the list of solid balance sheet and fundamentals (23 results) and keep weak finances off your shortlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com