


EN
Treasury Wine Estates (ASX:TWE) Could Be 10% Undervalued After Portfolio Reset
Treasury Wine Estates (ASX:TWE) has been reshaping its portfolio, selling the Rosemount label to the Oatley family and exiting Seppelt as management chases higher quality revenue in a weak global wine market.
The recent reshaping of the portfolio has coincided with a sharp rebound in Treasury Wine Estates’ share price, with a 14.41% 1 month share price return and 20.72% 3 month share price return lifting the stock to A$6.35, even though the 3 year total shareholder return has declined 40.34%. This suggests that momentum has picked up after a difficult stretch for long term holders.
Compare Treasury Wine Estates’ portfolio reset with other potential rebound stories by scanning our hand picked 14 high quality undiscovered gems that combine solid fundamentals with quieter share price histories.
After a sharp bounce that still leaves Treasury Wine Estates well below its 3 year mark, is the current A$6.35 tag skewing the risk reward more toward fresh buyers or toward patience from the sidelines as portfolio changes bed in?
Most Popular Narrative: 10.2% Undervalued
The most followed narrative on Treasury Wine Estates pitches a fair value of A$7.07 per share against the last close of A$6.35, framing the recent rebound as a move that still leaves upside according to that framework.
At A$7.072 per share, Treasury Wine Estates (ASX: TWE) appears reasonably valued, although the assessment relies on earnings recovering during the second half of FY26. TWE reported first-half revenue of A$1.30 billion, EBITS of A$236.4 million and underlying earnings of 15.9 cents per share. Annualising these earnings gives a P/E ratio of approximately 22 times, although management expects second-half EBITS to exceed the first-half result and now forecasts FY26 EBITS of A$480 to A$490 million.
See why 8 investors see Treasury Wine Estates as 10% undervalued.
According to Jamesiskindacool, this storyline leans heavily on Treasury Wine Estates’ current portfolio and FY26 guidance rather than optimistic side assumptions. The author highlights that the view does not place major weight on the full A$100m annual cost reduction target, a sharp rebound in the US market or much stronger Penfolds expansion, and instead treats those as potential extras that depend on execution and external conditions.
Result: Fair Value of A$7.07 (UNDERVALUED)
Still, weaker US demand and a suspended FY26 interim dividend could pressure Treasury Wine Estates if progress in debt reduction or cash generation stalls.
Find out about the key risks to this Treasury Wine Estates narrative.
Another View on Treasury Wine Estates’ Valuation
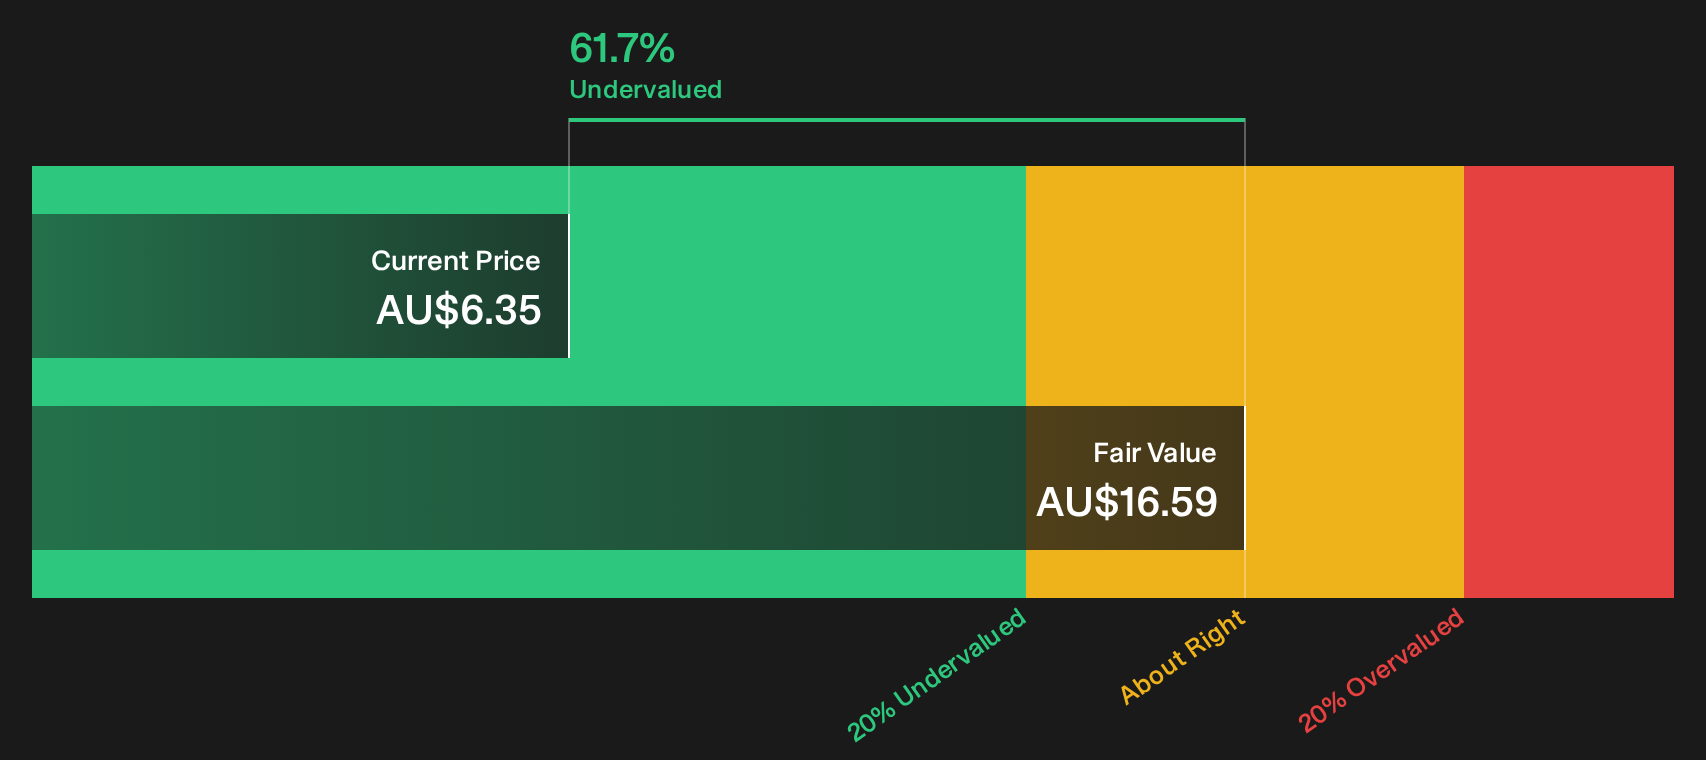
There is a sharp contrast between the A$7.07 fair value in the popular narrative and the SWS DCF model, which places Treasury Wine Estates at A$16.59 per share and therefore deeply undervalued. One model sees mild upside, while the other identifies a large gap. Which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Treasury Wine Estates is mixed, with clear risks on one side and genuine bright spots on the other. Move quickly and weigh both angles for yourself by checking the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Treasury Wine Estates?
If you stop your research with Treasury Wine Estates, you risk missing other setups that better match your goals, risk comfort, and dividend needs.
- Target income first and scan a curated group of reliable payers through the 5 dividend fortresses.
- Hunt for mispriced quality by filtering for companies that combine strong fundamentals with attractive pricing using the 4 high quality undervalued stocks.
- Prioritise capital protection and focus on resilient businesses with steadier profiles by checking the 6 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com