


EN
Ensign Group (ENSG) Lifts 2026 Outlook Following Q3 Results As Fair Value Stays In Focus
Ensign Group (ENSG) just delivered a busy late October, pairing Q3 earnings with an upgraded 2026 outlook that lifted both earnings and revenue guidance and sharpened investor focus on the stock.
That guidance lift arrived after a mixed stretch for Ensign Group’s stock, with a 5.39% 1 month share price return and a 4.77% year to date share price gain, but a 1 year total shareholder return that declined 3.92%. At the same time, the 3 year total shareholder return of 78.31% and 5 year total shareholder return of 126.44% point to momentum built over a longer horizon.
Scan other healthcare operators showing similar momentum to Ensign Group by reviewing the curated list of solid balance sheet and fundamentals (23 results).
Ensign Group has enjoyed a long stretch of strong shareholder returns, yet the recent share price has lagged the pace of its raised 2026 earnings outlook. Is most of the upside already captured, or is it still ahead as valuation resets?
Preferred P/E of 26.4x: Is it justified?
Valuation on Ensign Group today is being framed through a P/E of 26.4x, which sits above both its peer group and the broader US healthcare sector despite the stock trading at $182.21.
The P/E ratio compares the current share price to earnings per share and, for a healthcare operator like Ensign Group, it effectively reflects how much investors are willing to pay for every dollar of profit. A higher multiple often aligns with expectations of resilient profitability, solid execution and relatively predictable earnings in a sector where reimbursement, occupancy and operational discipline carry a lot of weight.
Here, Ensign Group trades on a P/E of 26.4x while the peer average sits at 15.8x and the US Healthcare industry average is 24.8x. This is a clear premium on both counts. That said, the estimated fair P/E of 27.3x implies the current multiple is much closer to what the SWS fair ratio suggests the market could move towards than the raw peer comparison alone might indicate.
Explore the SWS fair ratio for Ensign Group.
Result: Price-to-Earnings of 26.4x (ABOUT RIGHT)
Still, Ensign Group’s reliance on US healthcare reimbursement and its concentration in skilled nursing facilities could pressure earnings if funding rules or occupancy patterns change.
Find out about the key risks to this Ensign Group narrative.
Another view on Ensign Group’s valuation
The P/E comparison paints Ensign Group as roughly fairly valued, yet the SWS DCF model comes to a different conclusion. At a share price of $182.21 and a future cash flow value estimate of $161.09, the stock screens as overvalued on a cash flow basis. Which lens should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
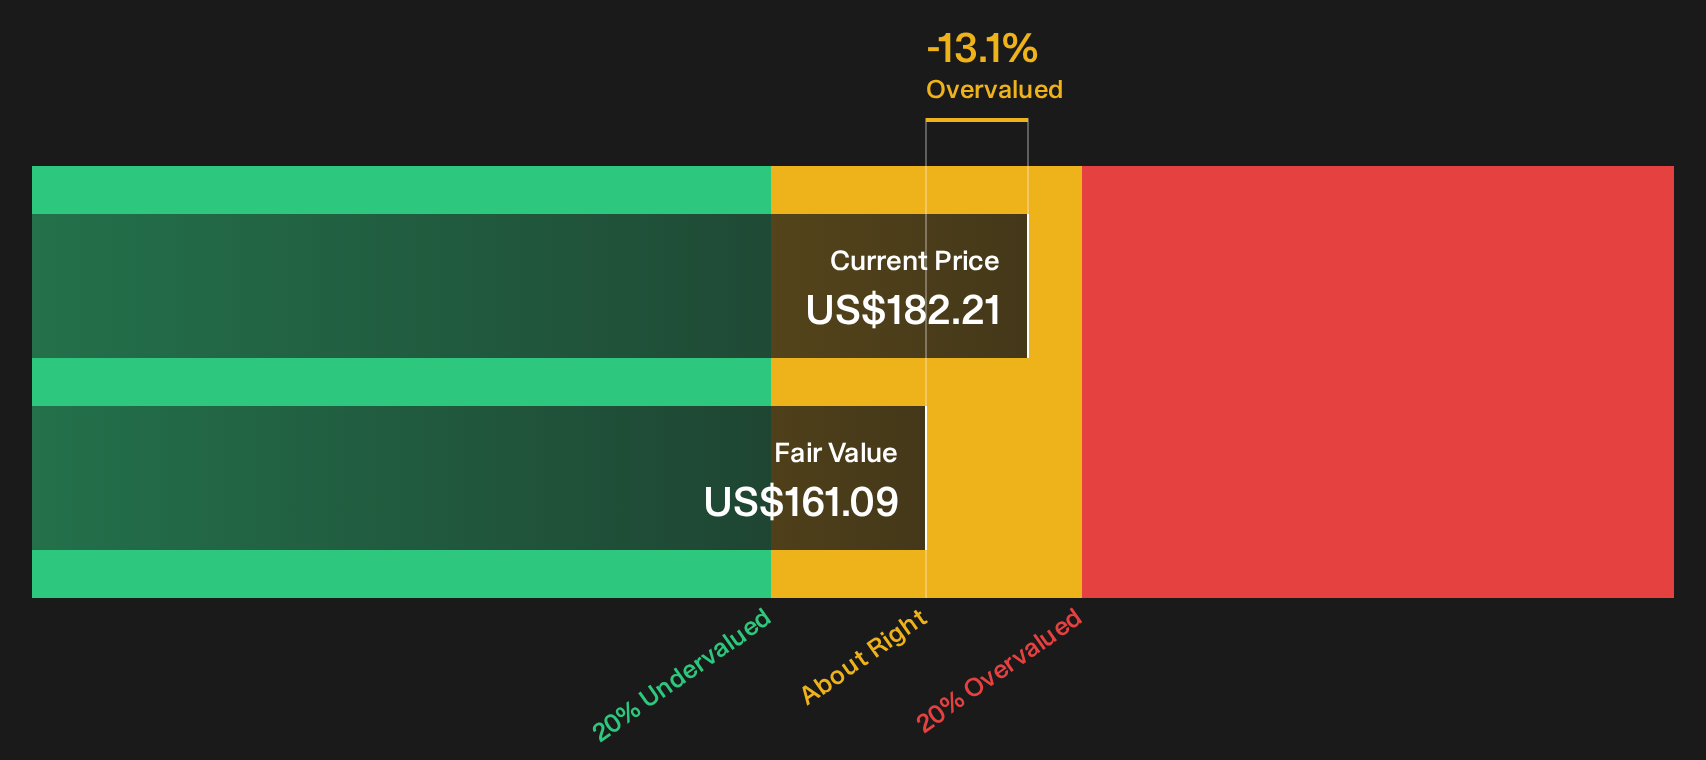
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ensign Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feel the cautious optimism in the Ensign Group story. Act before sentiment shifts, and weigh the upside and risks for yourself with the 3 key rewards.
Looking for more investment ideas beyond Ensign Group?
You do not need to stop with Ensign Group. Use the screeners below now so you are not left watching stronger opportunities pass by later.
- Target resilient balance sheets and steady fundamentals by reviewing the 30 resilient stocks with low risk scores that filters for businesses aiming to keep risk in check.
- Spot potential mispriced opportunities early by scanning the 19 high quality undiscovered gems that highlights companies with strong fundamentals that may not be widely followed yet.
- Build a watchlist of income-focused ideas using the 4 dividend fortresses that focuses on higher yield payouts backed by sturdier financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com