


EN
Texas Instruments (TXN) Stock May Be Fully Priced Despite Its $2 Billion Notes Sale
Texas Instruments has delivered a powerful run in recent years, and with the stock now around US$312, investors are asking whether that price still lines up with what its earnings can justify. After such a strong stretch, the market story and the profit story may not be telling the same thing.
- Over the past 3 years the share price return of about 133.5% puts a lot of weight on the question of how much earnings can support that kind of move.
- The planned US$2.0b senior notes issue to help finance the Silicon Labs acquisition can reshape how investors think about Texas Instruments' future earnings power versus its funding costs and capital needs.
- There is a second opinion on Texas Instruments worth weighing. See what analysts think Texas Instruments's shares could be worth.
The issue now is whether Texas Instruments' current share price is adequately supported by the earnings profile that investors are effectively paying for today.
If you want to pressure test the same earnings question that hangs over Texas Instruments against a broader slice of the market, scan through solid balance sheet and fundamentals stocks screener (23 results).
Is Texas Instruments Getting Expensive on Earnings?
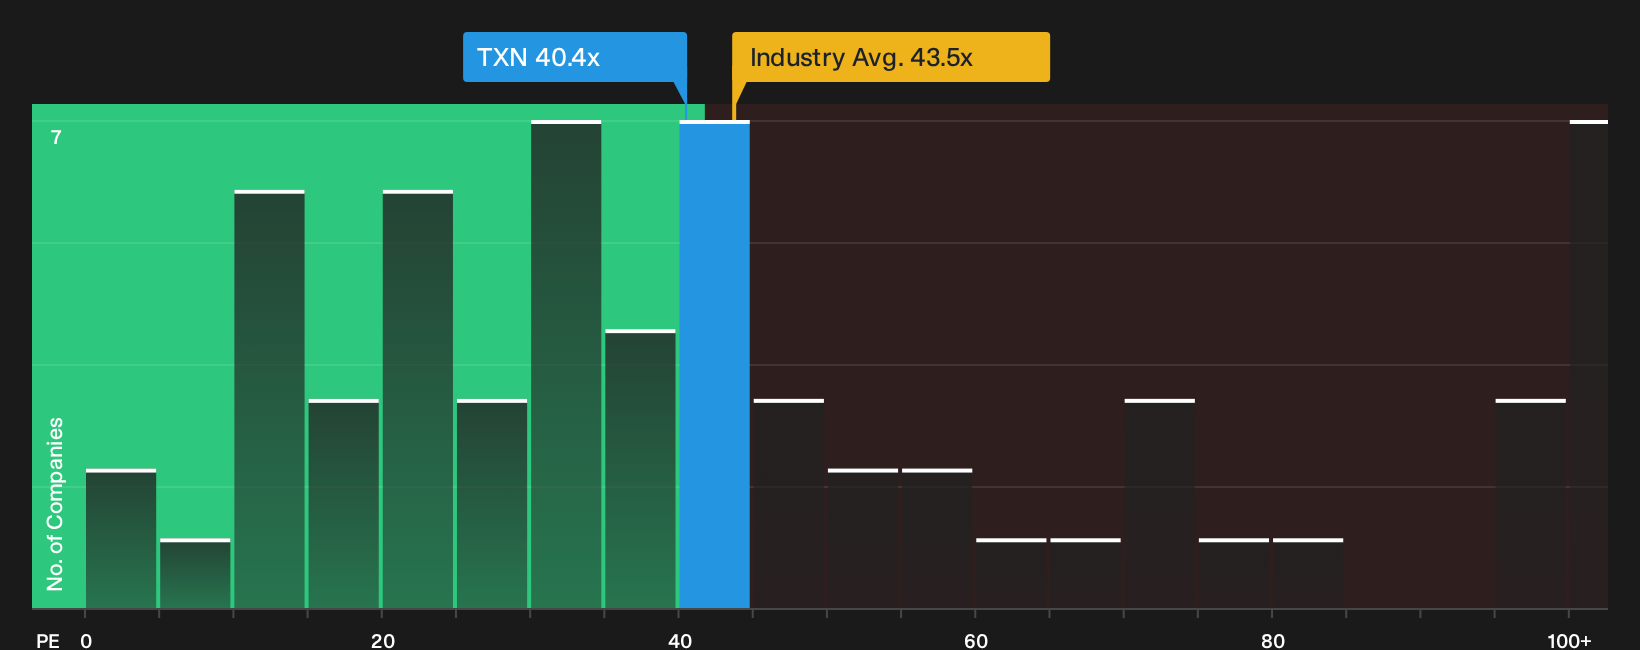
The P/E ratio is a useful quick filter for Texas Instruments because earnings remain the main anchor for how investors frame its value. On this measure, the stock trades on about 40.4x earnings, which is slightly below the broader semiconductor industry average of roughly 43.5x and sits well under the roughly 61.8x average for its listed peers.
The tailored fair multiple, which weighs Texas Instruments' size, profitability profile and risk factors, sits below where the shares currently trade, so the stock screens as overvalued on this framework even after that peer discount is taken into account. Because the US$2.0b senior notes will help fund the Silicon Labs acquisition, the market is now effectively paying a premium P/E for a business that is taking on extra debt to expand. This raises the bar for how those acquired earnings need to perform. Explore the numbers behind Texas Instruments's P/E valuation.
The Texas Instruments Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Texas Instruments and turn it into clear, testable scenarios for how future growth, margins and earnings would need to unfold for the shares to be worth materially more or materially less than today’s price, based on frameworks shared on the Community page. Rather than relying on a single P/E or model output, each narrative lays out the assumptions behind its estimated worth so you can compare them with actual results as they arrive.
Texas Instruments attracts two very different readings right now, with one group seeing meaningful upside and another flagging modest downside risk.
Bull case: 28% undervalued
"Texas Instruments is in the midst of a multiyear capacity-expansion cycle that is temporarily suppressing free cash flow but materially enhancing the company’s long-term competitive position…"
Discover why this Narrative puts Texas Instruments at 28% undervalued.
Bear case: 10% overvalued
"Watch: the 14,2 % growth input may be reading an analog cycle recovery as secular growth…"
Explore why this Narrative puts Texas Instruments at 10% overvalued.
One more Texas Instruments angle worth checking before you move on
Price multiples and scenario work only tell part of the story, because the analyst view of where Texas Instruments might be a few years from now offers a different reference point for you to compare with today. Explore where analysts expect Texas Instruments to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com