


EN
Higher Sales Lower Profit Might Change The Case For Investing In United Therapeutics Stock
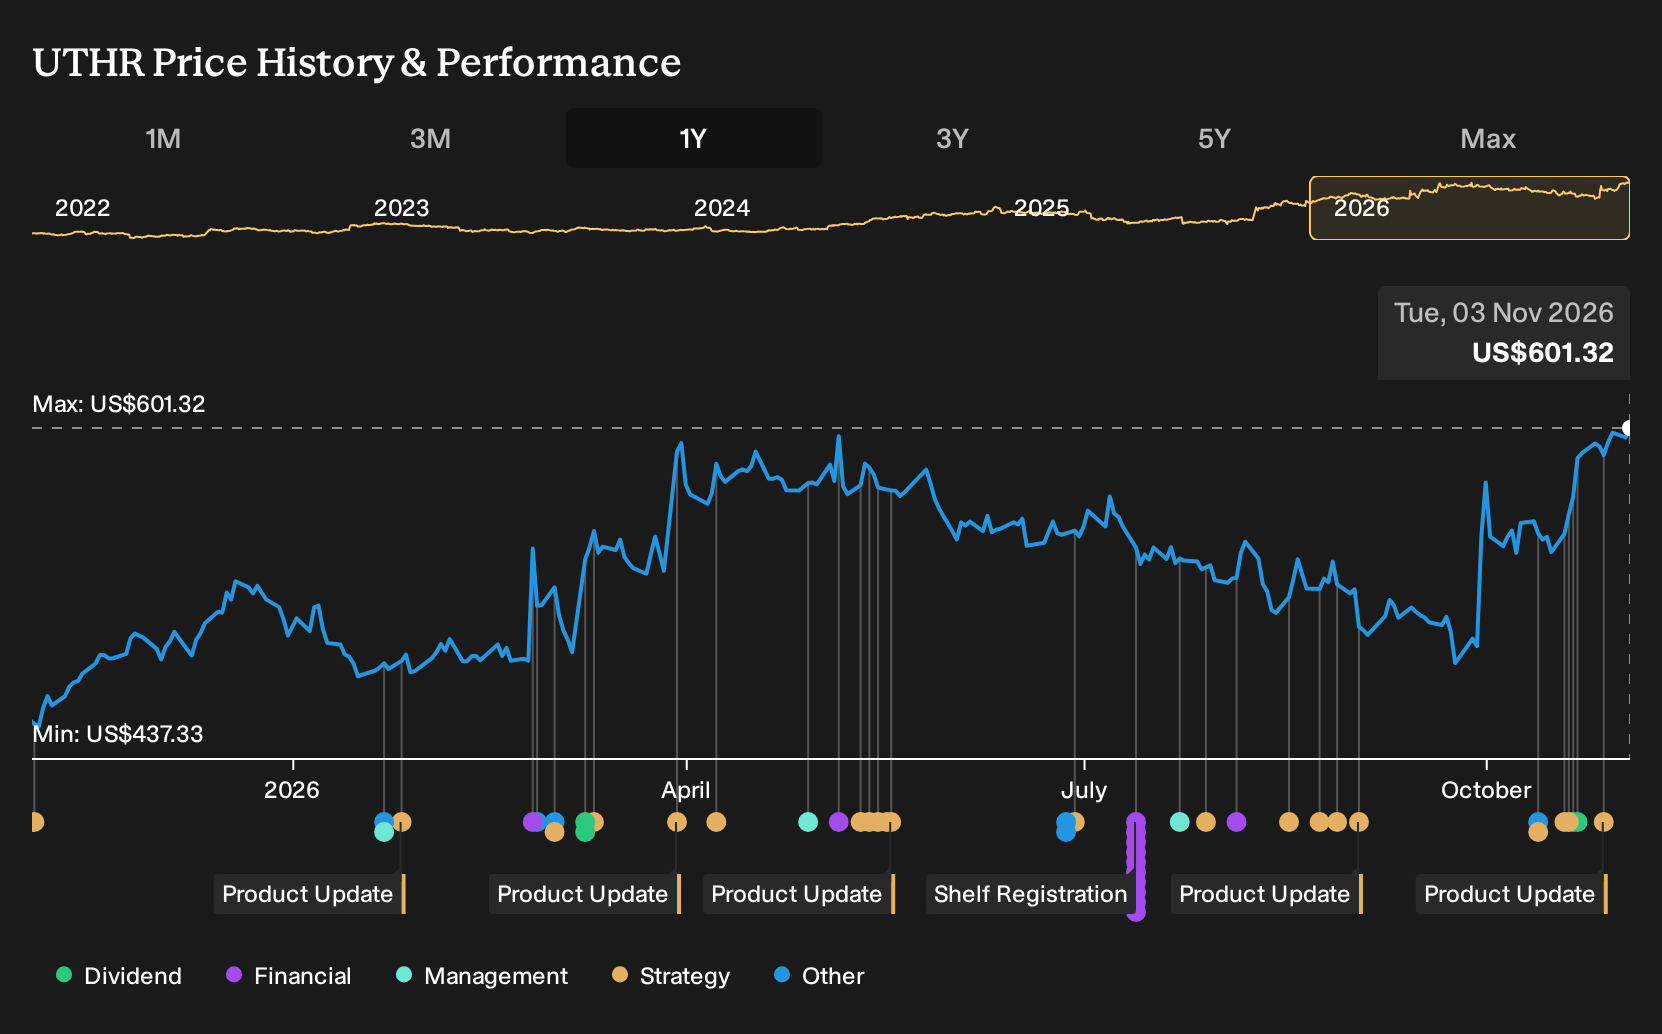
- United Therapeutics reported Q3 2026 results with sales of US$832.5 million and net income of US$258.6 million, along with lower basic and diluted EPS from continuing operations compared with the prior year.
- The mix of higher quarterly sales but softer profitability shifts attention to United Therapeutics’ cost structure and earnings quality at a time when product development and share repurchases remain active.
- The next section will examine how United Therapeutics’ investment narrative is influenced by higher revenue but reduced net income this quarter.
United Therapeutics Investment Narrative Recap
To be comfortable holding United Therapeutics, you need to believe the core pulmonary arterial hypertension portfolio can fund a long stretch of R&D while newer indications gradually pick up the slack. The latest quarter shows that revenue held up but net income and EPS softened, so the near term story is more about cost discipline and mix than raw sales momentum.
The key short term catalyst still sits with progress in Tyvaso and ralinepag related programs ahead of 2027 regulatory dates, and this quarter does not materially change that. The main risk remains pressure on the existing prostacyclin franchise from competitors, which could bite harder if operating expenses stay elevated against only modest top line movement.
The share repurchase activity around the current US$2.0b authorization is the announcement that most directly intersects with these earnings. United Therapeutics has already bought back 3,523,789 shares for about US$2.0b, including 980,394 shares in Q3 alone, at a time when net income for the quarter and year to date is softer than the prior period.
For you as an investor, that combination puts execution under a brighter spotlight. The firm is reducing its share count while EPS from continuing operations is down compared with last year, so the benefit to per share metrics depends on management keeping the pulmonary portfolio resilient and converting the current late stage pipeline into future cash flow without letting spending run ahead of returns.
United Therapeutics' narrative centers on analysts modeling US$4.5b in revenue and US$1.9b in earnings by 2029. This projection assumes 12.9% yearly revenue growth and an earnings increase of about US$600m from the current US$1.3b base.
Uncover how United Therapeutics' fair value indicates a 12% potential upside to its current price before the market closes that valuation gap.
Exploring Other Perspectives
One alternate view puts the recent Treprostinil-Iloprost SMI trial clearance at the center of the United Therapeutics story. In that more optimistic script, bullish analysts were already penciling in revenue of about US$5.4b and earnings of roughly US$2.4b by 2029. The latest Q3 earnings and heavy buybacks could reshape those expectations in either direction, so use this news to pressure test which scenario you find more convincing.
Explore 3 other United Therapeutics fair value estimates, including one that suggests as much as 246% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your United Therapeutics research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for United Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Therapeutics' overall financial health at a glance.
Looking for more ideas beyond United Therapeutics?
If this United Therapeutics update has sharpened your view on healthcare earnings, you can use that momentum to refresh the rest of your watchlist with a few focused stock searches built around quality, resilience, and upside potential.
- For investors who want to lean toward financial strength and balance sheet resilience, you can start with a list of solid balance sheet and fundamentals (23 results) that already filters for robust fundamentals.
- If your priority is finding companies that trade below what their cash flows and assets might justify, you can scan through 35 high quality undervalued stocks to help surface ideas for deeper research.
- For readers building a portfolio that leans on income rather than just price moves, consider using 4 dividend fortresses to focus your search on higher yielding options with an emphasis on staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com