


EN
How Investors May Respond To Iovance Biotherapeutics (IOVA) Biomarker Guided Lung Data
- Iovance Biotherapeutics reported updated Phase 2 IOV-LUN-202 data in previously treated non-squamous metastatic non-small-cell lung cancer, highlighting a 24.6% overall response rate and a 59.1% response rate within a biomarker-enriched subgroup that informed the launch of the POSITILITY registrational-intent cohort.
- The precision TIL approach, focused on KRAS and HER2 wild-type tumors in current or former smokers, targets a defined slice of the U.S. lung cancer population and could influence how Iovance deploys lifileucel across multiple indications and treatment lines.
- This analysis will examine how Iovance Biotherapeutics' investment narrative is affected by lifileucel's biomarker-enriched TIL strategy in metastatic lung cancer.
Compare Iovance Biotherapeutics' precision oncology push in lung cancer with a curated set of other potential breakout opportunities across 19 high quality undiscovered gems that are still flying under most investors' radar.
What Is Iovance Biotherapeutics' Investment Narrative?
Iovance Biotherapeutics is essentially a bet that tumor infiltrating lymphocyte therapy can scale beyond melanoma into several solid tumors, with Amtagvi and Proleukin funding an increasingly broad lifileucel pipeline. The updated lung data and the POSITILITY and OPTILISM plans fit directly into that story. They point to a more focused, biomarker led commercial opportunity in non squamous metastatic NSCLC, while still keeping lifileucel as a one time, high touch product that requires complex manufacturing, intensive support and meaningful capital to build out capacity and physician adoption.
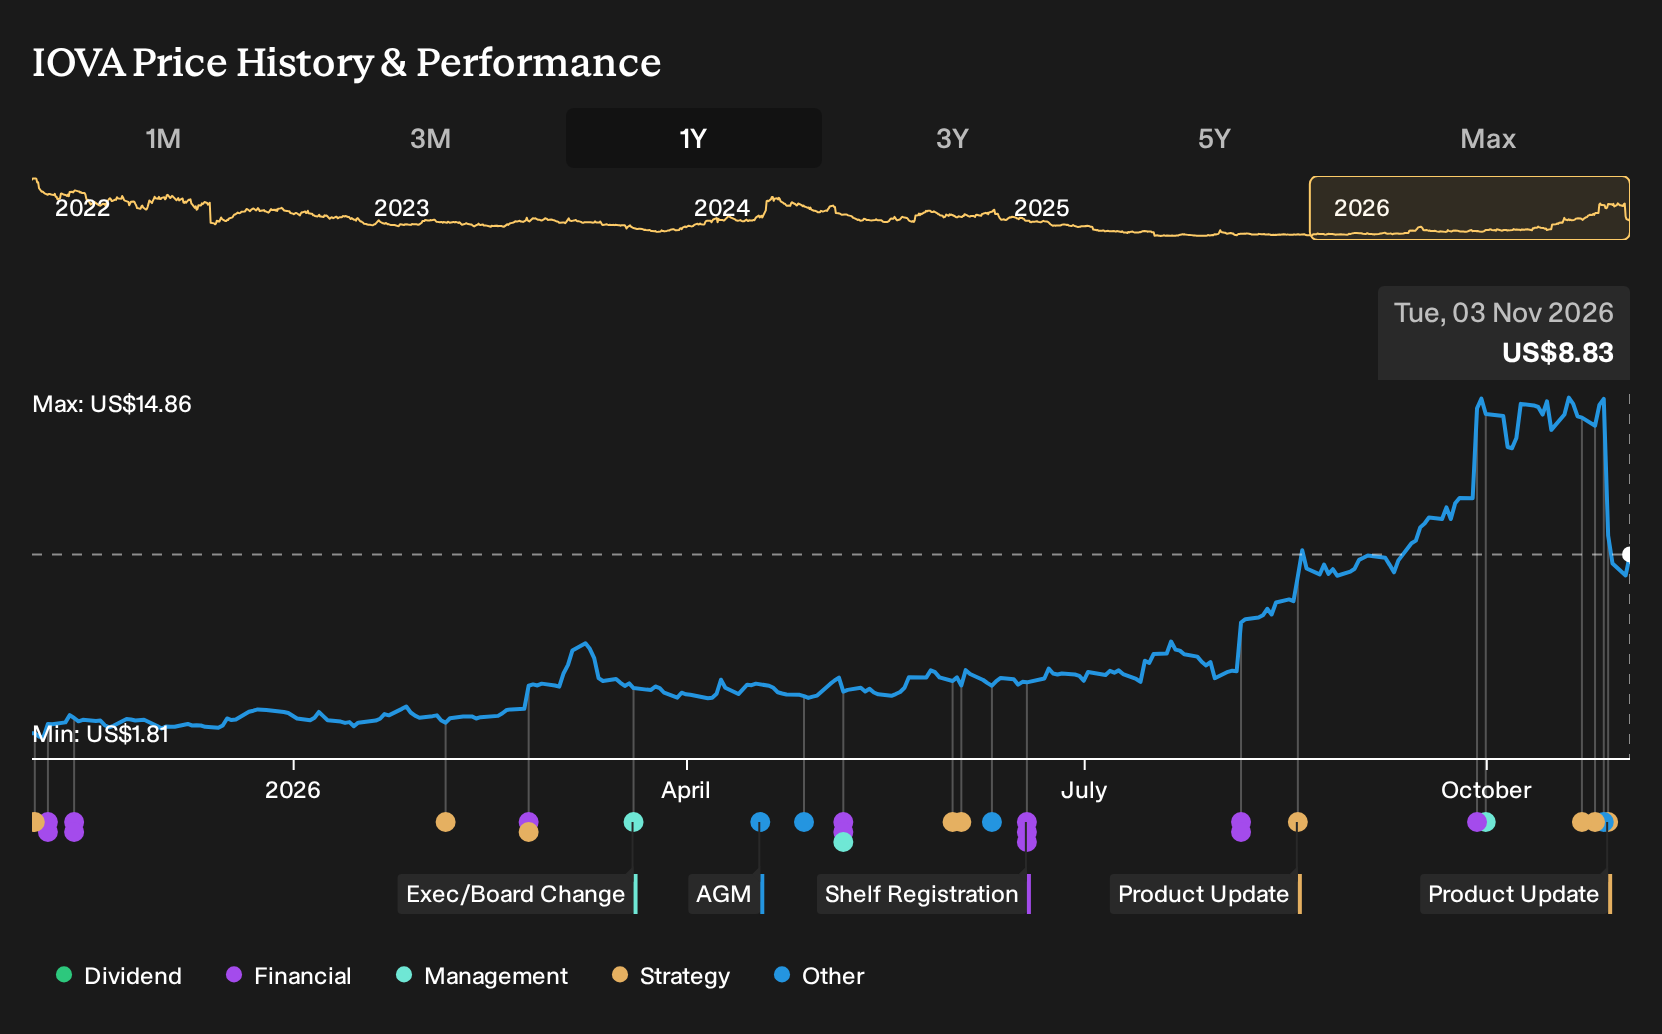
For a shareholder, the near term hinges on clean execution. That means keeping safety manageable as regimens evolve, hitting enrollment timelines, and turning current US$324.97m in revenue into something that can support an unprofitable, highly capital intensive platform. The recent lung update feeds into what many see as the key catalyst path, including the planned NSCLC sBLA in 2027 and ongoing Amtagvi uptake, but it does not erase familiar pressure points around cash needs, share dilution and a share price that has been highly volatile despite strong 1 year returns.
Even so, there is a less comfortable angle to the Iovance story that hinges on how much has to go right if...
There's only one way to know the right time to buy, sell or hold Iovance Biotherapeutics. Head to Simply Wall St's company report for the latest analysis of Iovance Biotherapeutics's Fair Value.
Exploring Other Perspectives
The lowest analysts focus on a different risk for Iovance Biotherapeutics. They worry that Amtagvi and Proleukin sales never scale enough to cover an expensive TIL platform, even with guidance lifted to US$410 million to US$420 million in 2026 revenue. Some were modeling revenue of about US$884.5 million and earnings of US$140.8 million by 2029, while others expected earnings to remain a loss near US$90.8 million. That gap shows how far opinions can stretch. Use this new lung data as a prompt to compare those forecasts yourself and consider which camp you find more realistic, knowing both views were set before the latest results.
Explore 5 other Iovance Biotherapeutics fair value estimates, including one that suggests as much as 21% downside from the current price!
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Iovance Biotherapeutics research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Iovance Biotherapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Iovance Biotherapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Iovance Biotherapeutics?
If the Iovance Biotherapeutics story has sharpened your interest in high risk, high reward situations, it can help to compare it with very different profiles on the market. A broad watchlist gives you context, helps you stress test your thesis, and can surface opportunities that better match your own tolerance for volatility and drawdowns.
- If you want potential high upside combined with tighter fundamentals, scan through 10 elite penny stocks with strong financials that pair smaller market values with balance sheets and income statements you can actually underwrite.
- For investors who care most about paying a reasonable price for quality, review the 35 high quality undervalued stocks and see which businesses currently screen as attractively priced based on cash flows and financial strength.
- If capital preservation ranks higher than chasing maximum return, work through the 30 resilient stocks with low risk scores and focus on companies that the Simply Wall St scoring framework flags with lower overall risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com