


EN
How Investors May Respond To Regeneron Pharmaceuticals (REGN) Earnings Beat
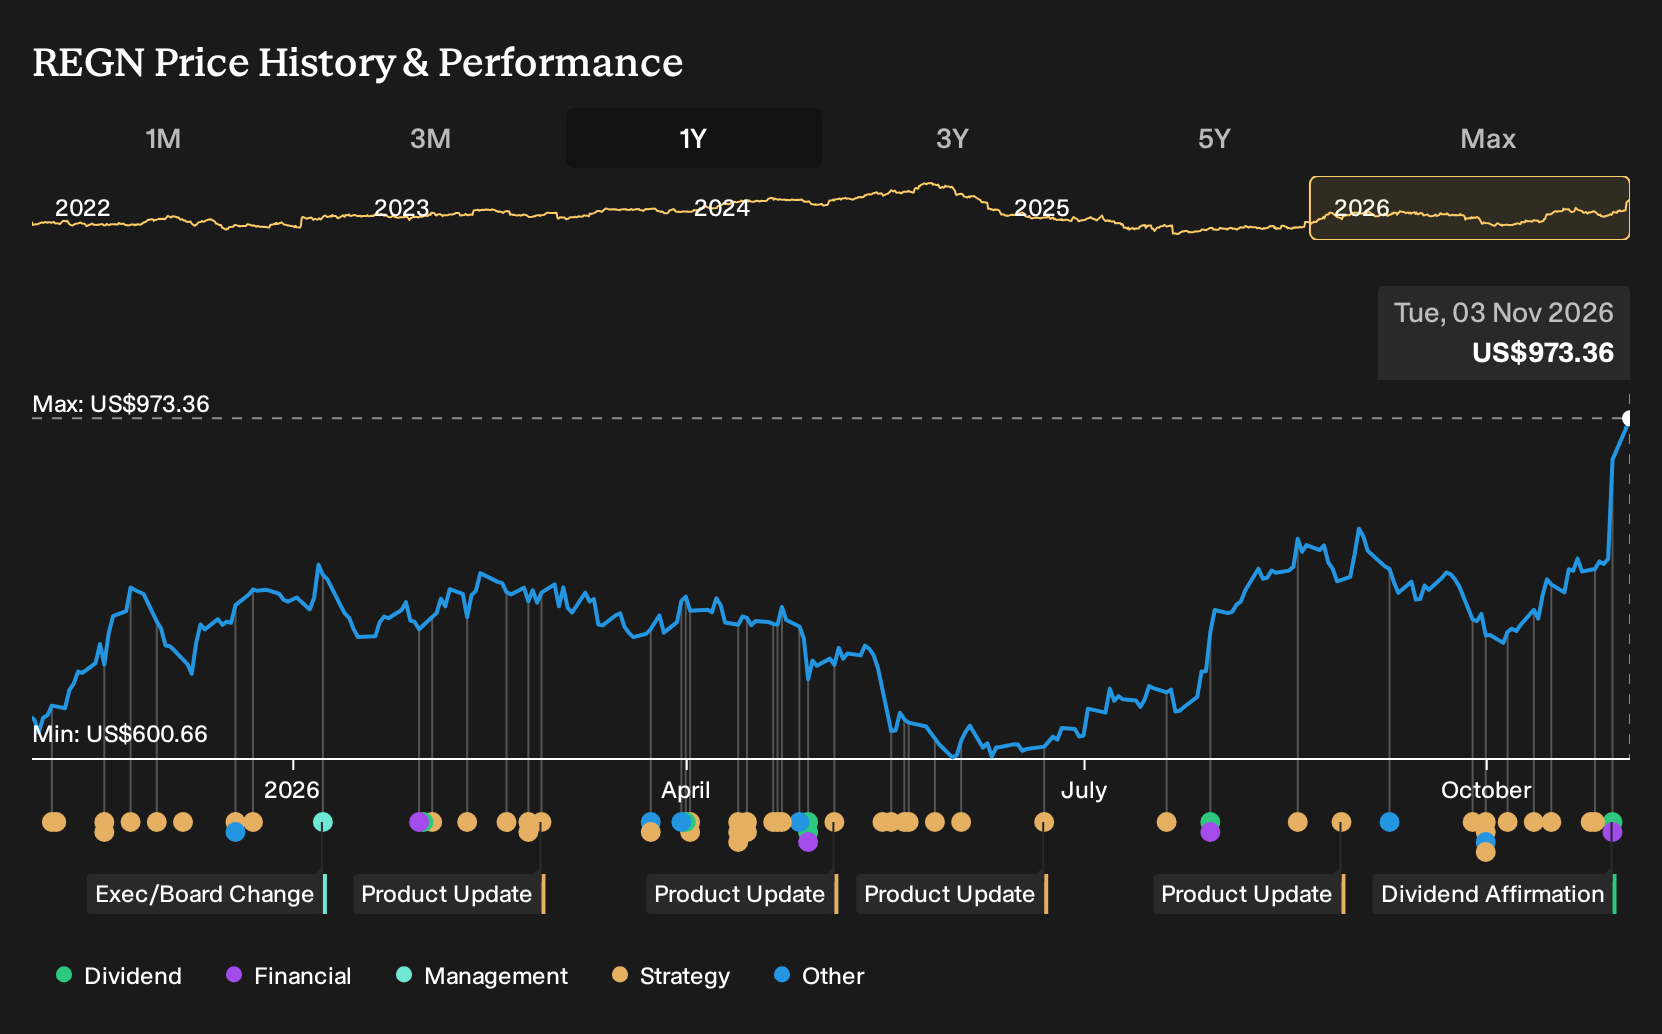
- Regeneron Pharmaceuticals reported third quarter 2026 revenue of US$5.1158b and net income of US$1.9487b, with basic earnings per share from continuing operations of US$19.16. The company also affirmed a quarterly dividend of US$0.94 per share announced on 30 October 2026.
- Along with these results, Regeneron Pharmaceuticals continued buybacks totaling about US$839.52m for 1.3% of shares and expanded its BARDA agreement for Ebola treatment Inmazeb by roughly US$270m, while presenting extended positive data for Libtayo in high risk skin cancer.
- The current focus is on how Regeneron Pharmaceuticals' stronger than expected quarterly earnings reshape its investment narrative and pipeline driven earnings profile.
Scan how Regeneron Pharmaceuticals’ earnings strength and dividend update compare with 30 resilient stocks with low risk scores to see which other businesses pair resilient balance sheets with durable cash generation.
Regeneron Pharmaceuticals Investment Narrative Recap
To own Regeneron Pharmaceuticals, you need to believe the core franchises Dupixent, EYLEA HD and Libtayo, together with a broad late stage pipeline, can keep funding disciplined R&D while weathering competition in eye care and pricing pressure. Fresh Q3 2026 results with US$5.1b in revenue and US$1.95b in net income support that earnings engine in the near term.
The near term swing factor is execution on late stage programs and regulatory decisions such as cemdisiran for generalized myasthenia gravis, alongside keeping EYLEA HD competitive as rivals emerge. The biggest risk is erosion in the retinal business or legal overhang from Libtayo related securities actions, which could reduce future earnings flexibility. Recent news does not fundamentally change those stakes.
The most relevant update for catalysts is the longer term Libtayo data in high risk cutaneous squamous cell carcinoma from the Phase 3 C POST trial. With a median follow up of 44 months, the study reported sustained disease free survival and an emerging overall survival signal despite high crossover from placebo to Libtayo, with safety broadly in line with prior reports.
For investors watching Regeneron Pharmaceuticals, this matters because it reinforces oncology as a second pillar beside Dupixent and EYLEA HD. A more durable evidence set can support label discussions, physician confidence and potential future use in high risk skin cancer. It also adds context around Libtayo’s scientific profile at the same time as legal proceedings around melanoma disclosures remain an ongoing overhang.
Regeneron Pharmaceuticals' current analyst narrative points to revenues of US$20.6b and earnings of US$6.7b by 2029, based on forecast yearly top line expansion of 9.9% and an earnings step up of about US$2.4b from US$4.3b today.
Uncover why Regeneron Pharmaceuticals' fair value points to an 11% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
Some of the lowest Regeneron Pharmaceuticals analysts focus on pipeline execution risk, especially around cemdisiran and other late stage trials, rather than the latest dividend and buyback news. These more cautious views were built on revenue growing about 5.3% a year and earnings reaching roughly US$6.9b by 2029, so you may see those narratives shift as fresh data and these Q3 results filter into new forecasts.
Explore 4 other Regeneron Pharmaceuticals fair value estimates, including one that suggests as much as 14% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Regeneron Pharmaceuticals research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Regeneron Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Regeneron Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Regeneron Pharmaceuticals?
Once you have a view on Regeneron Pharmaceuticals, it helps to compare it with other businesses that share some of the qualities you care about, whether that is income, value or balance sheet strength. The Simply Wall St screener gives you a fast way to line up alternatives and stress test your thesis against real data.
- If you want income to play a bigger role in your portfolio, take a look at 4 dividend fortresses that focus on consistent payouts and higher yields.
- For investors who care most about paying a sensible price for quality, start with 35 high quality undervalued stocks that combine stronger fundamentals with more modest market expectations.
- If resilience and financial strength sit at the top of your checklist, anchor your watchlist around the list of solid balance sheet and fundamentals (23 results) so you can compare Regeneron Pharmaceuticals with peers that also keep leverage and liquidity in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com