


EN
Super Micro Computer Posts Record $19.9 Billion Quarter, But 44% of Revenue Came From a Single Customer
Super Micro Computer (SMCI) delivered a record-shattering fiscal first quarter of 2027, reporting revenue of $19.9 billion — a staggering 298% surge year over year that blew past both its own pre-announced range of $18.5 billion to $19.5 billion and Wall Street's consensus estimate of approximately $16 billion.
Non-GAAP earnings per share of $1.81 crushed the analyst consensus of $1.23, representing a nearly 46% earnings surprise, while net income ballooned 849% year over year to $1.59 billion.
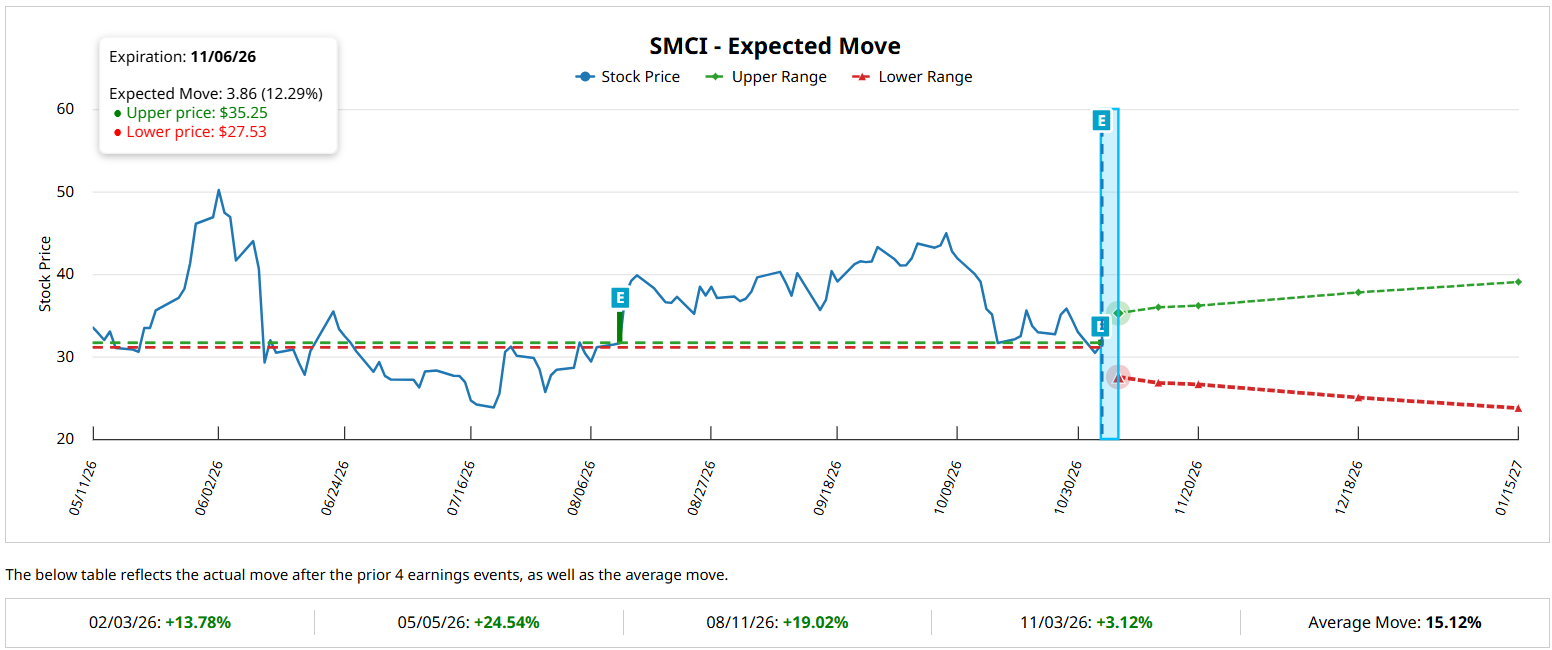
SMCI stock popped late Wednesday following the fiscal Q1 announcement, but has since erased those gains and is set to open roughly flat. With the November 6 options series pricing in a much more ambitious 12% swing for SMCI after earnings, premium buyers could be facing a tough post-event scenario this morning.
The Buried Number That Changes the Story
Beneath the blockbuster headline lies a striking concentration risk: a single large data center customer accounted for 44% of quarterly revenue, a level CFO Mark Long characterized as a consequence of the unprecedented scale at which AI infrastructure is being deployed.
AI solutions represented 71% of quarterly revenue, up sharply from 59% in the prior quarter, meaning Super Micro's fortunes are increasingly tethered to a narrow set of hyperscale buyers.
$2.3 Billion in "Catch-Up" Revenue Inflated the Beat
Management disclosed that approximately $2.3 billion of the quarter's revenue consisted of catch-up deployments originally scheduled for earlier periods, placing underlying revenue at roughly $17.6 billion.
That’s still impressive, but suggests a notable pull-forward effect that complicates the sustainability narrative.
Guidance Soars, Margins Compress
Super Micro raised its full-year fiscal 2027 revenue guidance to $72 billion to $82 billion from a prior range of $65 billion to $72 billion, and its fiscal second-quarter outlook of $19.5 billion to $21.5 billion also exceeded Street expectations by a wide margin.
Non-GAAP gross margin of 12.8% beat guidance but declined sharply from 17.6% in the prior quarter, reflecting the heavier mix of lower-margin large-scale AI deployments.
Management explicitly warned that second-half margins will fall below first-half levels as AI revenue trends toward the upper end of the 70% to 80% mix estimate, with the full-year gross margin outlook of 11.8% to 12.2% underscoring a structural tension between volume growth and profitability.
Cash Flow Flashes Red
Operating cash flow was negative $434 million during the quarter, and free cash flow was negative $481 million, even as Super Micro ended the period with $6.9 billion in cash against $8.6 billion in debt and convertible notes — resulting in $1.7 billion of net debt.
The cash conversion cycle improved meaningfully from 149 days to 97 days, but the working capital intensity of a hardware business scaling this rapidly demands continued vigilance, and mandatory convertible preferred stock issued last quarter carries a $75 million quarterly dividend burden that dilutes earnings per share.
Governance Overhang Hasn't Disappeared
A contractor's guilty plea involving illegal export of servers containing advanced AI chips to China, along with prior DOJ indictment-related charges involving senior employees, continues to shadow Super Micro.
The newly appointed CFO has emphasized embedding compliance into the corporate culture and expanding internal controls, but legal and regulatory risks remain unresolved — and SMCI shares have cratered roughly 33% over the past year and 27% over the past month alone, partly reflecting these governance concerns alongside a Gartner report questioning the viability of neocloud customers.
Cheap for a Reason?
At approximately 5.6 times forward earnings — a fraction of peers in the AI infrastructure buildout — and with an analyst consensus rating of “Hold,” SMCI stock’s valuation appears optically cheap.
Thin margins, negative cash flow, extreme customer concentration, and unresolved compliance issues suggest the risk-reward calculus remains precarious despite the record top-line performance — a reminder that in hardware, revenue without margin durability is a story Wall Street has learned the hard way before.
To explore a lineup of more Data Center Stocks to screen for investing ideas, check out our curated watchlist.
This article was created with the support of automated content tools from our partners at Sigma.AI. Together, our financial data and AI solutions help us to deliver more informed market headline analysis to readers faster than ever.
On the date of publication, Sarah Holzmann did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.