


EN
The Call CK Asset Bulls Got Right
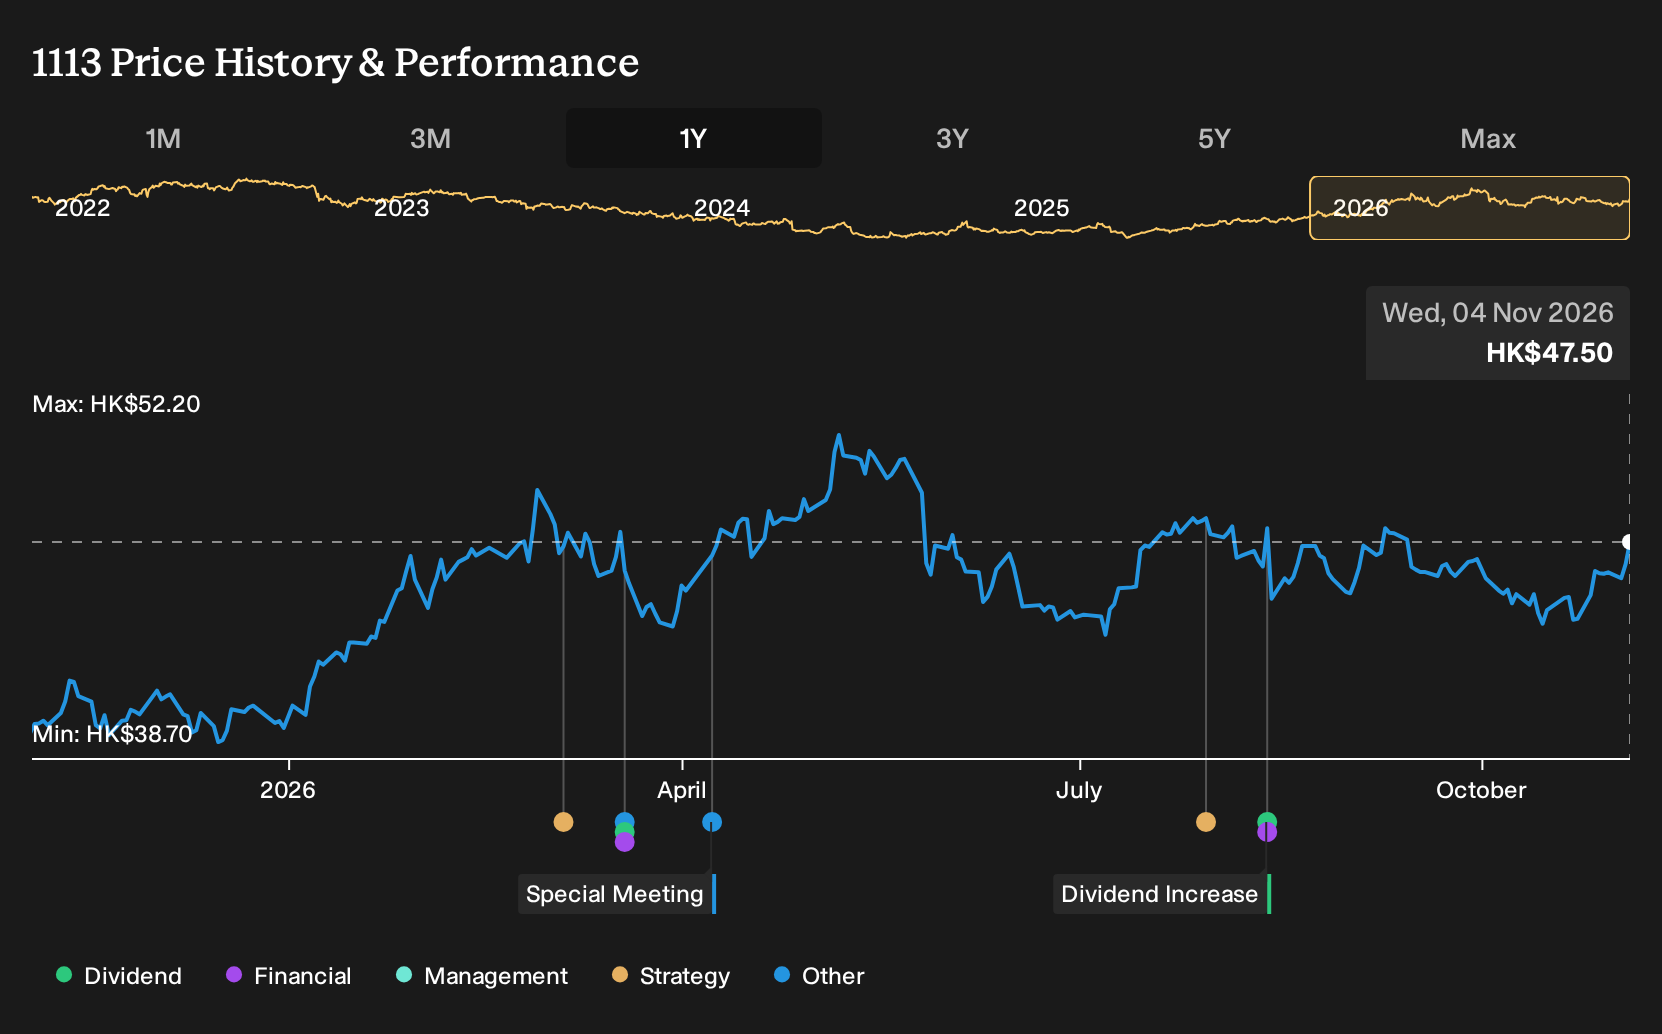
If you had bought CK Asset on 4 November 2025 and simply left it alone, the result might surprise you. Holding CK Asset over the past year would have returned 24.7%, including dividends. That outcome now sits alongside fresh headlines on record-priced luxury sales and new broker optimism around Hong Kong developers. If that decision were on the table again, how would you weigh rich recurring income against warnings about aging assets and softer local demand?
CK Asset has already moved. See which of 194 high quality undervalued stocks still trade below our estimates.
CK Asset: What Investors Were Really Arguing About
The shares cost HK$39.5 at the start of the period, and CK Asset sat between two very different but still reasonable stories about where value could come from next.
The bullish view pointed to a Fair Value of HK$48, a notional target based on assumptions that revenue could rise 21.7% a year with profit margins near 22.7% and a future P/E of 11.1x.
The cautious camp worked off a Fair Value of HK$28, built on only 1.3% assumed annual revenue growth, flat 23.2% profitability, and worries about weaker Hong Kong demand and office oversupply.
What The Results Changed For The CK Asset Debate
The cleanest test came from CK Asset’s H1 2026 numbers. Revenue reached HK$40,306m against HK$25,386m a year earlier, and net income rose to HK$8,683m from HK$6,302m, which backed the bullish focus on earnings power. Net margin slipped from 24.8% to 21.5%, so profitability quality did not fully match the more optimistic thesis.
The lesson is simple. When a property group is presented as being driven by recurring income strength, it is important to track whether net margin moves in the same direction as revenue and profit, rather than assuming scale alone will justify the story.
What CK Asset's Price Now Asks You To Believe
CK Asset now trades at HK$47.5, with this Narrative’s Fair Value sitting below that level based on its own set of assumptions rather than any settled truth about the stock.
The Narrative argues that recurring, inflation linked earnings and a large cash position are only attractive if reinvestment offsets low property margins. A buyer today is effectively assuming that recurring income stays resilient, so how does thin development profitability and slower capital deployment risk challenge that bet?
"The main thing that has to go right is that CK Asset Holdings continues to grow and protect its largely recurring, inflation linked income base while deploying its sizeable net cash into new long term assets without diluting returns. The current valuation implies that CK Asset Holdings is fairly valued, with the market treating disposal gains, strong liquidity, and resilient recurring income as sufficient to balance weaker development profitability and a cautious capital deployment stance."
One Narrative disagrees with today's price. → See where this Narrative says CK Asset should trade
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 38% below our estimate - targets long-life reserves and converts new discoveries into producing ounces.
- Company 2 - 45% below our estimate - applies data and AI tools to refine underwriting and claims decisions.
- Company 3 - 42% below our estimate - rolls out AI hiring and marketing platforms that automate client candidate matching.
Three companies from the same screener. Open the full list of 196 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com