


EN
Ferrari (BIT:RACE) Could Be 3% Below Fair Value On Raised Guidance
Ferrari (BIT:RACE) became the focus for investors after its third quarter report topped market expectations and management lifted both current year and 2026 revenue guidance, pointing to strong personalization demand and a deep order book.
The guidance upgrade and stronger third quarter figures arrived alongside a sharp move in the share price, with Ferrari posting a 1-day share price return of 4.47% and a 7-day gain of 7.33% as investors responded to the raised outlook and active share buyback. Over a longer stretch, momentum has been steadier rather than spectacular, with an 18.56% year to date share price return and a 5-year total shareholder return of 75.92%. This suggests the recent rally builds on a much longer run of value creation.
Scan the luxury auto space alongside Ferrari and see which peers are showing similar momentum and fundamentals with our hand picked 604 high quality undiscovered gems
After a guidance bump, a beat on earnings and a fresh leg higher in the share price, the next issue is simple: Does Ferrari still offer an appealing risk reward at €375, or has the recent surge done that work already?
Most Popular Narrative: 3% Undervalued
Ferrari closed at €375, while the most widely followed narrative pegs fair value around €388, implying a small discount that hinges on product mix, pricing power and the shift to hybrids and electric models.
Ferrari's imminent launch of its all-electric Elettrica and increased focus on hybrid models positions the company to not only capture demand from eco-conscious affluent buyers but also to comply with tightening global emissions regulations, which is likely to support long-term revenue growth and net margin resilience as sustainability and premiumization trends accelerate.
See why 59 investors see Ferrari as 3% undervalued.
Result: Fair Value of €388 (UNDERVALUED)
Still, the Ferrari narrative can come under pressure if electrification stays slow, or if luxury demand weakens and new model launches fail to keep order books as healthy.
Find out about the key risks to this Ferrari narrative.
Another View: Ferrari Through The P/E Lens
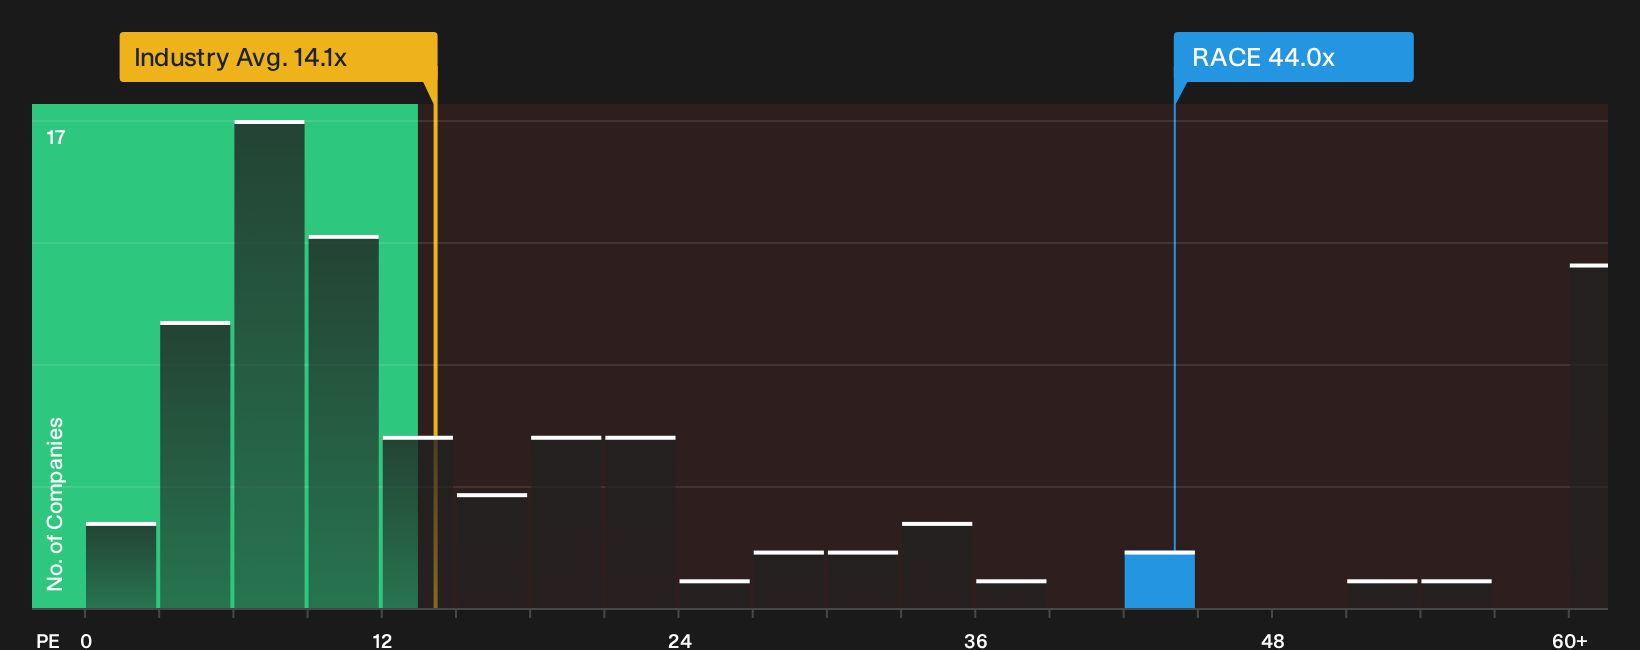
Fair value of €388 suggests Ferrari might have some upside left on the consensus model, but the current P/E of 44x tells a tougher story. The stock trades at more than 3x the global auto industry on 13.6x and over 2.5x the peer average on 16.5x, while the fair ratio sits at 22.3x.
This gap means you are paying a very rich premium for quality, brand and growth expectations. The question is simple: are those strengths sufficient for you to stay comfortable if the market ever moves that multiple closer to the fair ratio?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings about Ferrari's valuation story are clear, so move fast, test the assumptions against your own thresholds, and weigh both sides of the ledger with the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Ferrari?
Do not stop at Ferrari. Use the Simply Wall Street Screener to spot fresh opportunities that fit your style before other investors crowd in.
- Target potential upside in quality names that trade below their assessed worth by zeroing in on the 194 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies that aim to combine stability with generous payouts through the 216 dividend fortresses.
- Dial down portfolio risk by concentrating on resilient businesses with healthier finances using the 222 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com