


EN
Rush Street Interactive Stock In Focus After Strong Q3 Results And Maintained Guidance
- Rush Street Interactive reported Q3 2026 sales of US$385.85 million and net income of US$11.83 million, with basic and diluted EPS from continuing operations of US$0.10, and reconfirmed full year 2026 revenue guidance of US$1.56 billion to US$1.60 billion.
- The latest results show higher year on year sales and net income alongside maintained guidance, indicating that Rush Street Interactive is seeking to balance expansion in markets such as Latin America with cost discipline and profitability objectives.
- We will now examine how Rush Street Interactive's reaffirmed full year revenue guidance fits into the broader investment narrative for the business.
Rush Street Interactive Investment Narrative Recap
To own Rush Street Interactive, you need to be comfortable with an online betting operator that is leaning into product depth, especially casino, and growth in regulated markets across the Americas while still keeping an eye on profitability. The latest quarter delivered higher sales and net income year on year, and guidance was reiterated, so the core thesis around scale and operating discipline looks intact in the near term.
The key short term catalyst remains execution in existing jurisdictions, particularly Latin America and North American iCasino, without letting marketing or regulatory costs squeeze margins further. The biggest risk stays the same, namely concentrated exposure to changing tax and regulatory rules in places like Colombia, Mexico, Illinois, and New Jersey, and this earnings update does not materially change that risk profile.
The most relevant update for that story is the reaffirmed 2026 revenue outlook of US$1.56b to US$1.60b, tied to implied year on year growth of 38% to 41%. Keeping that range after Q3 suggests management still sees the current mix of markets, user trends, and marketing intensity as sufficient to hit the top line targets that were already on the table.
For you, the read through is about execution risk rather than a shift in direction. Progress on guidance depends on continued user engagement in the US, Canada, and Latin America and on keeping customer acquisition and regulatory costs from eroding earnings power. Any future changes to that full year outlook, in either direction, would likely be an important datapoint for how those catalysts and risks are evolving.
Rush Street Interactive's current earnings are US$37.7 million, with analysts modeling revenue growth of 11.9% per year and consensus earnings of US$123.0 million by 2029. This implies an earnings increase of about 3.3x from today and a forecast revenue build to US$2.1b in the same year.
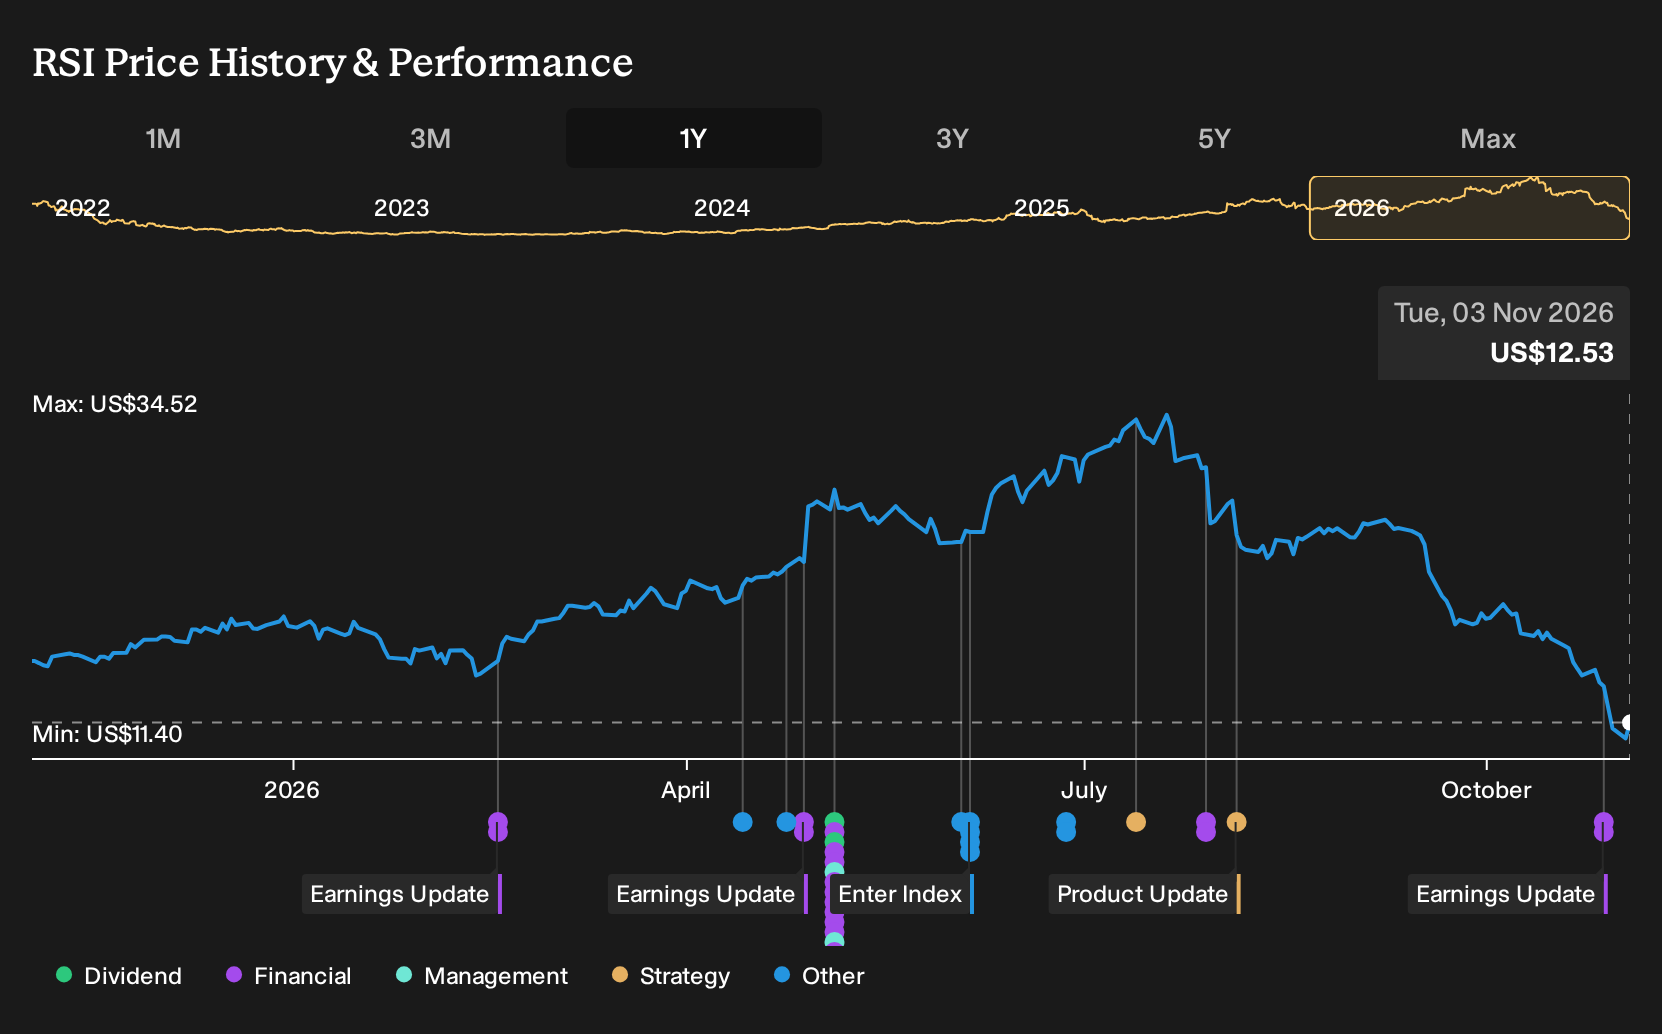
Uncover how Rush Street Interactive's fair value indicates an 85% potential upside to its current price that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Rush Street Interactive’s faster growth assumptions rather than tax risk. Before this Q3 update, the bullish camp was modeling revenue of about US$2.6b and earnings of roughly US$142.4 million by 2029, well above consensus. This guidance reaffirmation may prompt you to reassess which narrative feels closer to your own view.
Explore 2 other Rush Street Interactive fair value estimates, including one that suggests there could be as much as 181% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rush Street Interactive research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Rush Street Interactive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rush Street Interactive's overall financial health at a glance.
Looking for more investment ideas beyond Rush Street Interactive?
Once you have a view on Rush Street Interactive, it can help to line it up against other opportunities using the Simply Wall St Screener, so you see where it truly fits in your wider watchlist.
- If capital protection is a priority, you could start with companies that screen as more resilient by risk score through the 30 resilient stocks with low risk scores.
- For investors who care most about financial sturdiness, compare Rush Street Interactive with businesses highlighted in the list of solid balance sheet and fundamentals (23 results).
- If you want potential upside backed by fundamentals, scan the 19 high quality undiscovered gems that combine quality metrics with less crowd attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com