


EN
Is Zymeworks (ZYME) A Bargain On New ZW191 Data And The Roche Deal?
Zymeworks (ZYME) is in focus after new Phase 1 data for its FRa-targeting ADC ZW191 in heavily pretreated ovarian cancer, as well as a global collaboration with Roche around trispecific T cell engager ZW209.
Investors have reacted quickly to these updates, with Zymeworks’ share price at US$30.13 after a 1-month share price return of 19.8% and a 90-day gain of 28.21%. The 1-year total shareholder return of 65.91% and very large 3-year total shareholder return of about 4x suggest momentum has been building around the broader pipeline and partnership story rather than just this week’s headlines.
Spot other biotech stories with similar momentum by scanning our curated 19 high quality undiscovered gems, which pairs strong fundamentals with under-the-radar drug pipelines.The surge in Zymeworks after the Roche deal and ZW191 update still leaves the shares trading at a steep discount to both analyst targets and estimated fair value. Is that caution earned, or overly conservative given the current pipeline mix?
Most Popular Narrative: 27% Undervalued
On the most followed narrative, Zymeworks screens as undervalued, with a fair value estimate of $41.50 against the latest close at $30.13. This puts the current move after the Roche collaboration in a wider earnings and royalty story rather than a one week trading spike.
The key requirement is that Zymeworks successfully converts its partnered pipeline and platforms into durable, high-margin royalty streams and cash flows that can cover lower internal R&D spend and support ongoing non-dilutive financing and buybacks.
The current valuation implies the market is still discounting Zymeworks’ growing base of recurring royalty and profit-share revenue, the shift toward adjusted EBITDA generation, and the potential upside from large opportunities such as Ziihera royalties and ZW209 milestones. This view is consistent with a bullish stance that the stock is undervalued.
See why 9 investors see Zymeworks as 27% undervalued.
Result: Fair Value of $41.50 (UNDERVALUED)
Still, the Zymeworks story hinges on partners delivering on Ziihera and ZW209 milestones, as well as on royalty backed debt not squeezing future buybacks or acquisitions.
Find out about the key risks to this Zymeworks narrative.
Another View: Zymeworks Looks Expensive On P/B
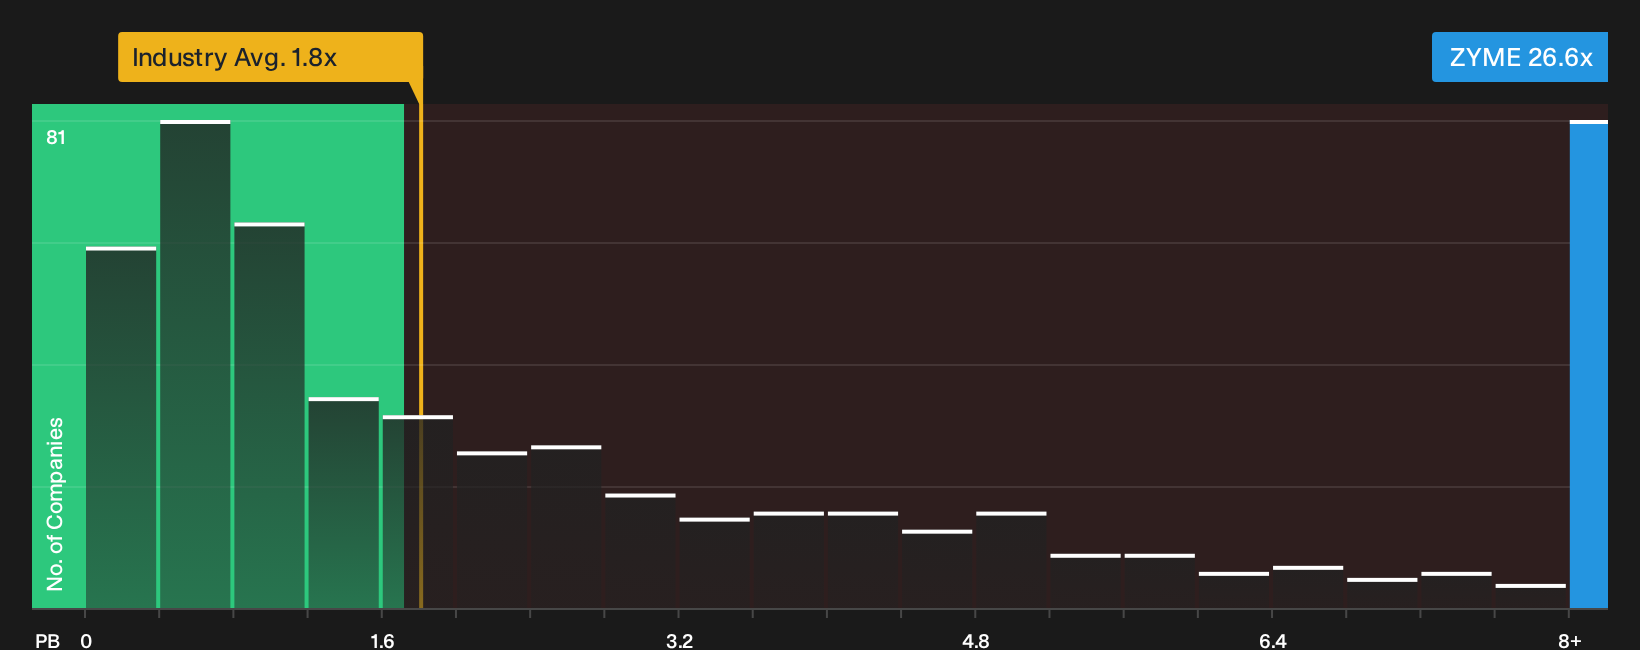
On a simple P/B yardstick, Zymeworks tells a very different story. The stock trades at 26.6x book value, compared with 5.4x for peers and 1.8x for the wider US biotechs group. That rich gap raises the question of how much balance sheet risk investors are really comfortable with.
For investors who want to see how the numbers line up against what the market might eventually be willing to pay, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Wondering whether the upbeat tone around Zymeworks matches your own read of the numbers and milestones? Act quickly, review the upside signals, and ground your view in the 2 key rewards.
Looking for more investment ideas beyond Zymeworks?
Do not stop with one stock. Broaden your watchlist using the Simply Wall Street Screener to spot fresh opportunities that fit the way you already think about risk and reward.
- Target potential mispricings by scanning a curated set of 35 high quality undervalued stocks that combine strong fundamentals with prices the market has not fully rewarded yet.
- Prioritise resilience by reviewing a 30 resilient stocks with low risk scores that focuses on businesses with sturdier balance sheets and calmer risk profiles than the wider market.
- Hunt for tomorrow's quiet outperformers by running through a 10 elite penny stocks with strong financials that filters for smaller companies with cleaner numbers instead of pure speculation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com