


EN
Is Novo Nordisk (NYSE:NVO) Reasonable After Its 58% Fall?
Novo Nordisk has seen its share price fall sharply in recent years, even as attention stays fixed on its diabetes and obesity franchise. With the stock down heavily over a 3 year window, the key issue for anyone looking at Novo Nordisk today is whether the current valuation lines up with what its earnings can support.
- The share price has fallen 58.0% over the past 3 years, which puts the focus squarely on whether the earnings profile still backs the market value placed on the business.
- Recent news around tougher GLP-1 competition and new products such as CagriSema can influence how investors think about future profitability, which feeds directly into how much they are willing to pay for Novo Nordisk's earnings stream today.
- The analysts covering Novo Nordisk have run their own numbers. See what analysts think Novo Nordisk's shares could be worth.
The stock's next move may depend on whether Novo Nordisk's current earnings, and realistic expectations for those earnings, are enough to justify the price investors are paying today.
If you are weighing Novo Nordisk after a 58.0% 3 year share price decline and tough GLP-1 competition, it can help to compare that earnings story with 35 high quality undervalued stocks.
Is Novo Nordisk a Bargain on Earnings?
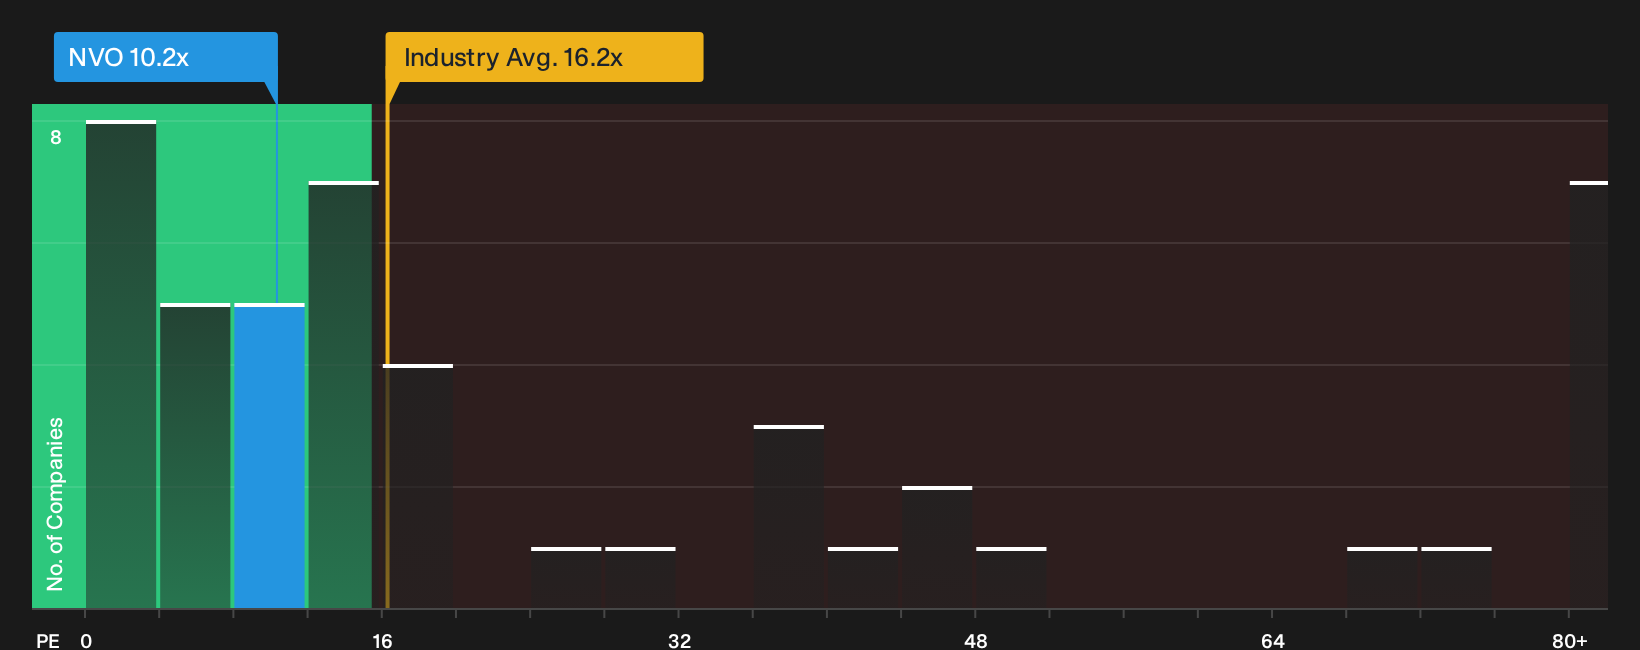
The P/E ratio is a useful lens for Novo Nordisk because earnings still anchor how investors think about its drug portfolio. On this measure, the stock trades on about 10.2x earnings, which is well below the pharmaceuticals industry average of roughly 16.2x and far under the broader peer group around 59.6x. That is a wide gap for a global healthcare player with a large diabetes and obesity platform.
The fair value framework, which blends factors like Novo Nordisk's margins, scale and risk profile, points to a higher P/E than where the shares change hands today. As a result, the current multiple screens as undervalued against that tailored benchmark. Because recent headlines focus on tougher GLP-1 competition and ambitious 2030 targets, the discount suggests investors may be pricing in a cautious outlook despite solid current earnings support. Explore the numbers behind Novo Nordisk's P/E valuation.
The Novo Nordisk Narrative: What Would Justify Today's Price?
Novo Nordisk's valuation story raises a simple question that Narratives try to answer directly. Narratives on Simply Wall St's Community page set out the specific paths for Novo Nordisk's future growth, margins and earnings that would need to hold for the current share price to look meaningfully cheap or expensive. This turns a single ratio or model output into a concrete set of expectations you can monitor over time.
One of the top community narratives on Novo Nordisk: 58% undervalued
"While sentiment is weak and valuation has compressed to roughly mid-teens forward earnings, Novo has added an important de-risking catalyst..."
Discover why this Narrative puts Novo Nordisk at 58% undervalued.
Novo Nordisk’s price is only one side of the decision
The people setting Novo Nordisk’s priorities and the way their rewards line up with your interests can matter as much as any P/E chart you see. See who runs Novo Nordisk and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com