


EN
Alphabet (GOOGL) Commits $15 Billion To Malaysia As AI Lawsuit Lands
- Alphabet (NasdaqGS:GOOGL) plans to invest US$15b to expand Google data centers and AI infrastructure in Malaysia.
- The Malaysian buildout includes new facilities to support AI services in Southeast Asia, along with sustainability and workforce programs.
- Shareholders have filed a lawsuit alleging Google trained AI models, including Lyria music tools, on copyrighted material without permission.
- Both the US$15b Malaysia data center push and the AI copyright lawsuit only capture part of what matters for Alphabet today. Take a look at 1 major warning sign we have identified for Alphabet.
This kind of AI infrastructure push involves a wider group of companies that are exposed to similar demand and regulatory questions. You can explore this through 53 AI infrastructure stocks.
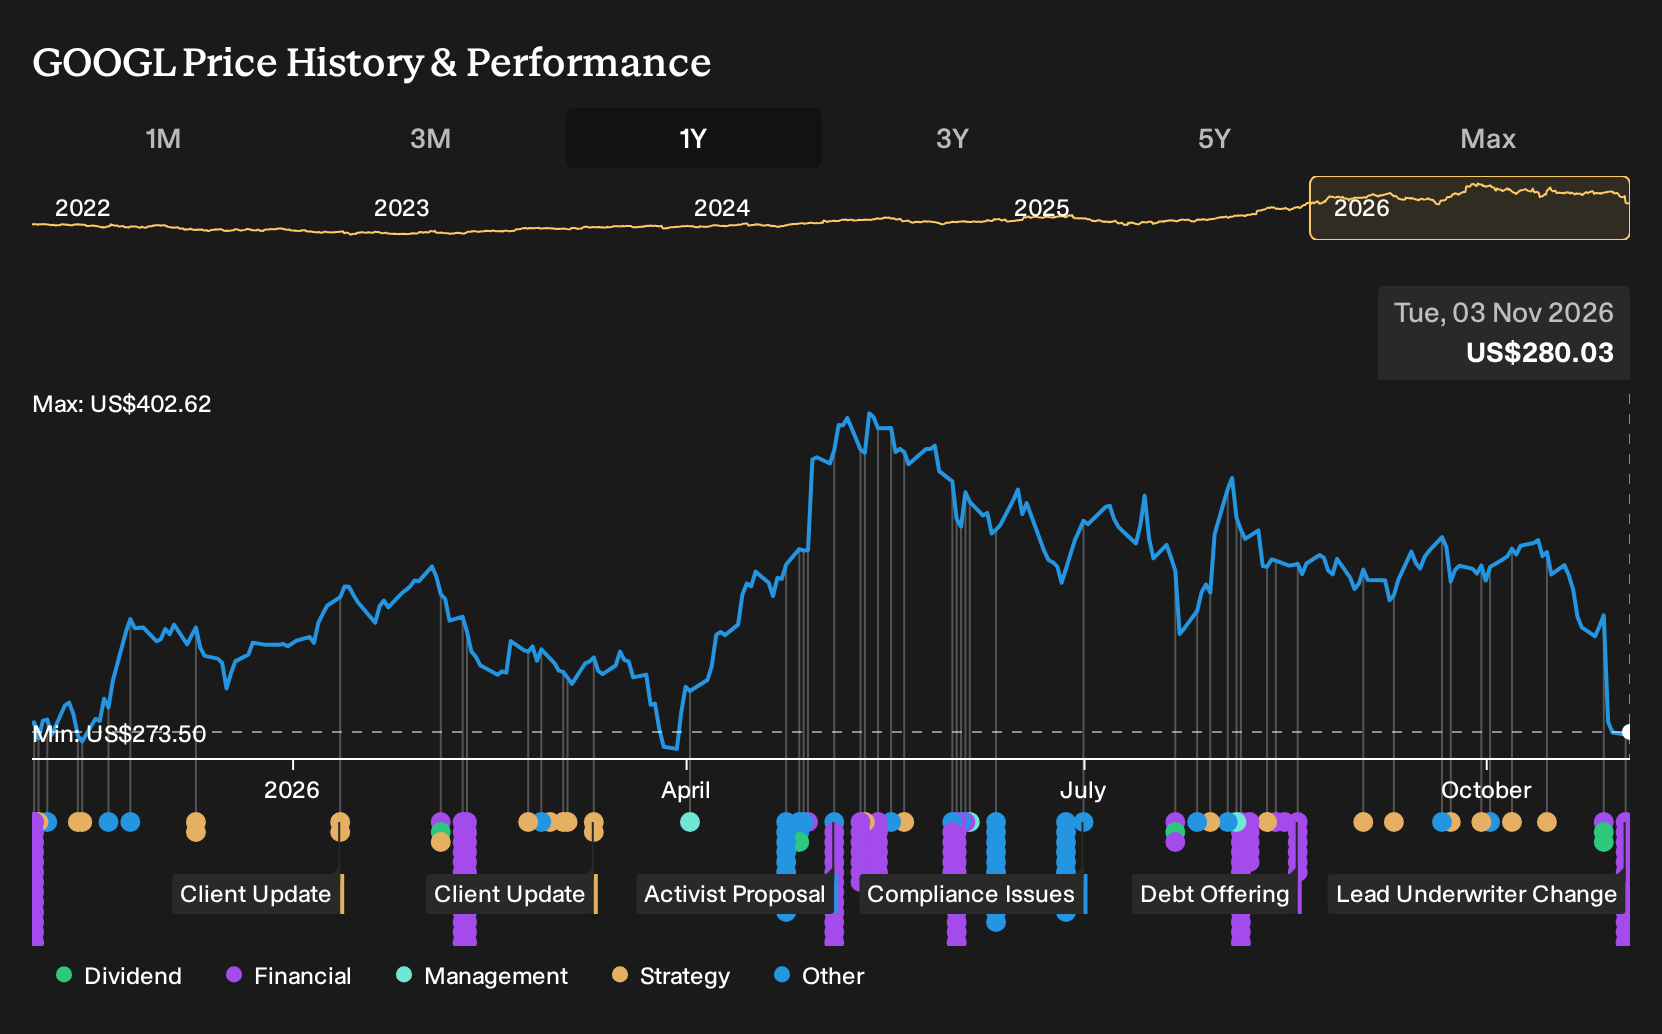
Alphabet runs global search, video, cloud and advertising platforms across regions that include the US and Asia-Pacific. As a result, large AI data center projects and legal disputes over training data both sit close to how its core services are built and delivered.
See which insiders are buying and selling Alphabet following this latest news.
Why would Alphabet fund a US$15b Malaysia buildout while tapping the euro bond market?
Heavy AI and data center spending requires long lived capital. Alphabet has just layered on more of that through multiple euro denominated bond issues, including notes maturing from 2028 out to 2045. The Malaysia plan points to Alphabet leaning on its strong balance sheet and access to debt markets so it can keep pushing AI capacity without relying only on near term cash generation.
Does this change the Alphabet Narrative the market is trading on?
The Narrative already hinges on Alphabet turning large AI infrastructure and custom TPU investment into durable demand for Gemini and Google Cloud, while managing pressure on free cash flow. A US$15b regional data center push and a copyright lawsuit both reinforce that same tension, between big AI spend on one side and mounting legal and regulatory risks on the other.
See how these catalysts shape Alphabet's path to a $408 fair value.
What will really tell investors if this AI story is working or not?
The clearest indication will be whether Google Cloud and AI related revenue, including the AI weighted backlog already referenced by analysts, keep scaling fast enough to cover rising depreciation and interest costs from bonds and data centers. Quarterly updates on Cloud margins and group free cash flow, especially through 2027 when capex is flagged to rise, will be the key checkpoints.
Add Alphabet to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com