


EN
Is Strong Q3 Earnings Altering The Investment Case For Steven Madden Stock (SHOO)?
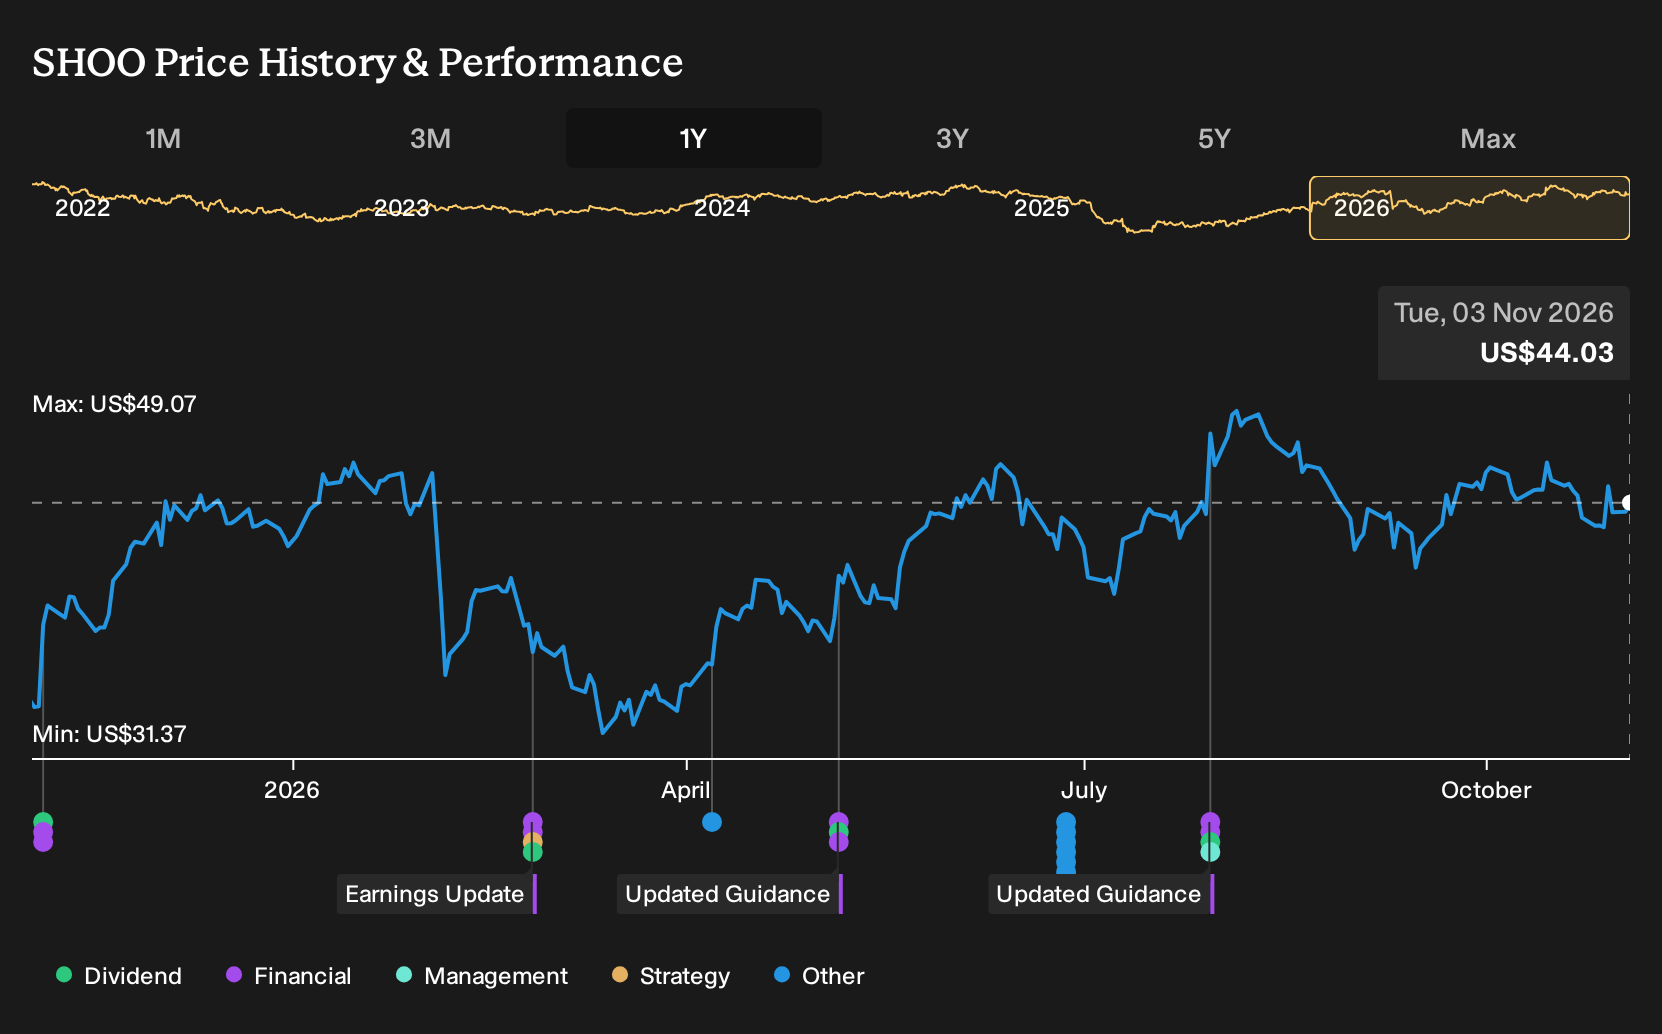
- UBS Securities recently highlighted expectations that Steven Madden would report Q3 earnings ahead of earlier projections, with momentum from the Steve Madden and Kurt Geiger brands seen as a key driver and a potential basis for higher full year guidance.
- The focus on stronger contributions from acquired and core labels suggests the footwear group is leaning harder into brand driven demand rather than relying on private label volumes.
- We will now look at how Steven Madden's investment narrative could shift if stronger Q3 earnings justify raising full year guidance.
Scan how brand driven footwear stories like Steven Madden compare with other consumer stocks that currently show strong earnings momentum using our hand picked 19 high quality undiscovered gems.
Steven Madden Investment Narrative Recap
To own Steven Madden, you need to believe the branded portfolio keeps pulling more weight than private label while tariffs and freight costs stay contained within what management already assumes. The near term swing factor is whether Steve Madden and Kurt Geiger can keep driving higher margin direct to consumer and international revenue without letting expenses run too hot.
The biggest risk still sits in cost pressure and the weak private label channel. If Q3 shows that brand strength only masks higher duties or sluggish value wholesale partners, the story around margin resilience looks less convincing, even if guidance nudges higher.
Recent commentary around strong double digit digital growth in direct to consumer for Steve Madden and Kurt Geiger feels central to this earnings setup. Global DTC revenue was reported at 30.6% higher in the latest quarter, and marketing spend moved to about 5.3% to 5.4% of revenue, which points to a heavier push behind owned channels.
For you as an investor, that DTC mix shift links directly to both the upside case and the risks. Higher margin online and store sales can offset tariff and freight pressure, yet they also require higher ongoing SG&A and clean execution on inventory, especially around Kurt Geiger, where integration costs and margin improvement targets are still in focus.
Steven Madden's current analyst scenario points to US$3.5b in revenue and US$276.8 million in earnings by 2029, based on a projected 8.2% yearly revenue growth rate and an earnings increase of about US$133.5 million from US$143.3 million today.
Uncover why Steven Madden's fair value indicates a 19% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
One alternate angle on Steven Madden focuses on the bullish catalyst of faster direct to consumer and branded growth. Those analysts were modelling about US$3.6b of revenue and US$287.9 million of earnings by 2029, which is more optimistic than the consensus. With the UBS Q3 beat call now in play, it is likely that those pre news narratives will be tested and possibly reshaped.
Explore another Steven Madden fair value estimate, including one that suggests potential upside of up to 110% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Steven Madden research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Steven Madden. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Steven Madden's overall financial health at a glance.
Looking For More Investment Ideas Beyond Steven Madden?
If the Steven Madden story has sharpened how you think about brands, earnings quality, and balance sheets, use that lens across a wider watchlist. The Simply Wall St Screener can help you filter the market into shortlists that actually match your risk tolerance and income goals rather than just presenting more tickers.
- For investors who want growth potential without ignoring quality, shortlist companies that combine strong fundamentals with attractive valuations through the 19 high quality undiscovered gems.
- If capital preservation comes first and you care about financial strength, start by filtering for companies with cleaner leverage and liquidity profiles through a list of solid balance sheet and fundamentals (23 results).
- Income focused investors who prefer a steadier stream of returns over headline excitement can focus on higher yielding candidates by screening for 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com