


EN
How Investors Are Reacting To Essential Utilities (WTRG) Earnings Beat
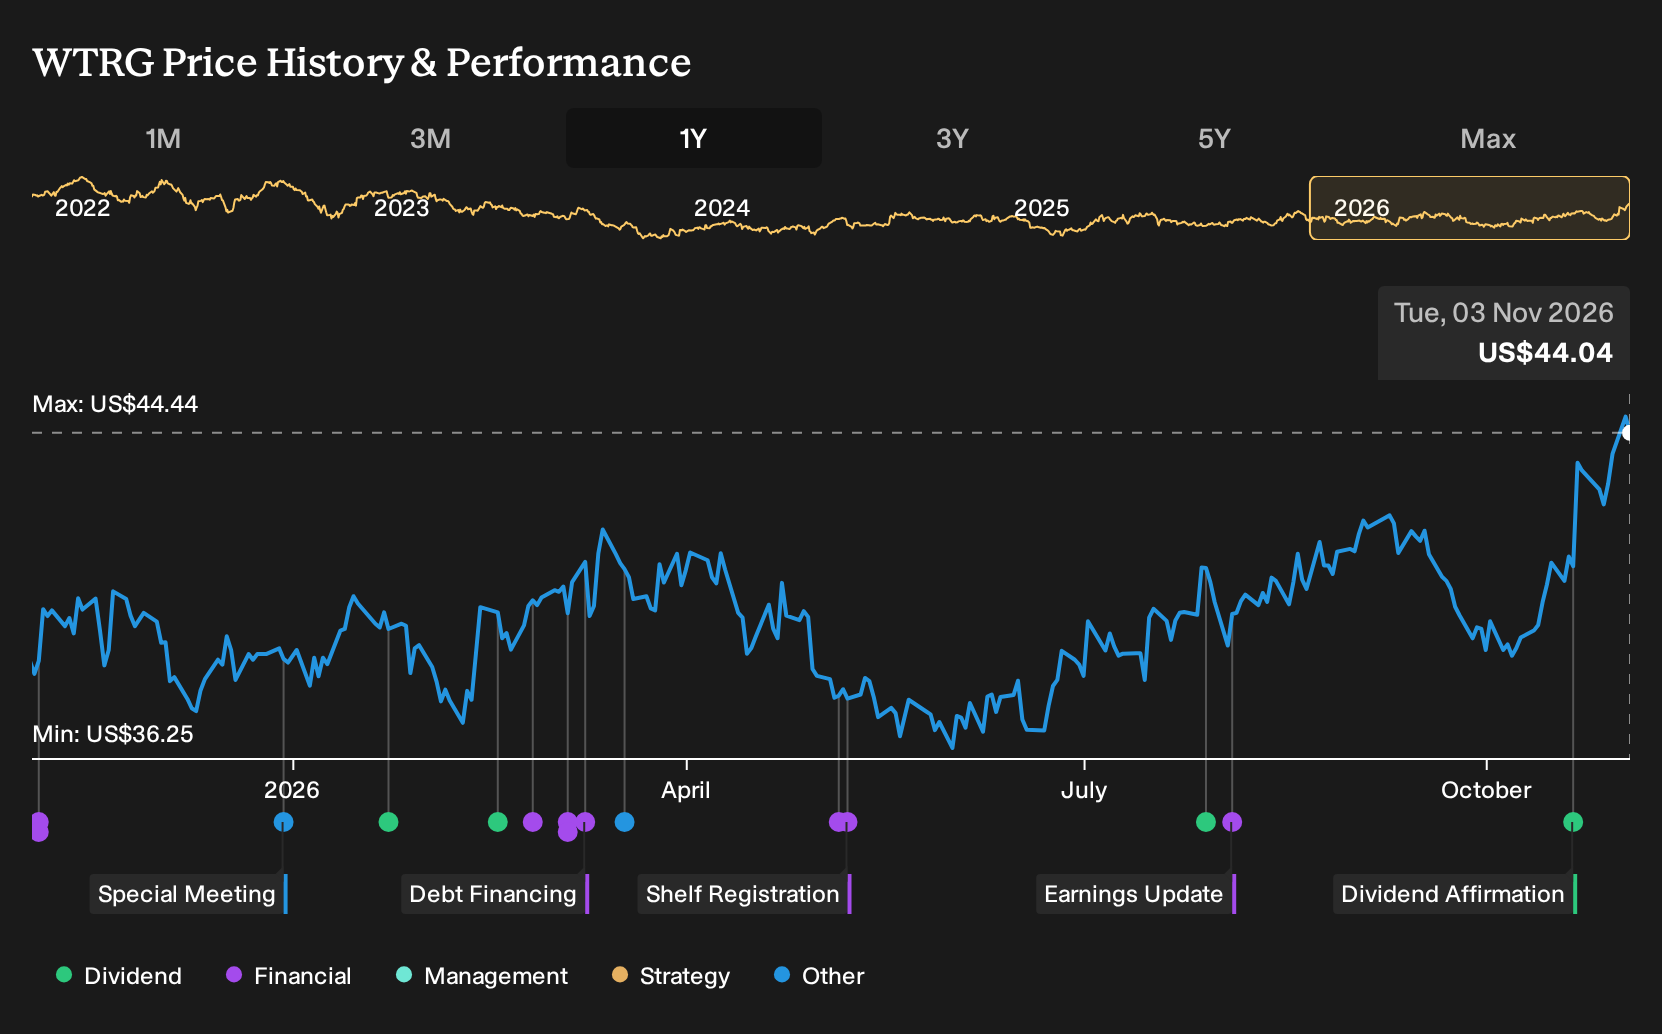
- Essential Utilities reported third quarter 2026 revenue of US$508.26 million and net income of US$103.84 million, with GAAP diluted earnings per share from continuing operations of US$0.36 and adjusted earnings per share of US$0.38. The company also declared a quarterly dividend of US$0.3606 per share in October.
- The utility showed higher quarterly earnings per share from continuing operations than a year earlier while nine month earnings per share trailed the prior period. This highlights how recent operating performance, infrastructure spending and merger related costs are pulling financial results in different directions at the same time.
- The next step is to review how Essential Utilities’ stronger than expected third quarter earnings could influence the existing merger led investment narrative.
Scan how Essential Utilities' earnings beat compares with other regulated players by reviewing our hand picked list of 30 resilient stocks with low risk scores in the current market.
Essential Utilities Investment Narrative Recap
Owning Essential Utilities means believing the regulated water and gas platform, plus acquisitions, can support steady earnings while it leans into very heavy infrastructure plans and the American Water merger. The latest quarter helps that story on the surface. Revenue of US$508.26 million and diluted EPS of US$0.36 from continuing operations show the core utility engine is still working.
The tension is in the nine month numbers. Net income of US$433.95 million compared with US$483.69 million a year earlier points to pressure from costs, financing and merger related spending. That matters because the short term catalyst is smooth progress on the American Water deal, while the key risk is funding US$1.7b of 2026 capex without stretching the balance sheet or diluting returns.
The most relevant update here is management’s confirmation that Essential Utilities remains on track to invest US$1.7b in infrastructure in 2026. That scale of spending underpins the whole rate base growth story investors are considering, from regulated water and wastewater systems to the natural gas network.
This commitment also sharpens the main risk. Heavy capex plus merger funding increases the importance of regulatory support for future rate cases, disciplined cost control and careful use of debt and equity. If execution on these projects and the American Water integration stays tight, that spending can remain a catalyst instead of turning into a drag on earnings quality.
Essential Utilities' current earnings are US$554.9 million, and analysts are assuming revenue will grow by 4.1% a year. Consensus forecasts point to US$2.9b of revenue and US$751.1 million of earnings by 2029, which implies an earnings increase of roughly US$196 million from today.
Uncover why Essential Utilities' fair value indicates a 6% potential downside to its current price, suggesting a premium that may not hold.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster in a tight US$41.2 to US$43.91 band, so even a small price move could flip Essential Utilities from perceived discount to premium. Those individual models do not yet reflect Q3 earnings, the American Water merger path or the heavy capex plan, so you may want to compare several fresh viewpoints before leaning on any single number.
Explore another Essential Utilities fair value estimate, including one that suggests there may be as much as 6% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Essential Utilities research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Essential Utilities. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Essential Utilities' overall financial health at a glance.
Looking for more investment ideas beyond Essential Utilities?
If the Essential Utilities story has you thinking about portfolio balance, use the Simply Wall St Screener to compare this utility with a broader set of opportunities and pressure test your thesis against what else is out there.
- For investors who want a margin of safety alongside quality fundamentals, scan our curated 35 high quality undervalued stocks that combine earnings power with disciplined balance sheets.
- If dependable income is a priority, focus on companies in the 4 dividend fortresses that pair higher yields with business models built around recurring cash flows.
- When capital preservation sits near the top of your checklist, start with the list of solid balance sheet and fundamentals (23 results) to quickly surface businesses with sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com