


EN
Invitation Homes Stock: Analyst Estimates & Ratings
Invitation Homes Inc. (INVH), headquartered in Dallas, Texas, is the nation's premier single-family home leasing and management company. Valued at $53.1 billion by market cap, the company owns and operates single-family rental homes, as well as offers acquisition underwriting and execution, upfront capital investment and renovation, ongoing leasing and maintenance operations, and dispositions services.
Shares of this single-family rental giant have underperformed the broader market over the past year. INVH has declined 6.2% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.5%. In 2026, INVH’s stock fell 4.3%, compared to the SPX’s 10.6% rise on a YTD basis.
Narrowing the focus, INVH’s underperformance is also apparent compared to the Residential REIT ETF (HAUS). The exchange-traded fund has gained about 2.3% over the past year. Moreover, the ETF’s 2.2% losses on a YTD basis outshine INVH’s dip over the same time frame.
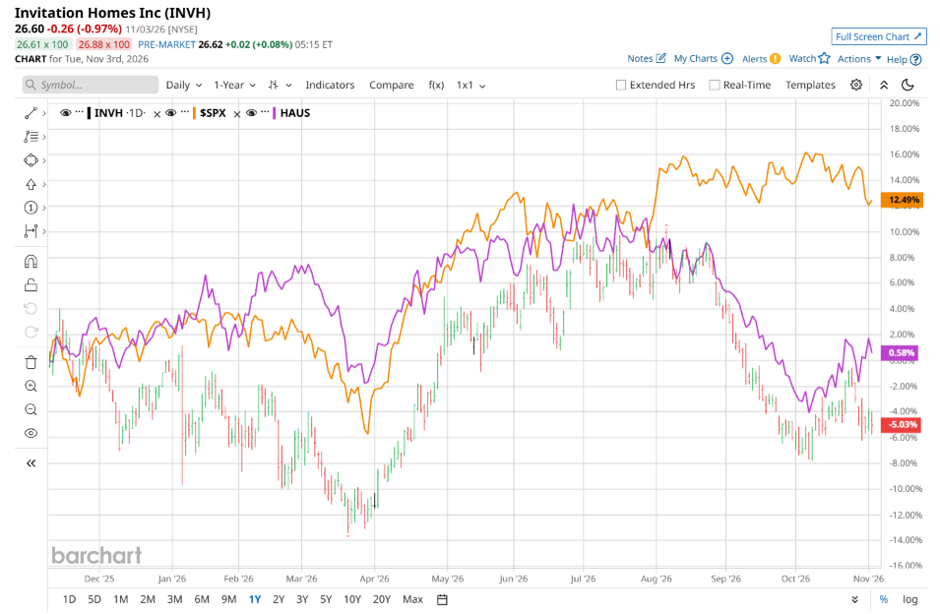
INVH has lagged the broader market primarily due to persistent macroeconomic headwinds, including elevated benchmark interest rates that have increased borrowing costs, compressed REIT valuations, and made fixed-income alternatives more attractive to investors. Furthermore, a combination of moderating single-family rental growth, slowing renewal pricing momentum as new housing supply catches up, and broader affordability hurdles has weighed on core FFO expansion and investor sentiment relative to the wider S&P 500 index.
On Oct. 28, INVH shares closed down by 1.6% after reporting its Q3 results. Its revenue stood at $731.3 million, up 6.3% year over year. The company’s adjusted FFO has remained flat from the year-ago quarter at $0.38 per share.
For the current fiscal year, ending in December, analysts expect INVH’s FFO to fall marginally to $1.90 on a diluted basis. The company’s FFO surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 25 analysts covering INVH stock, the consensus is a “Moderate Buy.” That’s based on 12 “Strong Buy” ratings, one “Moderate Buy,” and 12 “Holds.”
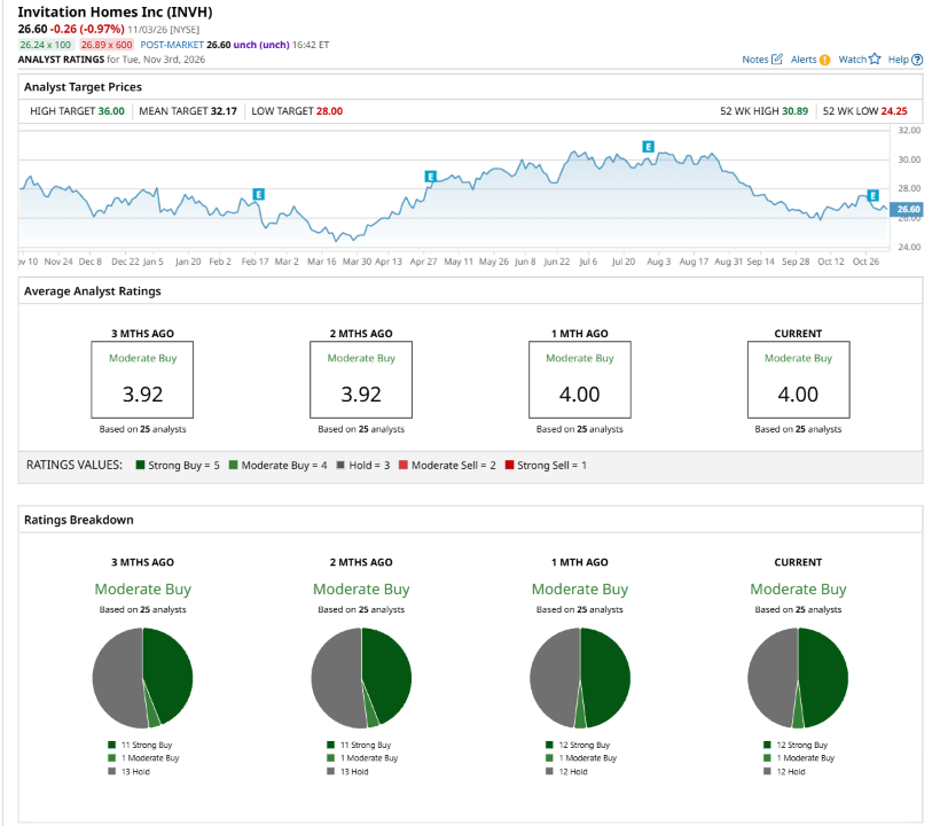
This configuration is more bullish than two months ago, with 11 analysts suggesting a “Strong Buy.”
On Nov. 2, Jade Rahmani from KBW maintained a “Hold” rating on INVH, with a price target of $31, implying a potential upside of 16.5% from current levels.
The mean price target of $32.17 represents a 20.9% premium to INVH’s current price levels. The Street-high price target of $36 suggests a notable upside potential of 35.3%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.