


EN
Did AI Platform Launch Just Shift Halliburton (HAL) Stock's Investment Narrative?
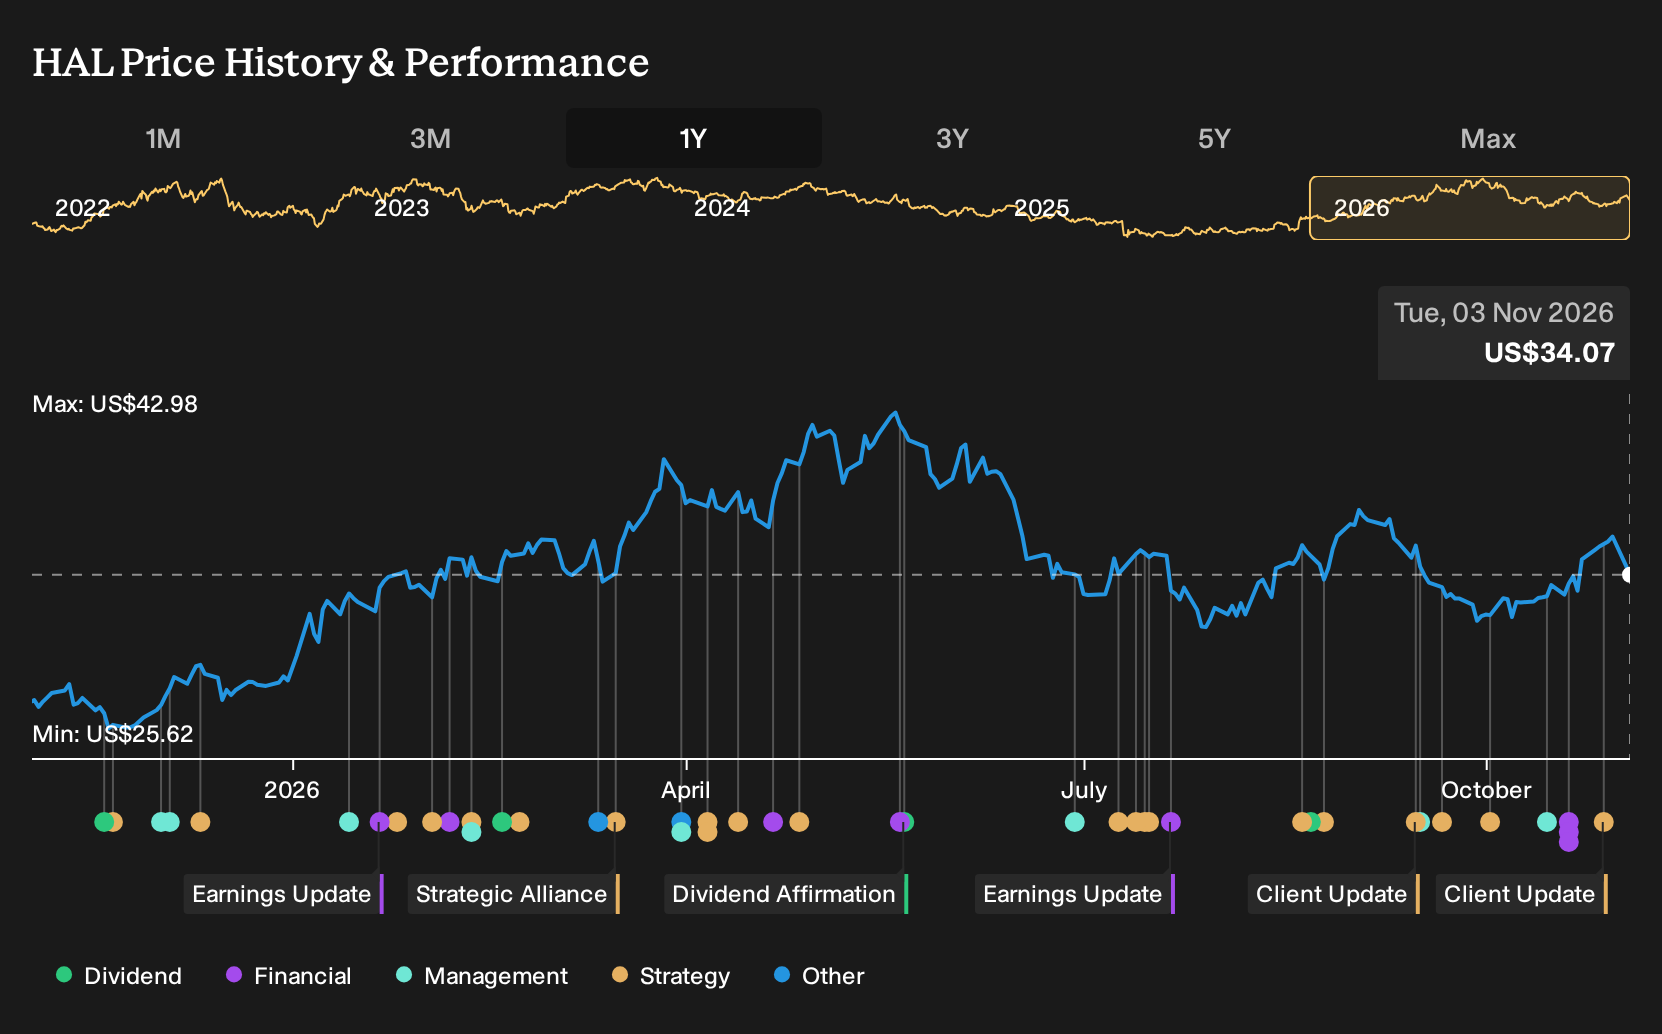
- Halliburton introduced its AI powered, cloud based Agile Asset Management platform and reported third quarter revenue of US$5.7b with continued share repurchases.
- The new tool aims to link subsurface, well, facilities and economic data so energy producers can shorten project evaluation and standardize capital decision making.
- We will now consider how Halliburton's investment narrative could be influenced by the rollout of the new Agile Asset Management platform.
Scan how Halliburton is leaning into AI and energy infrastructure, then size up similar potential breakouts in our hand picked list of 53 AI infrastructure stocks.
Halliburton Investment Narrative Recap
For Halliburton, the core belief is that upstream oil and gas spending remains healthy enough for its international contracts and higher tech services to stay busy. The near term swing factor is how effectively the business can keep lifting margins toward management’s stated 15% operating margin goal while still funding capex and its dividend.
The biggest risk is that decarbonization policies and faster renewable build out discourage long life oil and gas projects, which would eventually tighten Halliburton’s opportunity set. The new Agile Asset Management platform supports the technology and automation angle of the story, but on its own it does not materially change those broader demand risks.
The Agile Asset Management launch is the clearest recent event to watch against those catalysts. It plugs directly into Halliburton’s push to tie more international work to differentiated digital tools, alongside offerings such as ZEUS electric fracturing and LOGIX drilling automation that analysts already flag as important for mix and efficiency.
What matters now is execution. If customers adopt Agile Asset Management and embed it in multi year project planning, that can reinforce Halliburton’s role in complex field developments and support higher value contract awards. If uptake is slow, the company stays more dependent on traditional service work at a time when regulation and energy transition risks are still building.
Halliburton's narrative projects US$25.1b revenue and US$2.7b earnings by 2029. This is based on 3.9% yearly revenue growth and an earnings increase of about US$1.1b from US$1.6b today.
Uncover why Halliburton's fair value indicates a 28% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts Middle East disruption risk front and center for Halliburton. The most cautious analysts were working off only 1.2% annual revenue growth and US$23.2b sales by 2029 before this AI rollout. That is far more downbeat than consensus. Use the Agile Asset Management launch as a prompt to compare these sharply different narratives for yourself.
Explore 4 other Halliburton fair value estimates, including one that suggests it could be worth just $34.03.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Halliburton research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Halliburton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Halliburton's overall financial health at a glance.
Looking for more investment ideas beyond Halliburton?
Once you have a handle on Halliburton, it can help to widen the lens and line it up against other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- If you want potential mispricings with quality still in focus, scan our hand picked set of 35 high quality undervalued stocks that may suit a value driven approach.
- For investors who care most about resilience and capital preservation, consider filtering through a curated group of 30 resilient stocks with low risk scores that aim to keep risk scores in check.
- Income focused readers can round out research by reviewing a targeted pool of 4 dividend fortresses that combine high yields with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com