


EN
Space Exploration Technologies (SPCX) Moved Today, What Is Driving Attention Now?
Space Exploration Technologies (SPCX) has filed a shelf registration for up to US$3.42b of Class A common stock, covering 23,637,224 shares. This filing provides investors with updated information on the company’s potential future equity issuance plans.
Against that shelf filing backdrop, Space Exploration Technologies has been volatile, with a 1-day share price return of 3.62% and a 7-day share price return that declined 4.89%, as investors weigh merger talk with Tesla, fresh regulatory scrutiny, and ambitious AI and wireless expansion plans. The 30-day share price return is down 11.10%, while the 90-day move is a 30.52% gain, leaving year-to-date share price performance down 12.20% and indicating that short-term momentum has cooled following a strong run into recent newsflow.
Expand your watchlist beyond Space Exploration Technologies by reviewing hand-picked telecom and AI infrastructure players in our 53 AI infrastructure stocks that may feature in upcoming headlines.
Space Exploration Technologies now reflects a mix of powerful business headlines and fast changing mood music. Recent swings hint at both. The next step is to see how the current valuation lines up with that story.
Most Popular Narrative: 5% Overvalued
Space Exploration Technologies last closed at $141.31, while the most followed narrative on Simply Wall St anchors fair value at $135. That gap is small in dollar terms, yet it raises a bigger question about how realistic the long term revenue story really is at today’s price.
What makes SpaceX unusual is that investors are not buying a single business. They are buying exposure to several large themes at once: space, global communications, and AI. These are heavy infrastructure businesses that SpaceX has managed to build with an incredible momentum.
See why 73 investors see Space Exploration Technologies as 5% overvalued.
The narrative from QuanD argues that for Space Exploration Technologies to justify an implied US$3.75t future market value, revenue would need to reach about US$313b in 10 years with a 40% profit margin and a 30x P/E multiple. That thought experiment sets a very high bar compared with the latest reported top line of US$32,043m and a current net loss of US$3,431m.
Segment data in that narrative paints a picture of a three engine model, with Space, Connectivity and AI each hypothetically contributing around US$104b of revenue in a decade. Against the latest breakdown, Space at US$4,157m, Connectivity at US$16,024m and Super Intelligence at US$11,862m, the gap between today’s operations and that scenario is clear and helps explain why the narrative still tags the stock as slightly overvalued.
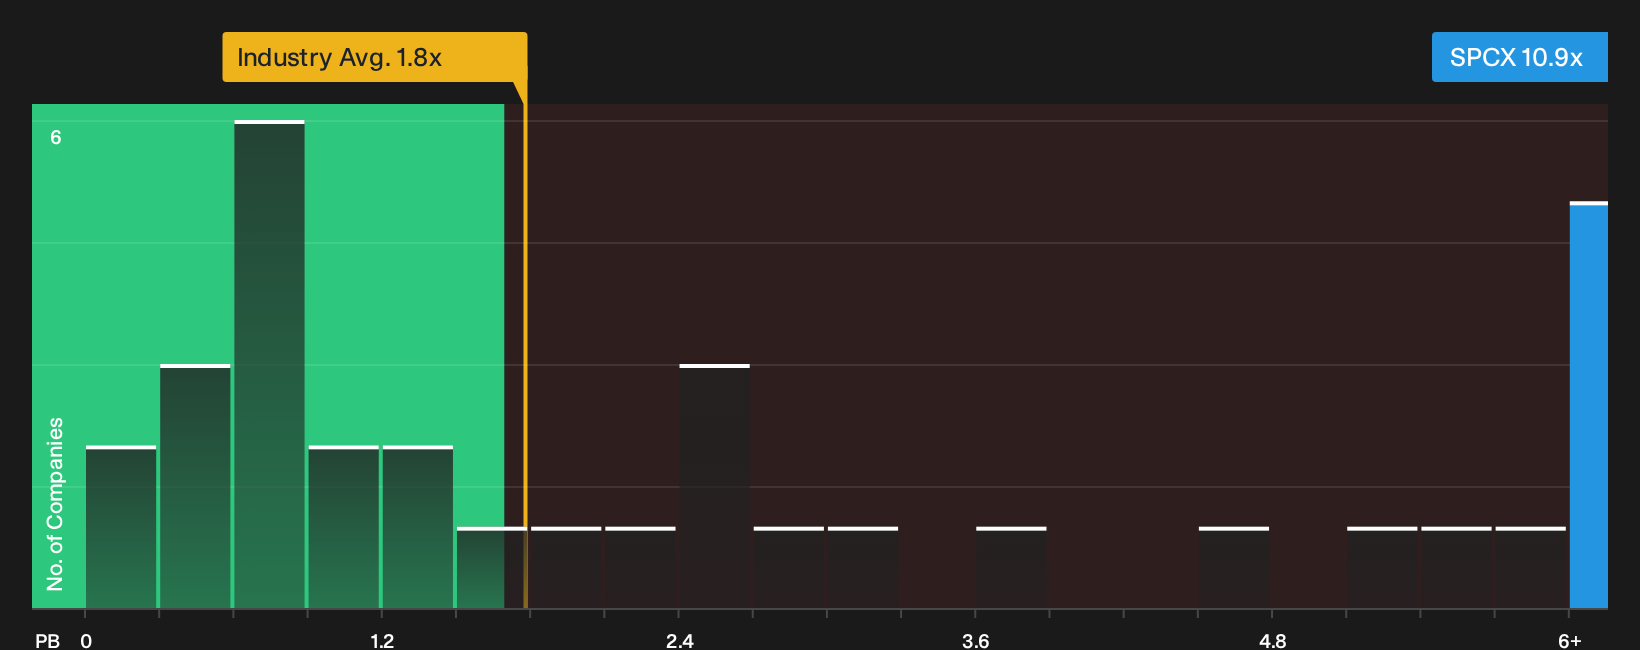
At the same time, Simply Wall St’s own checks flag a different angle. The shares are described as trading at a 32.1% discount to an internal fair value estimate, and also as good value on a P/B basis versus a selected peer average. However, the P/B of 10.9x screens as expensive against the wider US Telecom group on 1.8x. That split view underlines how much the long term outcome for Space Exploration Technologies depends on whether its high forecast revenue and earnings growth can be sustained.
The story in aggregate is that the most widely followed narrative sees fair value at $135 while some quantitative checks mark the stock as attractively priced relative to a model and certain peers. The 5% narrative premium to the last close is modest, yet it signals that a lot of future execution across rockets, broadband and AI may already be reflected in the current price.
Result: Fair Value of $135 (OVERVALUED)
Still, the story can crack if Space Exploration Technologies struggles to turn heavy AI infrastructure spending into profitable contracts, or if regulators tighten the leash on X and Starlink.
Find out about the key risks to this Space Exploration Technologies narrative.
Another View: What Multiples Say About Space Exploration Technologies
There is a different read once price is compared with book value. Space Exploration Technologies trades on a P/B of 10.9x. That is below a selected peer group on 12.1x, yet far above the wider US Telecom sector at 1.8x, which points to meaningful valuation risk if expectations reset closer to the industry.
Investors weighing those gaps may want to see what the numbers imply for today’s price versus balance sheet strength, and how that could shift if sentiment cools or heats up, in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Space Exploration Technologies can feel noisy, so review the underlying numbers and sentiment data now and decide where you stand on its 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Space Exploration Technologies?
If you only stop at Space Exploration Technologies, you risk missing other companies with strong balance sheets, income potential, and rerating upside that could better fit your goals.
- Target stability first and scan a list of solid balance sheet and fundamentals (23 results) to focus on businesses where debt and cash levels look more resilient on paper.
- Hunt for mispriced opportunities by reviewing a 35 high quality undervalued stocks that highlights companies combining quality fundamentals with what the model views as discounted share prices.
- Prioritize income and shortlist payouts using a 4 dividend fortresses that filters for higher yielding stocks that still clear basic financial health checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com