


EN
MasTec (MTZ) Jumped, But What Is Really Driving Attention Now?
MasTec (MTZ) is back in focus after third quarter 2026 results showed higher sales alongside a small dip in quarterly profit, paired with fresh full year guidance that outlines revenue and earnings expectations.
MasTec’s earnings update and fresh full year guidance arrived alongside a sharp short term rebound in the shares, with a 7 day share price return of 12.24% after a weak 90 day stretch where the stock fell 25.74%. The 3 year total shareholder return of 300.69% and 5 year total shareholder return of 105.26% underline how a volatile recent slide sits against a still very strong longer run for investors.
Scan how MasTec’s grid and energy work compares with peers by reviewing a curated group of infrastructure contractors, screened as 41 power grid technology and infrastructure stocks, for potential opportunities in a similar theme.
After MasTec’s sharp bounce and rich multi year run, the real fork in the road is timing. Does it make more sense to commit capital here, or to wait for a cleaner entry once the valuation picture is clearer?
Most Popular MasTec Narrative: 45% Undervalued
Against MasTec’s last close of $198.10, the most followed narrative framework points to a fair value of about $360, which frames the recent rebound as only a partial move toward that implied upside.
Rapid acceleration in utility grid modernization, data center build outs and renewable energy investment continues to support MasTec’s record backlog of about US$21.4b and raised 2026 guidance. This points to further upside potential in revenue and earnings as these projects convert.
See why 31 investors see MasTec as 45% undervalued.
Result: Fair Value of $360 (UNDERVALUED)
Still, the MasTec narrative can crack if communications headwinds persist or if any future earnings miss again triggers a sharp reset in market confidence.
Find out about the key risks to this MasTec narrative.
Another View On MasTec’s Valuation
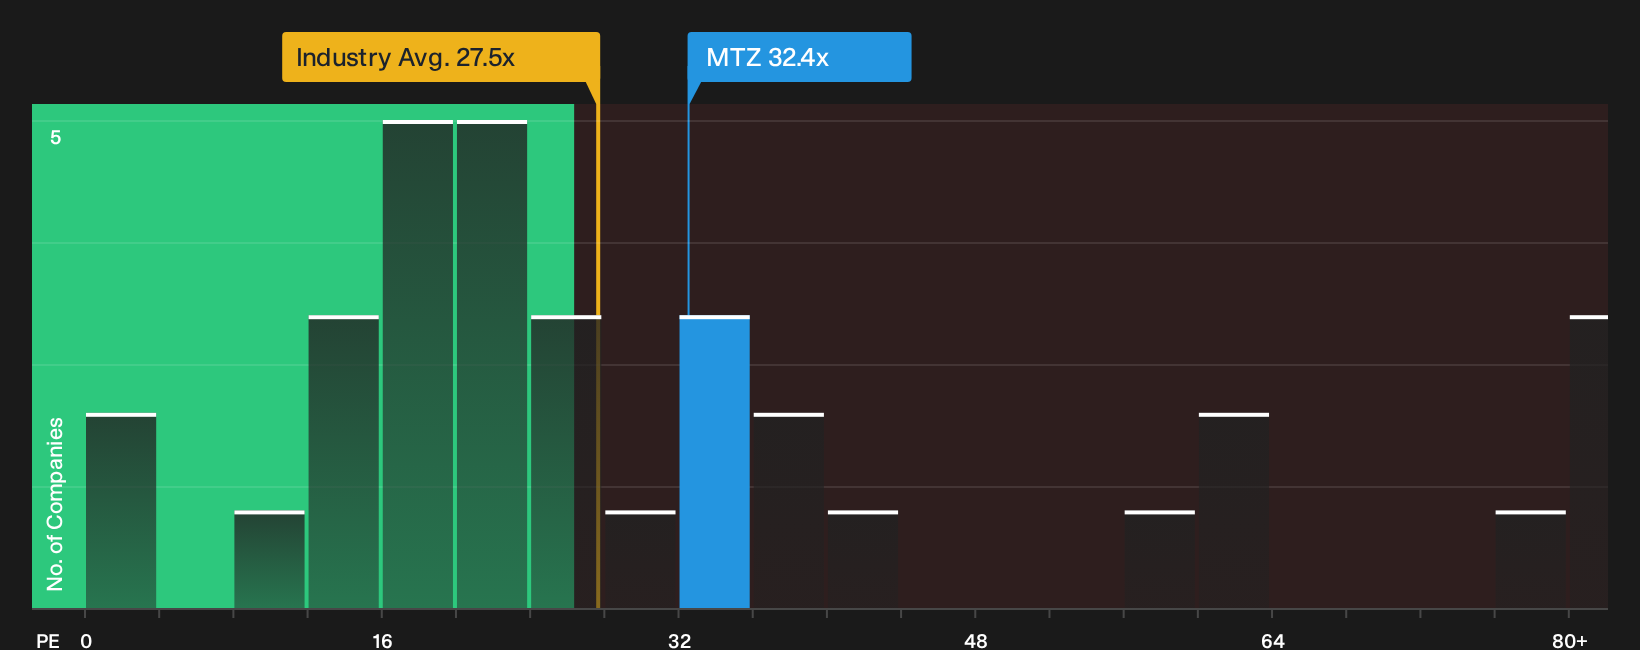
Multiples tell a different story for MasTec. The stock trades on a P/E of 32.4x, which is richer than both the US Construction sector at 27.5x and a 20.2x peer average, yet still below a fair ratio of 37.8x that the market could move toward. Is that premium a warning sign or a potential opportunity if earnings keep tracking forecasts?
To pressure test the earnings based view against that richer P/E profile, take a closer look at how the current price compares with the detailed valuation work in our breakdown: See what the numbers say about this price — find out in our valuation breakdown.
For a visual sense of how MasTec’s earnings multiple stacks up against the broader industry, see the latest relative valuation snapshot here:
Next Steps
Mixed messages on MasTec’s value case so far. Move quickly, pull up the numbers yourself, and then decide if the balance of upside and risk feels worth it to you by weighing the 3 key rewards and 1 important warning sign.
Looking for more MasTec style investment ideas?
If MasTec has you thinking harder about where to put fresh capital, do not stop here. The right watchlist today can shape tomorrow’s opportunities.
- Target potential mispricing by reviewing the 35 high quality undervalued stocks that pair solid fundamentals with prices the market may be underestimating.
- Strengthen your income stream by scanning the 4 dividend fortresses that combine higher yields with a focus on resilience.
- Reduce potential downside shocks by filtering for the 30 resilient stocks with low risk scores that score well on financial health and stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com