


EN
Oil Prices Are Back So Which Upstream Energy Stocks Deserve A Closer Look
Oil prices are back in the spotlight, with Brent above $100 and WTI near $96 as Middle East conflict, U.S. Iran talks and weaker flows through the Strait of Hormuz keep a risk premium in crude. That mix of higher energy prices and geopolitical uncertainty can quickly reshape which producers attract capital and which get avoided. This article walks through 3 stocks exposed to these headlines and how investors might think about them now.
The three stocks that follow are just a starting sample. The full screen surfaced 24 more integrated and upstream oil and gas producers with equally compelling narratives that are not covered below. To go straight to the broader opportunity set, head into the Integrated and Upstream Oil & Gas Producers screener to identify, filter, and analyze the highest conviction plays that fit your own risk and return preferences.
Obsidian Energy (TSX:OBE)
Overview: Obsidian Energy is a Calgary based producer that focuses on exploring, developing, and pumping oil and natural gas assets across Western Canada.
Operations: Obsidian Energy generates about CA$544 million from oil and gas exploration and production, with all reported revenue coming from operations in Canada.
Market Cap: CA$969 million
Obsidian Energy gives you pure upstream exposure to Western Canadian oil, so revenues are closely tied to crude pricing and volumes. The stock trades on earnings that carry a relatively high P/E, backed by recent profitability and forecasts of faster growth than the wider Canadian market. That mix of leverage to higher prices and a richer valuation means there is significant sensitivity if a single key assumption does not hold.
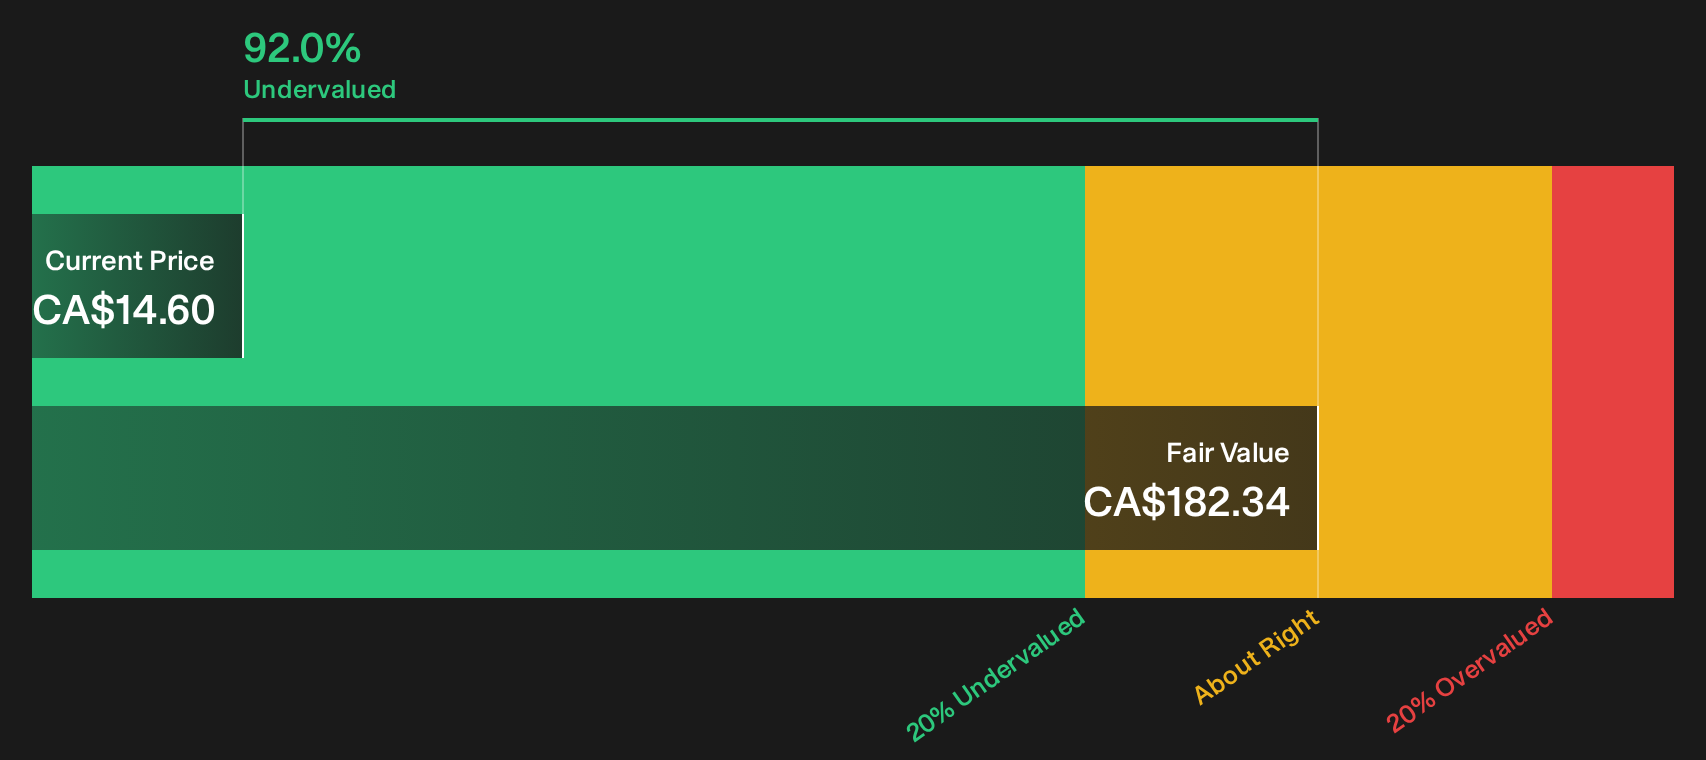
When a single assumption can significantly affect the thesis, it helps to see how the market is pricing that risk inside the DCF valuation analysis for Obsidian Energy before deciding where Obsidian Energy really sits.
Infinity Natural Resources (INR)
Overview: Infinity Natural Resources acquires, explores, and develops oil, natural gas, and NGL acreage across the Utica and Marcellus shale plays in the United States.
Operations: Infinity Natural Resources generates about US$523 million from acquiring, exploring, developing, and producing crude oil and natural gas exclusively in the United States.
Market Cap: US$886 million
Infinity Natural Resources is one of the clearest plays in this screen on upstream exposure, with oil, gas, and NGL volumes that are closely tied to the very price moves currently driven by Middle East supply worries and tighter flows through key shipping routes.
"Although the underutilized midstream network with roughly 1 Bcf per day of capacity offers room for volume growth without large new infrastructure builds, current utilization near 35% and small third party revenue contributions mean the system could remain a cost center rather than a profit driver. This would limit the uplift to operating income and EBITDA that some investors may expect."
The real swing factor for Infinity Natural Resources now is how one cost pressure shapes the gap between higher commodity prices and future margins.
That cost squeeze is only half the story, and the full narrative for Infinity Natural Resources shows how pricing, capital plans, and balance sheet choices could still accelerate Infinity Natural Resources.

Logan Energy (TSXV:LGN)
Overview: Logan Energy focuses on upstream exploration and production in Alberta and British Columbia, giving investors direct leverage to higher oil prices.
Operations: Logan Energy generates about CA$212 million from oil and gas exploration and production in Canada, offering concentrated upstream revenue exposure.
Market Cap: CA$1.0 billion
Logan Energy offers pure upstream exposure at a time when oil prices are rebounding and revenue growth forecasts are strong. The stock trades on rapid earnings expansion and a P/E above many peers. As a result, the appeal of this oil price play rests heavily on whether a single pressure point ultimately widens or compresses future margins.
That pressure point deserves a closer look through the 3 key rewards and 2 important warning signs (1 is major!) to see what might amplify or cap Logan Energy’s upside if forecasts shift.

Seeking Alternatives Beyond Oil Plays
Fresh opportunities move fast. Breakout momentum, flying liquidity and under the radar for now information can get caught and stale quickly. Scan these ideas before the crowd and act now.
- Target dependable income by lining up high-yield candidates in the 3 dividend fortresses, then decide which cash generators still look sustainable while it matters.
- Spot early tech momentum by tracking companies inside the 53 AI infrastructure stocks, before AI build out demand is fully reflected in prices and entry points start dropping.
- Hunt for overlooked quality using the curated 8 high quality undiscovered gems that highlights under the radar for now businesses before market attention drives a fresh wave of interest.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com