


EN
Revolve Group (RVLV) Stock Dropped, What Is Behind The Latest Attention?
Revolve Group (RVLV) has just released new third quarter results, reporting sales of US$355.96 million and net income of US$14.47 million, providing investors with updated financial data to review.
Despite a strong third quarter revenue update and new store openings such as the Aventura Mall location in Florida, Revolve Group’s 1-day share price return fell 2.14% and its 7-day share price return declined 4.82%. However, the 1-year total shareholder return is 7.76% and the 3-year total shareholder return is 54.67%, indicating longer term gains even as recent momentum has faded relative to earlier years.
Spot fresh ideas beyond Revolve Group by scanning a hand picked 19 high quality undiscovered gems that echo similar growth, profitability and platform driven retail stories.Revolve Group’s share price has slipped despite a 20% jump in quarterly sales, while analyst targets cluster well above the current US$21.53 level. Does fair value lean closer to that target band or to today’s quote?
Most Popular Narrative: 30% Undervalued
Revolve Group’s most followed storyline puts fair value around $30.85 using an 8.21% discount rate, compared with the latest close at $21.53. That gap sets up a valuation debate that leans heavily on growth spending and expansion paying off over time.
A key factor is that higher marketing and general and administrative spending lead to sustained double digit net sales growth, stronger gross margins, and lasting demand for newer categories and collaborations.
Building out physical retail locations in Aspen, Los Angeles and soon Miami, together with offline media such as the upcoming REVOLVE Magazine and capsule collaborations like the 32 piece Porsche Collection, is expected to deepen brand influence, support customer acquisition and contribute to higher revenue and operating leverage over time.
See why 10 investors see Revolve Group as 30% undervalued.
Result: Fair Value of $30.85 (UNDERVALUED)
Still, this Revolve Group thesis relies on heavier marketing and higher general and administrative spending eventually paying off, and those outlays could simply compress earnings instead.
Find out about the key risks to this Revolve Group narrative.
Another View: What Multiples Say About Revolve Group
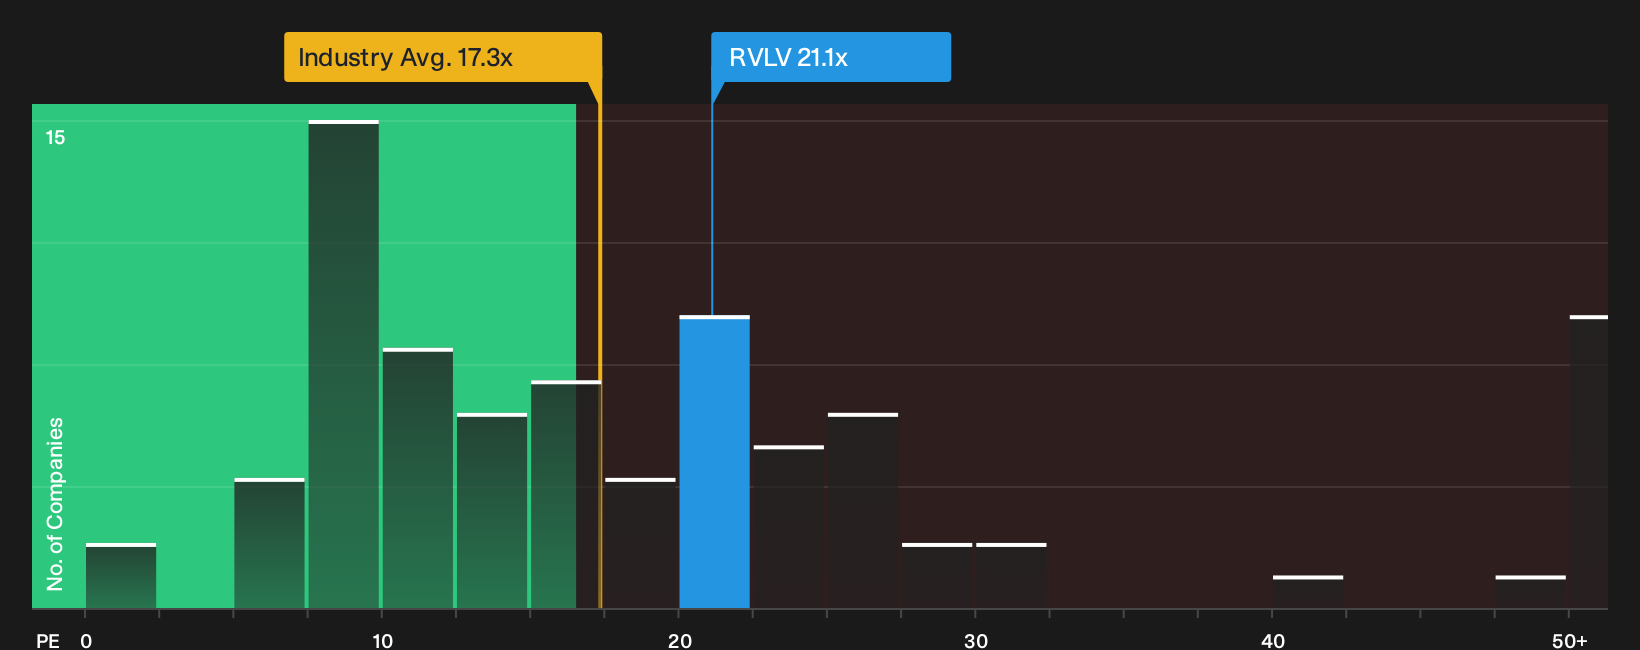
Revolve Group might look undervalued on a $30.85 fair value narrative, yet the current P/E of 21.1x is higher than the US Specialty Retail industry at 18.1x and above an estimated fair ratio of 14.1x. That gap points to valuation risk if sentiment cools before growth assumptions play out.
For a closer look at how this pricing gap lines up against sector and fair ratio signals, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Revolve Group often create more questions than answers, so move fast, review the full picture, and weigh both sides with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Revolve Group?
If Revolve Group has you thinking about what else might fit your portfolio, use these focused stock shortlists to spot opportunities you might otherwise miss.
- Target more defensive holdings by scanning a 30 resilient stocks with low risk scores that aims to keep downside risk in check while still giving you a broad spread of businesses.
- Hunt for strong fundamentals through a list of solid balance sheet and fundamentals (23 results) that filters for companies with healthier finances and room to handle tougher conditions.
- Pursue growth potential off the beaten path with a 19 high quality undiscovered gems designed to surface quality stocks that are not yet heavily followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com