


EN
QinetiQ Group (LSE:QQ.) Just Gave Investors Something To Think About
Why QinetiQ Group’s extended contract matters now
QinetiQ Group (LSE:QQ.) has extended a key long-term partnering agreement to 2033 worth £1.5b, alongside record £3.6b order intake and a £4.8b backlog that covers 67% of next year's revenue.
Recent trading reflects that contract momentum. QinetiQ Group’s share price return is up 15.44% over the past month and 23.65% year to date, while the 1-year total shareholder return of 18.27% follows very strong 3 and 5 year gains, suggesting momentum is still building rather than fading.
Scan defence and security peers that show similar contract-backed momentum with our hand-picked 5 resilient stocks with low risk scores to see how QinetiQ Group compares on resilience and consistency.
QinetiQ Group now trades only slightly below analyst targets, yet still shows a much larger modelled discount to fair value. Is that gap a genuine opportunity or a sign the market doubts the recent surge?
Most Popular Narrative: 42% Overvalued
Against the last close of £5.50, the most followed narrative on QinetiQ Group argues for a fair value of £3.88, which implies the current contract wins and share price strength are more than fully reflected. That narrative leans heavily on the dividend policy and earnings profile rather than short term order momentum.
Dividend now set at 35-40% of underlying EPS, no longer explicitly progressive, covered about 3x by free cash flow, low debt.
Thesis: 7-9% dividend growth from earnings growth plus buybacks.
See why 1 investors see QinetiQ Group as 42% overvalued.
The narrative, according to DKDGI, applies an 8.63% discount rate and a dividend discount model that focuses on a current 11.0p payout and a specific growth path for those distributions. That produces the £3.88 estimate, which sits well below both the market price and the modelled intrinsic value from cash flow forecasts, so readers are looking at a wide spread between different valuation frameworks.
Result: Fair Value of £3.88 (OVERVALUED)
Still, this thesis leans heavily on UK defence contracts and a payout policy that could force a lower dividend if earnings slip or the US review becomes costly.
Find out about the key risks to this QinetiQ Group narrative.
Another view on QinetiQ Group’s valuation
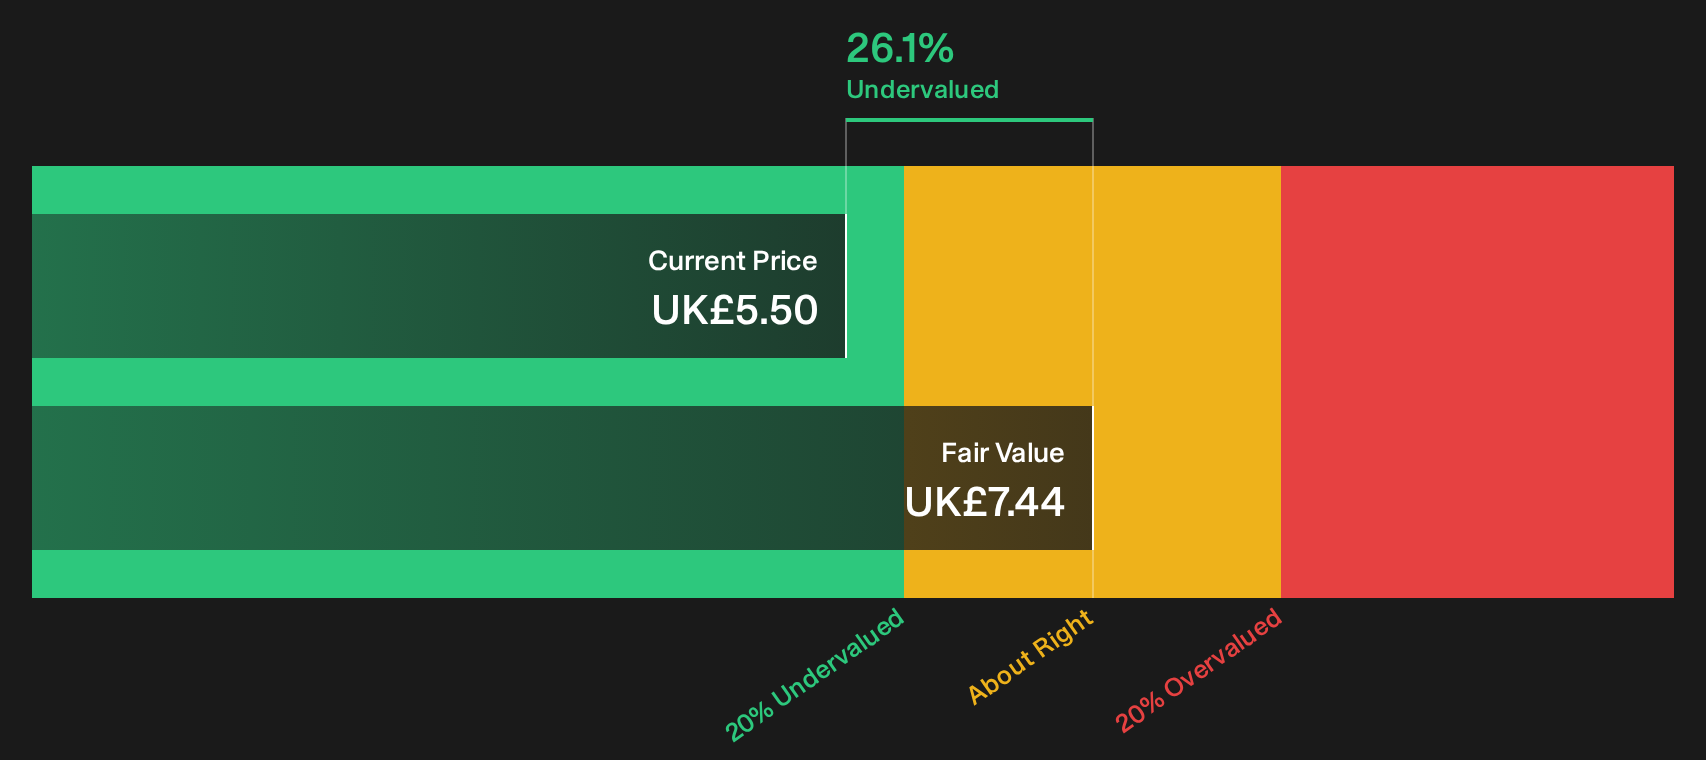
The SWS DCF model tells a very different story to DKDGI’s dividend-focused view. Compared with the £5.50 share price, the model points to a £7.44 future cash flow value, which frames QinetiQ Group as undervalued rather than overpriced. Which framework do you trust more: cash flow or dividend policy?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages in the QinetiQ Group story can be useful if you let them challenge your own thinking and then test the numbers yourself. To weigh the balance between contract strength, valuation disagreement and sentiment, take a close look at the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond QinetiQ Group?
If QinetiQ Group has sharpened your focus on quality and valuation, do not stop here. Use the Simply Wall Street screener to spot what others might miss.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (10 results) that align with disciplined debt and cash discipline.
- Hunt for mispriced opportunities through the 15 high quality undervalued stocks that blend cash generation with supportive fundamentals.
- Build a cash flow focused watchlist by checking out the 4 dividend fortresses that combine income potential with underlying business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com