


EN
Is OPKO Health (OPK) Still Undervalued After Its Q3 2026 Earnings Call?
OPKO Health (OPK) is back on investors’ calendars after the company scheduled its Q3 2026 earnings release and conference call for today, 4 November. This has drawn fresh attention to the healthcare group’s recent share performance.
That renewed focus lands on a stock that has already been rebuilding interest, with OPKO Health’s share price delivering a 90 day return of 27.41% and a year to date share price return of 35.43%, even as the 5 year total shareholder return is down 58.35%. This contrast indicates that recent momentum differs markedly from a more difficult long-term record.
Spot similar healthcare turnarounds and momentum stories by scanning our hand-picked 34 healthcare AI stocks as you consider what OPKO Health’s latest earnings call could mean for your portfolio.OPKO Health brings a mix of early stage drug assets, diagnostics scale and ongoing losses, alongside a share price that has run hard in recent months. Does that combination translate into a fair valuation today?
Most Popular Narrative: 59% Undervalued
OPKO Health closed at $1.72, while the most followed narrative anchors fair value at $4.15, implying a wide gap that hinges on how its pharmaceutical and antibody pipeline turns into cash flow over time.
The repeated use of non dilutive royalty backed notes on mazdutide, large expected cash proceeds and earnouts from Labcorp transactions and ongoing BARDA funding of MDX2301 and other programs provide funding sources that can support R&D investment of about US$125 million to US$135 million and share repurchases without relying on equity issuance, which can help future earnings per share if operating performance improves.
See why 16 investors see OPKO Health as 59% undervalued.
On this view, the fair value of $4.15 is built using a 7.28% discount rate and assumes OPKO Health eventually earns a 6.3% profit margin on $628.3 million of revenue by around 2029, producing $39.7 million of earnings and supporting an 88.6x P/E multiple on those future profits. That is a punchy valuation that already bakes in meaningful success from ModeX antibodies, NGENLA profit sharing and the broader endocrine portfolio even though the group currently reports a net loss of $72.9 million on $587.9 million of revenue.
The same narrative flags that analysts are not forecasting profitability over the next 3 years and that earnings are expected to decline by an average of 12.6% a year over that period. As a result, the investment case leans heavily on what happens beyond the near term and on management using non dilutive funding to support roughly $125 million to $135 million of annual R&D without leaning on fresh equity. For readers weighing that trade off, the share price today effectively asks whether this combination of losses, higher margin ambitions and funding structure earns the rich multiple implied by the $4.15 fair value.
Result: Fair Value of $4.15 (UNDERVALUED)
Still, the OPKO Health narrative is fragile if operating losses persist near guided cost levels or if key partnerships and antibody programs fail to turn into dependable cash flow.
Find out about the key risks to this OPKO Health narrative.
Another View: OPKO Health Looks Expensive On Sales
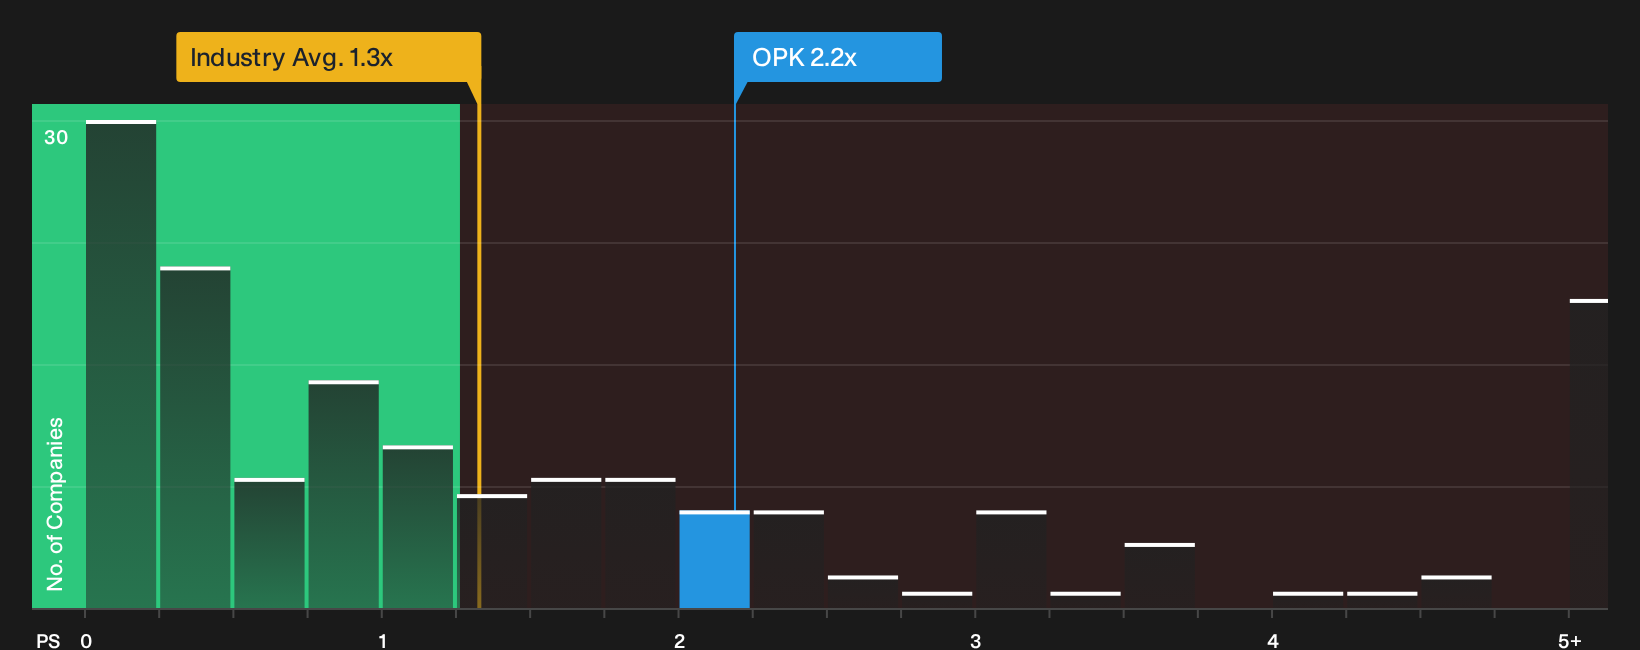
The story changes when you stop at the income statement and look only at what the market pays for OPKO Health’s revenue. At a P/S of 2.2x, the stock trades well above both the US Healthcare average of 1.4x and close peers at 1.6x, while the fair ratio points to just 0.5x.
If pricing eventually moves closer to that fair ratio, investors are taking clear valuation risk for a business that is still loss making and is currently estimated to see earnings decline. How comfortable are you paying a premium multiple today for a company that has not yet proved it can earn a consistent profit?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about whether OPKO Health’s recent share price strength outweighs its long track record of losses and rich revenue multiple? Act quickly, review the underlying data, and weigh the 2 important warning signs.
Looking for more OPKO Health style investment ideas?
If OPKO Health has you thinking harder about risk, reward and timing, do not stop at a single ticker. Use the Simply Wall St screener to pressure test your next moves, compare setups across sectors, and avoid missing opportunities hiding in plain sight.
- Target stronger upside potential by scanning a focused pool of 19 high quality undiscovered gems that pair quality fundamentals with underfollowed stories.
- Protect your downside first and build around 30 resilient stocks with low risk scores that score well on resilience while still offering room for returns.
- Anchor your portfolio in financial strength by reviewing the list of solid balance sheet and fundamentals (23 results) that can better handle shocks and funding needs.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com