


EN
Merit Medical Systems (MMSI) Stock Could Be Undervalued After New Deal
Merit Medical Systems has seen its share price slip in the short term, yet a multi year gain and fresh deal making now put the spotlight on a different question for investors: whether the current valuation is supported by the cash the business can generate over time.
- Over the past 5 years the stock has gained 23.9%, which raises the question of how much future cash flow is already reflected in today's price.
- The recent Solo Pace acquisition, along with higher revenue and earnings expectations, can shift views on how durable and sizable Merit Medical Systems' future cash flows might be.
- If you'd rather focus on earnings, this one's for you. See why Merit Medical Systems's 31.5x P/E tells a different valuation story.
The issue now is whether the current share price of Merit Medical Systems is justified by the cash flows implied by a Discounted Cash Flow (DCF) intrinsic value estimate.
If you are weighing Merit Medical Systems on its cash flows after this Solo Pace deal and guidance update, it can help to compare that story with 35 high quality undervalued stocks
Is Merit Medical Systems Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at the cash Merit Medical Systems can return to shareholders over time. On the latest twelve month numbers the group generated about $208.5 million in free cash flow, and the model assumes that figure continues to grow rather than reset lower or swing sharply negative.
Projected annual free cash flows step up toward the high $200 million range by 2028, then rise more gradually after that, which is closer to a mature medical devices profile than a hyper growth story. Because the Solo Pace deal and the raised 2026 guidance point to management leaning into cardiac therapies, the DCF outcome sitting meaningfully above the current $84.16 share price suggests the market is not fully pricing in those projected cash streams. The acquisition of Solo Pace for about $45 million helps explain why the cash flow curve in the model assumes sustained activity in Merit Medical Systems' core procedures. The gap between the DCF output and the traded price is what investors will want to test for themselves against alternative scenarios. Find out what Merit Medical Systems could be worth using our Discounted Cash Flow (DCF) estimate.
The Merit Medical Systems Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DCF puzzle for Merit Medical Systems leaves off and spell out what combination of future growth, margins and earnings would need to play out for the stock to look materially higher or lower than today. Each scenario ties its number to a clear view of how Merit Medical Systems' growth profile, profitability and risk picture might evolve, which you can revisit on the Community page as fresh information arrives.
One of the top community narratives on Merit Medical Systems: 21% undervalued
"The current valuation implies the share price may not fully reflect this track record of margin expansion, organic growth near the top of current guidance…"
Discover why this Narrative puts Merit Medical Systems at 21% undervalued.
For Merit Medical Systems, price is only one piece of your decision
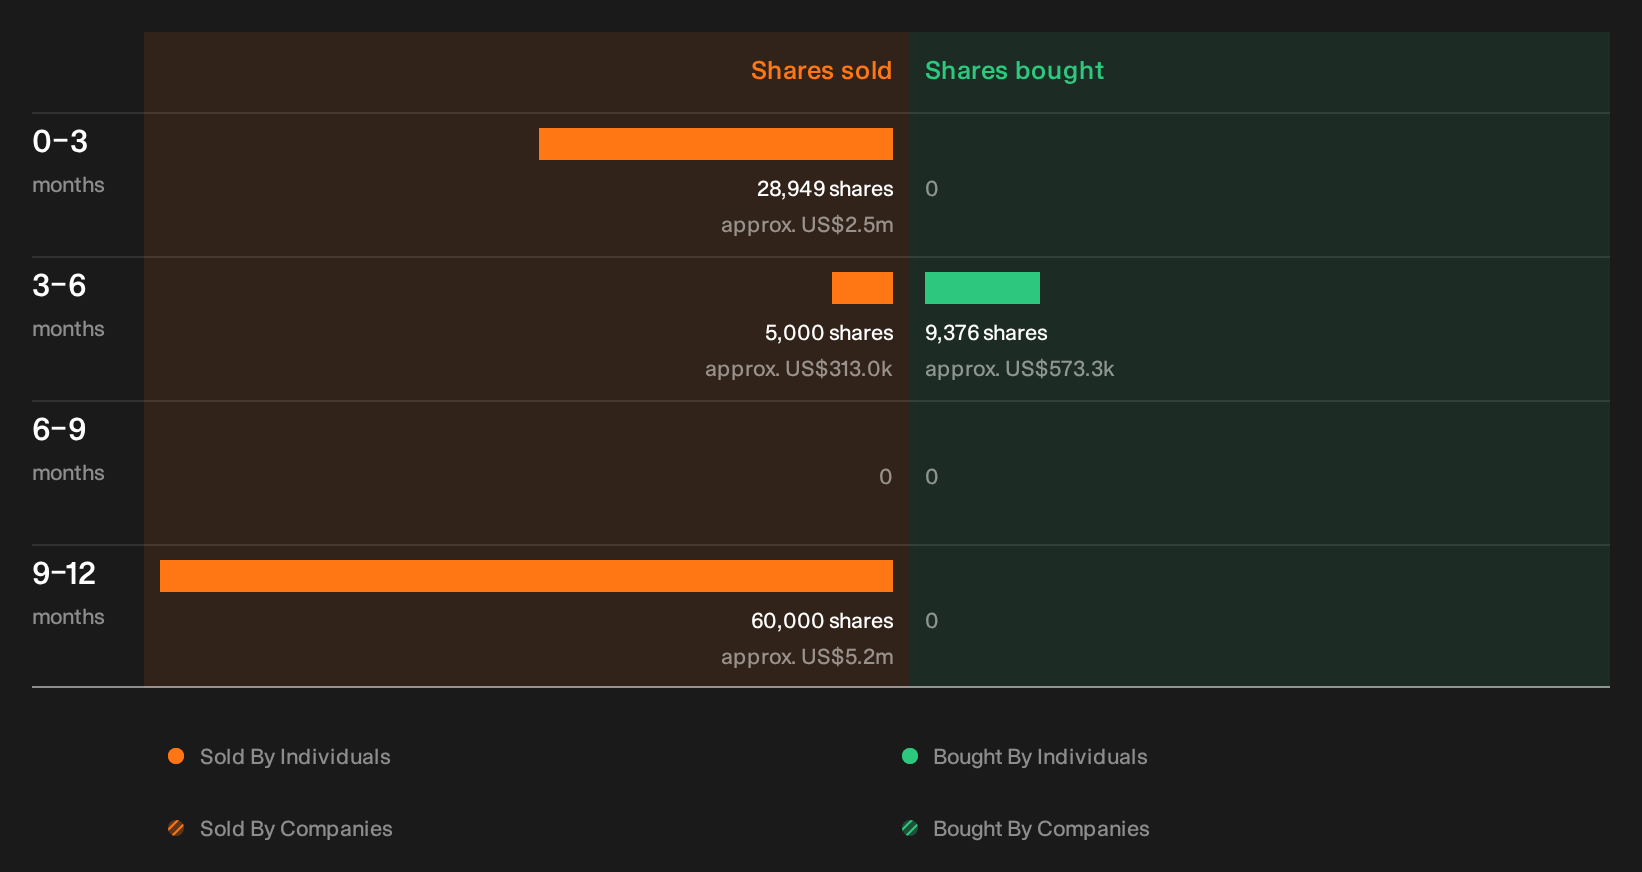
Valuation models tell part of the story, but recent insider transactions add a different clue about how people inside Merit Medical Systems are acting today, and the who, how much and why are all still for you to review. See the recent insider selling flagged for Merit Medical Systems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com