


EN
Fiserv Stock Faces Earnings Miss After $6.45 Billion Goodwill Write Down
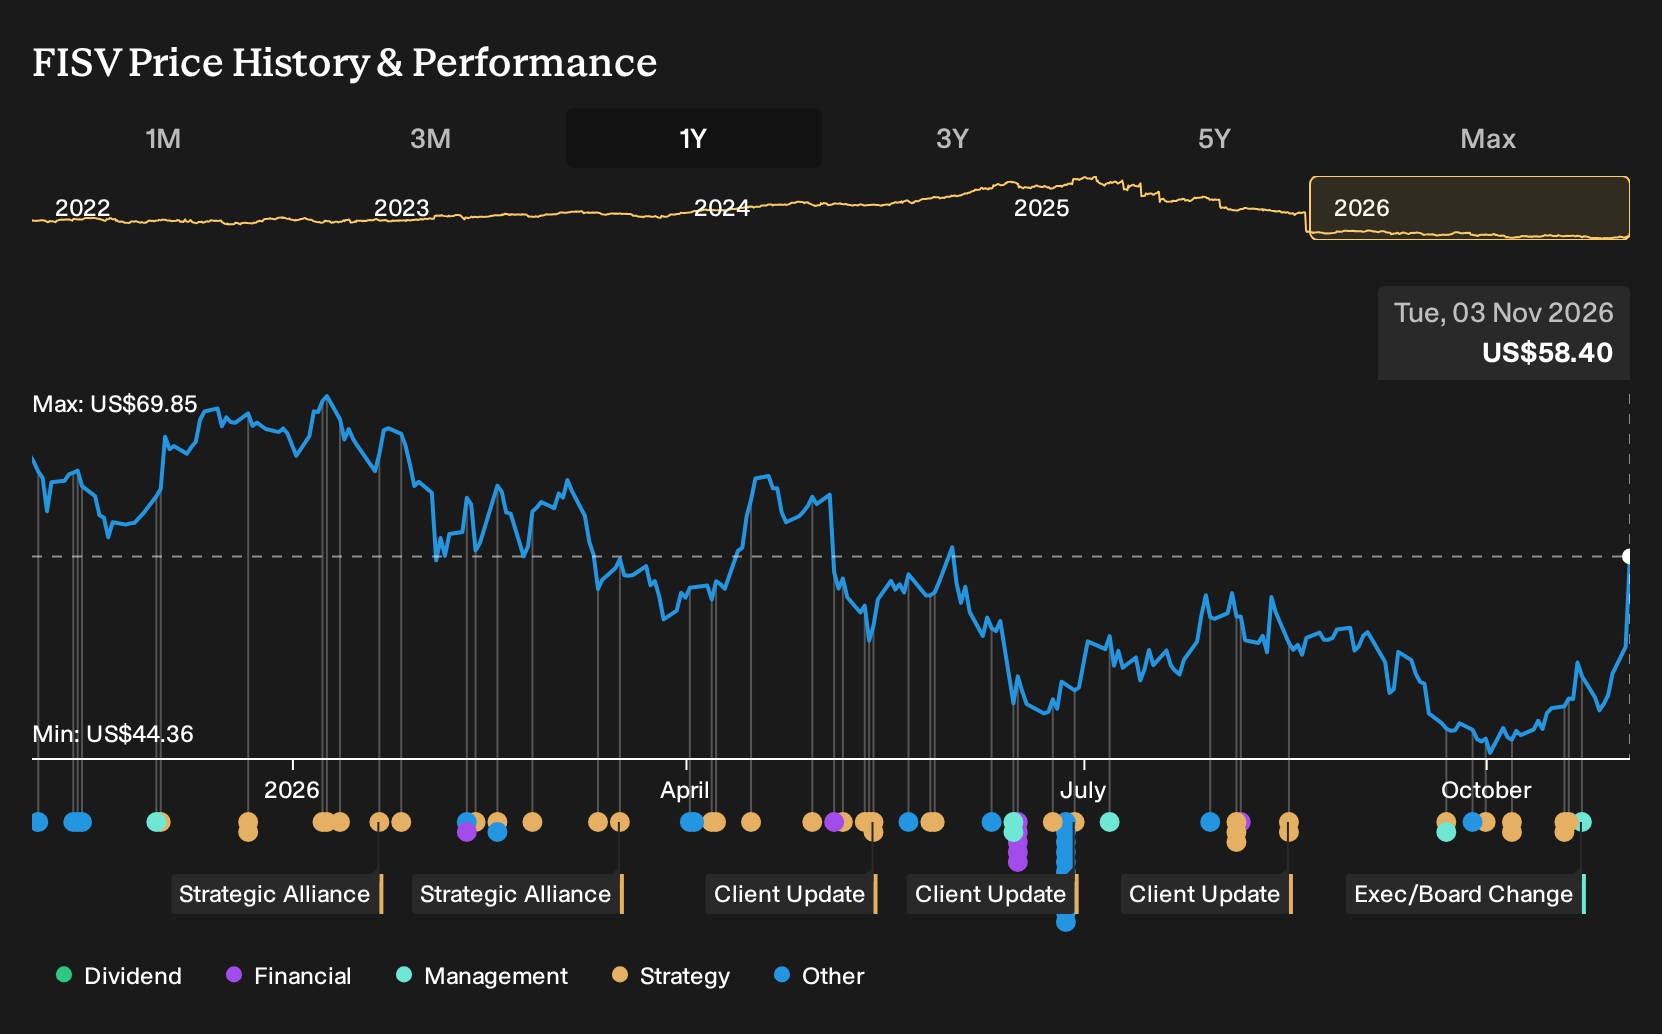
- Fiserv reported third quarter 2026 results with revenue of US$5.196b, a net loss of US$5.941b, and a diluted loss per share of US$11.17, largely shaped by a US$6.45b non cash goodwill impairment.
- The combination of a large goodwill write down, year on year revenue softness, and affirmed full year guidance for a slight GAAP revenue decline highlights pressure on both Fiserv's earnings profile and the assumptions behind past acquisitions.
- The focus now shifts to how Fiserv's investment narrative holds up when set against a sharp goodwill impairment and deep quarterly loss.
Fiserv Investment Narrative Recap
To own Fiserv, you need to be comfortable with a story built on a large recurring revenue base, cost programs like Project Elevate, and platform modernization across Merchant and Financial Solutions. The latest quarter stresses that belief. Revenue was slightly softer and a US$5.941b loss driven by a US$6.45b goodwill impairment puts execution and capital allocation under a brighter spotlight.
In the near term, the key catalyst is whether management can keep delivering on efficiency and integration plans while stabilising top line trends. The biggest operational risk is that revenue pressure in core segments and slower Clover contribution persist, which would make it harder to convert those cost actions into a healthier earnings profile.
The most relevant announcement for this earnings print is Fiserv affirming 2026 GAAP revenue guidance for a 1.5% to 0.5% decline. Management is effectively stating that, despite the impairment and year to date net loss, reported revenue expectations for the year are not changing much.
That stance keeps the focus squarely on margin execution, cash generation and delivery on programs like One Fiserv and Project Elevate as the practical near term triggers. It also increases the risk that any future cut to guidance, if revenue softness deepens, would land harder with investors who are already weighing a goodwill reset against the long term modernization and AI product roadmap.
Fiserv's current earnings sit at US$2.8b, while analysts collectively project revenue of US$21.3b and earnings of US$3.1b by 2029. That profit outlook implies roughly US$0.3b more earnings than today on a revenue line that is expected to remain fairly flat over the next 3 years.
Uncover why Fiserv's fair value indicates a valuation gap that is approximately aligned with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Project Elevate as the swing factor for Fiserv, arguing that cost savings could still support earnings closer to US$4.0b by 2029 on revenue around US$21.7b. You can compare that pre earnings optimism with your own view now that goodwill has been reset and decide which narrative feels more realistic for you.
Explore 13 other Fiserv fair value estimates, including one that suggests potential upside of as much as 105% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Fiserv research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fiserv. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fiserv's overall financial health at a glance.
Looking for more investment ideas beyond Fiserv?
Once you have formed a view on Fiserv, it can help to set it alongside other options that fit your style, risk tolerance, and return targets. The Simply Wall St Screener is built for exactly that kind of comparison, letting you filter by quality, balance sheet strength, income potential, and more in a few quick steps.
- If capital preservation ranks high for you, start by scanning 30 resilient stocks with low risk scores that pair resilience with more measured return profiles.
- For investors hunting for mispriced quality, compare Fiserv against 35 high quality undervalued stocks that combine strong fundamentals with what looks like a modest market expectation.
- If you want more robust financial footing across your watchlist, broaden your research with a list of solid balance sheet and fundamentals (23 results) that can sit alongside or even substitute positions like Fiserv.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com