


EN
Hyatt Hotels (H) Prices $400 Million Notes As Investors Weigh Whether The Story Is Fully Valued
Hyatt Hotels (H) has priced a US$400 million senior notes offering maturing in 2033. Management plans to refinance existing 2027 debt and allocate the remaining funds to general corporate purposes.
Hyatt Hotels shares have climbed 16.7% over the past month and 12.0% year to date. The 1-year total shareholder return of 37.4% and 5-year total shareholder return of 109.3% point to momentum that has been building rather than fading.
Scan how other hospitality and travel names with balance sheet stories similar to Hyatt Hotels line up in our hand picked list of solid balance sheet and fundamentals (23 results).
Bulls see Hyatt Hotels using its bond issue and strong recent share gains as evidence the story still has room to run. Bears point to richer expectations. Which side do the current valuation markers support?
Most Popular Narrative: 19% Undervalued
Hyatt Hotels closed at $185.44, while the most followed narrative pegs fair value at $228. That gap rests on the idea that a more asset light, fee heavy model and rising earnings power are not fully reflected in today’s price.
The main thing that has to go right is that Hyatt Hotels continues to grow high fee luxury, lifestyle and upper mid scale rooms globally while its loyalty and technology investments keep owners profitable despite regional shocks.
The current numbers on fee growth, cash generation and net rooms growth imply a share price that does not fully reflect Hyatt Hotels’ shift to a higher margin, asset light and loyalty driven earnings mix.
See why 0 investors see Hyatt Hotels as 19% undervalued.
Result: Fair Value of $228 (UNDERVALUED)
Still, the bullish Hyatt Hotels story can fray if the roughly US$15 million fee drag in Mexico and the 36% RevPAR drop in the Middle East persist longer than expected.
Find out about the key risks to this Hyatt Hotels narrative.
Another View: Hyatt Hotels Looks Expensive On Earnings
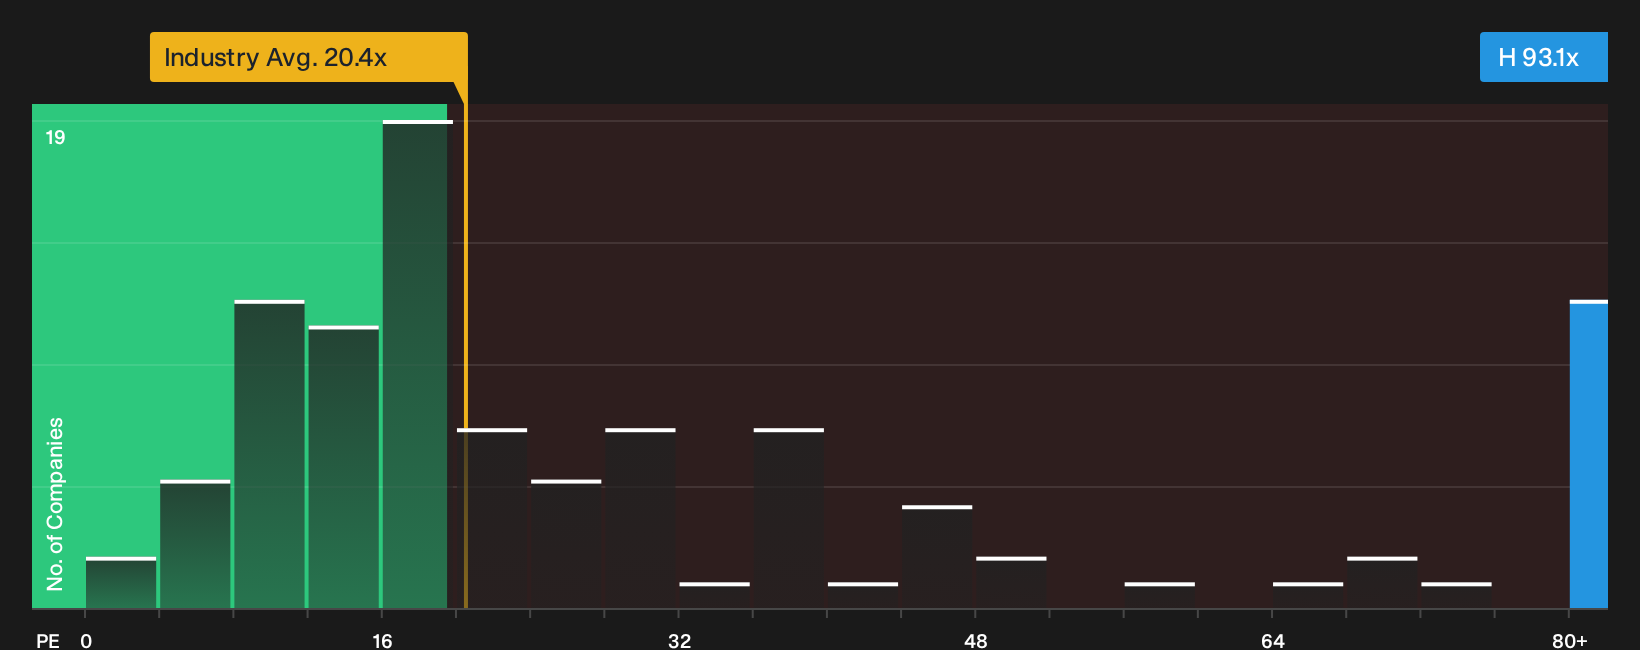
On cash flow assumptions, Hyatt Hotels screens as 10.5% below an internal fair value estimate of $207.11. On earnings, the picture is very different. The current P/E of 93.1x sits well above the US Hospitality average of 20.1x and a fair ratio of 35x, which points to rich expectations if earnings forecasts slip.
That kind of gap can reward investors if profit growth lands exactly as hoped, or punish them quickly if the story cools. It raises a simple question: which signal do you trust more when the future does not play out in straight lines?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Hyatt Hotels can feel uncomfortable, which is exactly why this is the moment to inspect the data yourself and decide where you stand. To help weigh both the potential upside and the issues investors are watching, start with our breakdown of 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hyatt Hotels?
If Hyatt Hotels has sharpened your focus on quality and risk, use that same lens to hunt for other opportunities that fit your style.
- Zero in on quality at a discount by scanning our curated pool of 35 high quality undervalued stocks that combine solid fundamentals with appealing prices.
- Prioritise staying power and sleep at night potential by combing through a hand picked 30 resilient stocks with low risk scores designed to highlight resilient businesses.
- Chase differentiated stories before the crowd by reviewing a focused 19 high quality undiscovered gems built to surface underfollowed companies with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com