


EN
Moog (MOG.A) Stock Looks Fully Valued On Current Earnings
Moog has been a strong performer over the past few years, which naturally puts the focus on whether the current share price is still grounded in its earnings power. With a track record that has rewarded patient holders, the question now is how much of that story is already reflected in today's valuation.
- Over the last 5 years the stock has returned 364.1%, so a lot of value creation is already on the table and earnings need to carry that weight.
- The business relies heavily on converting its engineering work into consistent profits, so trends in margins and cash generation can play a big role in how sustainable the current earnings base really is.
- Your read on Moog is one view; the desks covering it have another. See what analysts think Moog's shares could be worth.
The issue now is whether the current share price is properly aligned with what Moog actually earns today and what those earnings reasonably support.
If you want more context around Moog's earnings driven run, compare it with other companies through the 35 high quality undervalued stocks.
Is Moog Getting Expensive on Earnings?
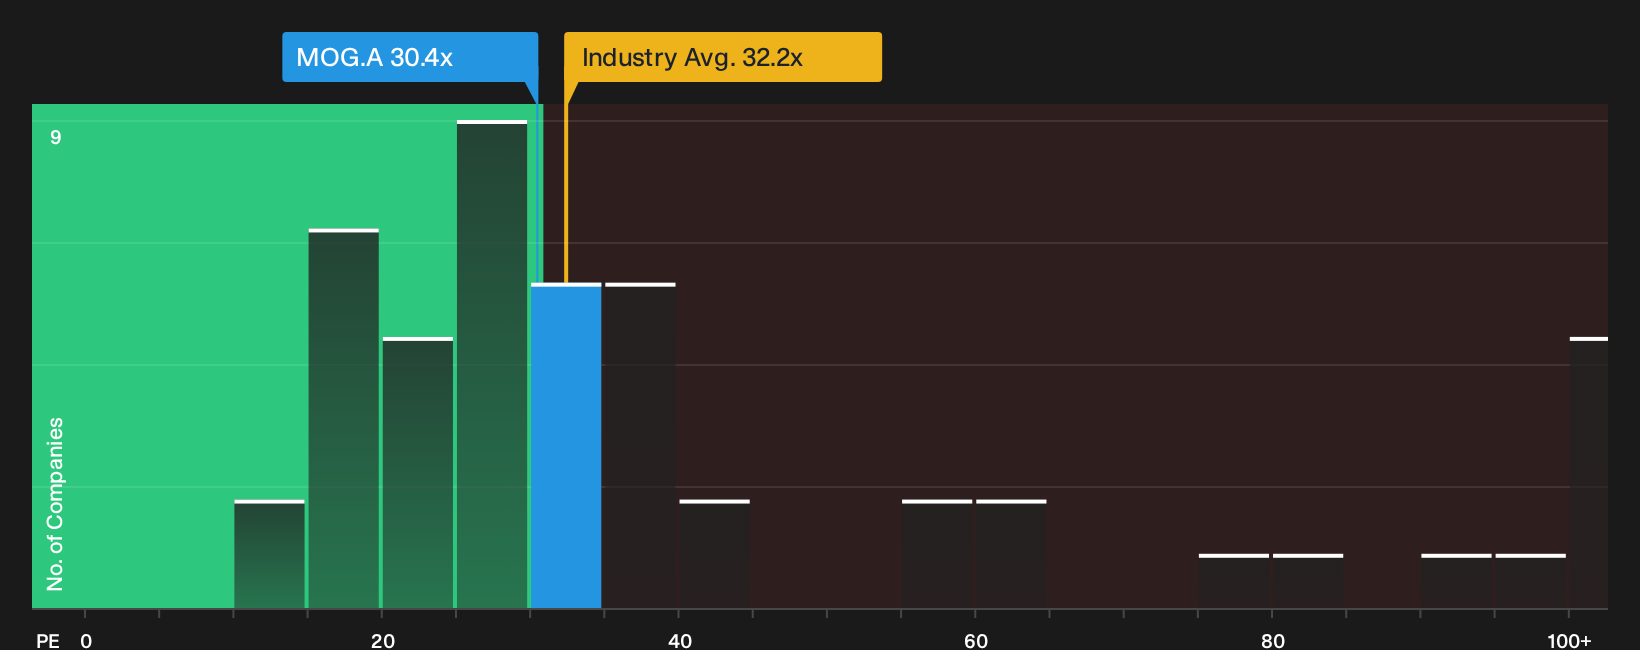
The P/E ratio is a useful lens for Moog because earnings drive so much of how investors think about established aerospace suppliers. On this measure, the stock trades on a P/E of 30.4x, which is above the peer group average of 25.9x but below the broader Aerospace & Defense sector on 32.2x. That mix suggests investors are already paying a premium to closer comparables even though the share price is not at the top of the wider industry range.
The fair P/E level implied by Moog’s own profile, including its profitability, business mix and risk, comes in lower than where the equity currently changes hands. That gap means the shares screen as overvalued on this framework, with buyers accepting a richer earnings multiple than the model suggests for the company’s characteristics. For anyone considering the stock, the key question is whether Moog’s earnings quality and resilience justify that extra P/E premium over more typical valuations. Explore the numbers behind Moog's P/E valuation.
The Moog Narrative: What Would Justify Today's Price?
Moog’s valuation puzzle really comes into focus once you start testing different stories about its future earnings power, and Simply Wall St Narratives are built to lay those stories out clearly. Each scenario ties a fair value to a specific mix of growth, margins and durability of earnings so you can see which potential catalysts and risks matter most. You can then track over time which version of Moog’s journey appears to be unfolding on the Community page.
One of the top community narratives on Moog: 19% undervalued
"Rapid expansion of missile program revenues, supported by new 7 year agreements that are not yet fully reflected in the backlog…"
Discover why this Narrative puts Moog at 19% undervalued.
Before acting on Moog's valuation, weigh who is steering the ship
The numbers only go so far when the long term course of Moog depends on the people in charge, how they think, and the way their rewards line up with your outcomes. See who runs Moog and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com