


EN
Everforth Stock Outlook After Earnings Guidance And WisdomAI Partnership
- Everforth, Inc. reported third quarter 2026 sales of US$1,031.4 million with net income of US$23.1 million, issued fourth quarter revenue and earnings guidance, and confirmed completion of a US$77.5 million share repurchase program, while also announcing an AI focused partnership with WisdomAI for enterprise analytics.
- The combination of softer profitability, detailed near term guidance and an expanded AI analytics offering through WisdomAI puts Everforth’s margin efficiency and execution on higher value consulting work in clear focus for investors.
- We will now see how Everforth’s updated earnings guidance and profitability trends could reshape the investment narrative investors have been using.
Compare Everforth's AI consulting pivot with other potential breakouts by scanning a curated list of 40 profitable AI stocks that aren't just burning cash.
Everforth Investment Narrative Recap
To own Everforth, an investor needs to believe the consulting-heavy model in cloud, AI and cybersecurity can translate into steadier earnings despite near term margin pressure. The third quarter showed sales of US$1,031.4 million, but net income of US$23.1 million and lower EPS than a year ago keep cost discipline and pricing power firmly in focus.
The fourth quarter guide for US$965.0 million to US$995.0 million of revenue and US$17.9 million to US$25.5 million of net income makes profitability the key short term catalyst. Execution against that range, especially on margins, sits alongside the biggest risk right now: that profit trends remain weak even as demand holds up.
The WisdomAI partnership is the announcement that most closely ties into this earnings update. Everforth is leaning harder into AI consulting and data-rich projects, and WisdomAI’s Agentic Analytics platform gives the firm a way to turn fragmented client data into governed, actionable intelligence that can support higher value work.
This matters for catalysts because consulting mix, AI contracts and ecosystem relationships are central to the bullish narrative on margins and earnings growth. The alliance also highlights an execution risk. If Everforth struggles to convert this broader AI toolkit into larger, repeatable programs, revenue quality and profitability could lag the expectations embedded in current forecasts.
Everforth's narrative projects US$4.4b revenue and US$188.4 million earnings by 2029. This assumes 3.0% yearly revenue growth and an earnings increase of about US$120.4 million from US$68.0 million today.
Uncover how Everforth's fair value indicates a 12% potential upside to its current price before the market closes the gap.
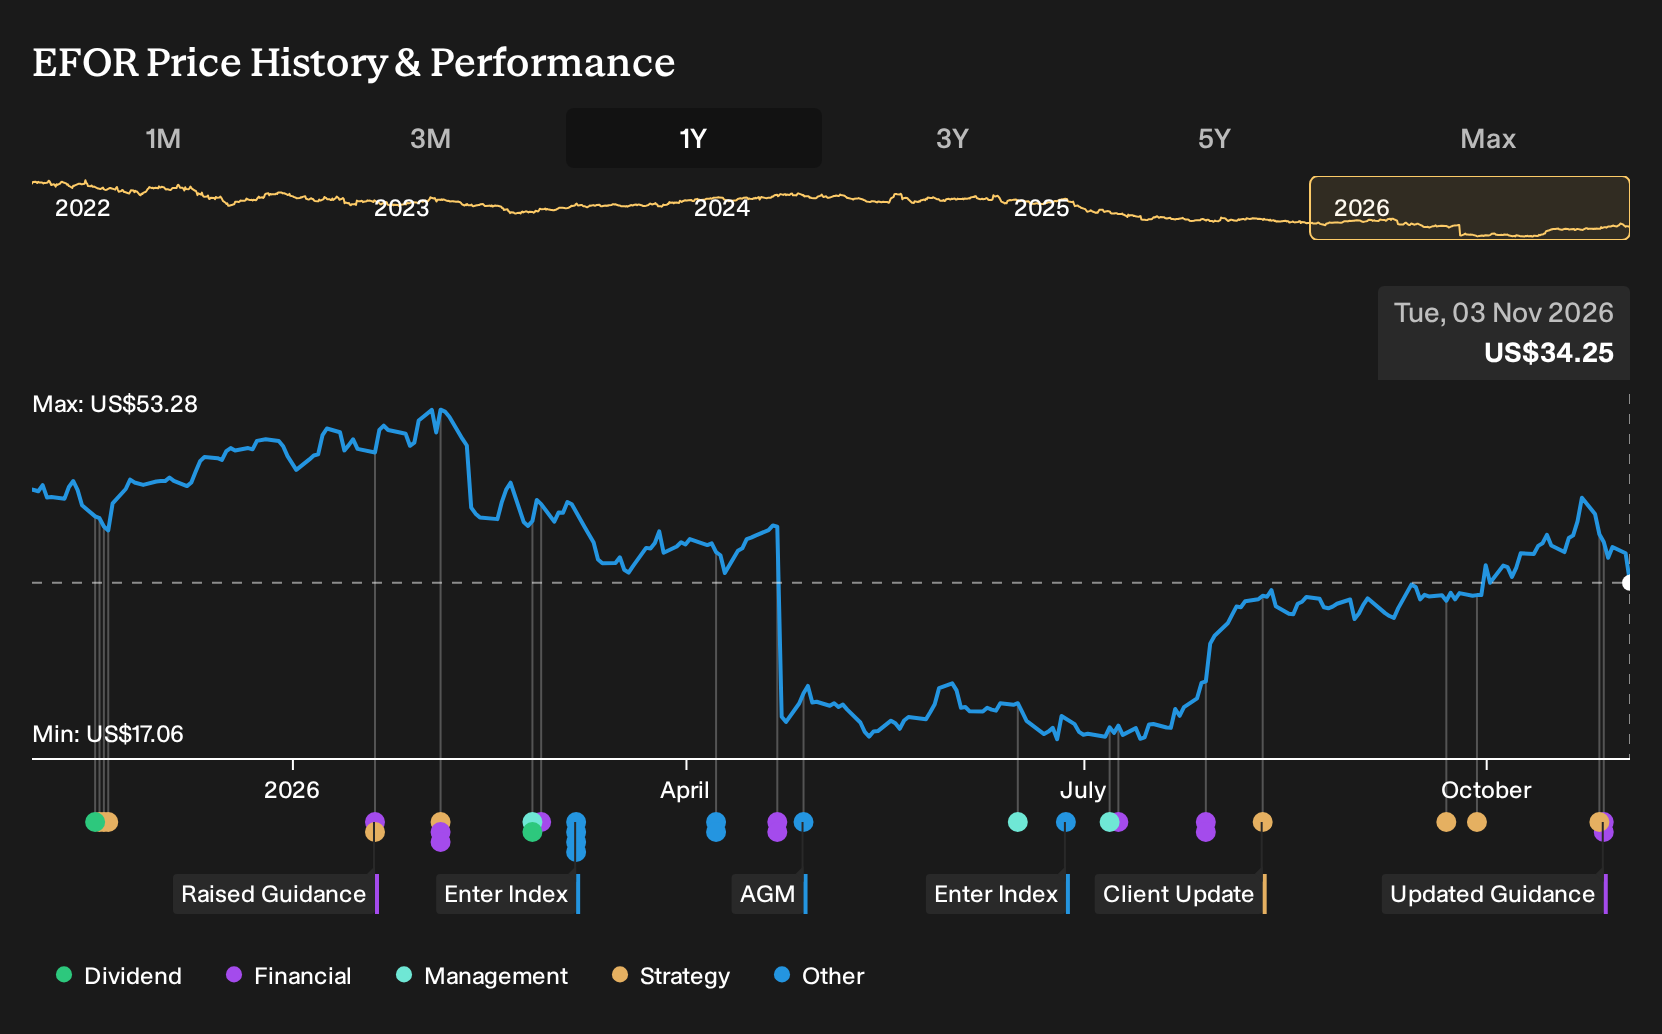
Exploring Other Perspectives
For a different angle, focus on one bullish catalyst. The most optimistic analysts lean hard into Everforth’s AI consulting shift, expecting revenue of about US$4.4b and earnings near US$222.4 million by 2029 before this latest quarter and guidance. Those projections are more upbeat than consensus, and the new AI partnership and outlook could push views even further apart. Readers can compare these narratives and decide which assumptions feel reasonable.
Explore another Everforth fair value estimate, including one that suggests as much as 99% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your Everforth research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Everforth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Everforth's overall financial health at a glance.
Looking For More Investment Ideas Beyond Everforth?
Once you have a view on Everforth, it can help to place it alongside other opportunities with different risk and income profiles. The Simply Wall St Screener gives you a way to filter that broader universe quickly so you can focus on a shortlist that actually fits your goals.
- If capital protection and steadier business profiles rank high for you, scan a 30 resilient stocks with low risk scores that score well on resilience metrics and lower overall risk.
- For investors who want quality but do not want to overpay, compare Everforth against a 35 high quality undervalued stocks that combine solid fundamentals with valuation support.
- If strong finances matter most, start with a list of solid balance sheet and fundamentals (23 results) that pair cleaner balance sheets with underlying business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com