


EN
Why Imperial Oil (TSX:IMO) Is Getting Attention Today
Imperial Oil (TSX:IMO) moved into focus after record third quarter earnings, a completed share buyback, and an unchanged quarterly dividend of CA$0.87 per share signalled continued capital returns to investors.
The recent record earnings, dividend affirmation and completed buyback come alongside a strong price move, with Imperial Oil’s share price delivering a 7.23% 90 day return and a 54.06% year to date gain, while the 5 year total shareholder return of 391.47% indicates powerful longer term momentum.
Scan how Imperial Oil’s record earnings, dividend commitment and completed buyback compare across the sector by reviewing a hand picked set of energy producers in the 4 high quality undervalued stocks screener.
Imperial Oil shares have already moved hard on record earnings and heavy buybacks, so the real tension now is simple. Does paying up today still make sense on the numbers, or does patience win?
Most Popular Narrative: 14% Overvalued
Imperial Oil closed at CA$188.43, while the most followed narrative pins fair value nearer to CA$165.59 using a 6.44% discount rate. This suggests the story leans toward a full price that already bakes in a lot of good news.
The main thing that has to go right is that Imperial Oil delivers on technology-driven cost and productivity targets at Kearl and Cold Lake, while progressing solvent-based in situ pilots and restructuring plans that aim to lower unit operating costs and overhead.
The numbers and this narrative’s view that Imperial Oil is fairly valued imply the share price already reflects both the company’s recent free cash generation and its commitment to return surplus cash through dividends and buybacks.
See why 30 investors see Imperial Oil as 14% overvalued.
Result: Fair Value of CA$165.59 (OVERVALUED)
Still, if decarbonization rules tighten faster than expected or if sustaining capital at Kearl and Cold Lake remains heavy, Imperial Oil’s earnings story could look very different.
Find out about the key risks to this Imperial Oil narrative.
Another View: What Imperial Oil’s Ratios Are Saying
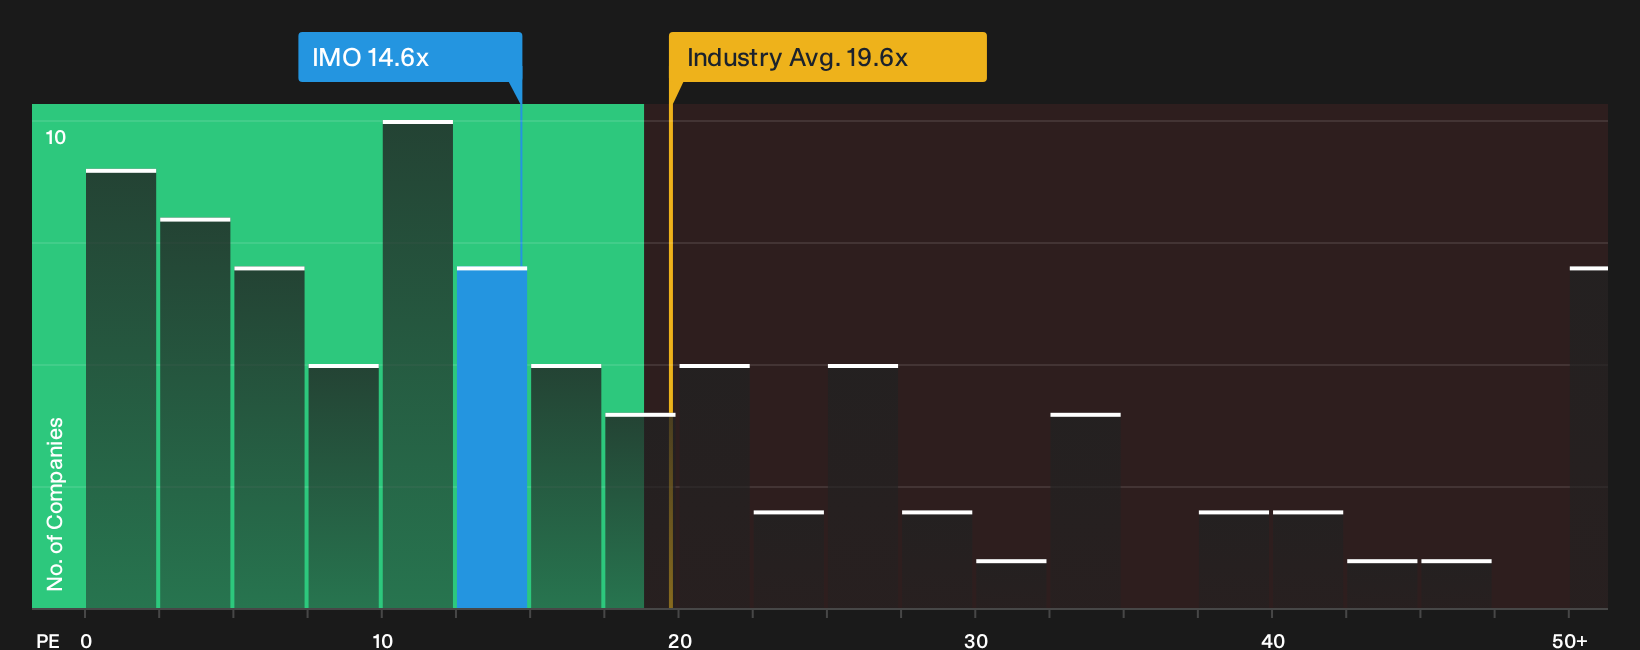
The narrative fair value suggests Imperial Oil is 14% overvalued, yet the current P/E of 14.6x looks cheaper than both peers at 16.1x and the broader Canadian Oil and Gas group at 21.2x. The fair ratio sits at 15.5x, which implies the market could still shift. Is the real risk paying too much, or underestimating how long earnings strength lasts?
To see what the numbers say about this price in more detail, including how that P/E gap compares against the fair ratio over time, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Imperial Oil’s valuation and future cash returns can create strong opinions fast, so act quickly by checking both the upside and the downside yourself. To balance those instincts with the underlying data, walk through the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Imperial Oil?
Imperial Oil is only one piece of the puzzle, and the smartest portfolios cast the net wider so the next opportunity does not slip by unnoticed.
- Target reliable income and stress test your payout expectations against a curated set of high yield opportunities through the 3 dividend fortresses screener.
- Hunt for financially resilient businesses that back up their story with robust balance sheets by scanning the list of solid balance sheet and fundamentals (6 results) screener.
- Unearth potential future leaders before the crowd pays attention by working through the 8 high quality undiscovered gems screener.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com