


EN
Cleveland Cliffs (CLF) Stock Looks Below Fair Value On Sales
Cleveland-Cliffs has delivered a sharp share price swing over the long haul, with shorter term gains sitting against deeper past declines. This leaves a clear question for investors about how the current valuation ties back to its sales base. With fresh headlines around its Canadian steel operations and government expectations on jobs and investment, the issue is whether the revenue the business generates is enough to underpin where the stock trades today.
- The share price is down 37.7% over 5 years. That puts the focus firmly on whether the current market value still lines up with what the company earns from its steel sales.
- Government scrutiny of employment commitments in Canada, alongside new policy support for domestic steel, may influence how investors think about Cleveland-Cliffs' future sales mix, pricing power and the capital it may need to commit to those operations.
- Your read on Cleveland-Cliffs is one view; the desks covering it have another. See what analysts think Cleveland-Cliffs's shares could be worth.
The stock's next move may depend on whether today's price can be justified by the level and quality of sales that Cleveland-Cliffs produces.
If you want to test the same sales linked valuation question beyond Cleveland-Cliffs, scan a wider field of steel and materials names using 35 high quality undervalued stocks.
Is Cleveland-Cliffs a Bargain on Sales?
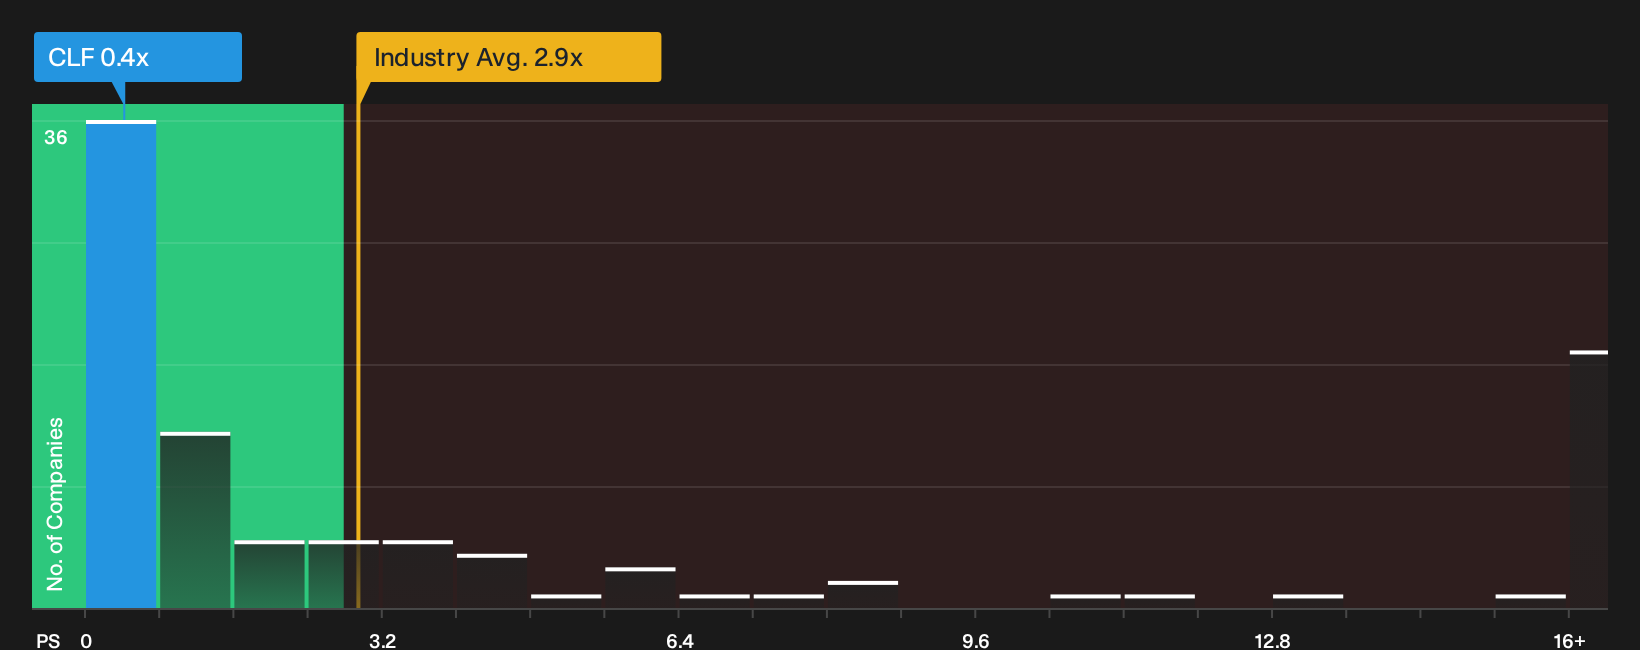
P/S suits Cleveland-Cliffs because investors are weighing it as a steel producer where revenue scale and pricing matter at least as much as accounting profit. On this measure, the stock trades on a P/S of 0.4x, which is far below the broader Metals and Mining sector on 2.9x and also below a narrower peer group average of 1.6x. Because the Canadian government is scrutinising its job commitments while at the same time offering policy support for domestic steel, the current low sales multiple shows the market is not assigning a high premium to that North American footprint.
The fair multiple model, which blends Cleveland-Cliffs specific factors like size, margins, cyclicality and typical pricing in the sector, points to a higher P/S than where the shares trade today. That places the current 0.4x ratio in undervalued territory on this framework, even after the recent Canadian support package for its steel operations improved sentiment around potential future demand. For you as an investor, the gap between price and this tailored benchmark highlights how much weight the market is putting on risks around earnings quality and future steel volumes relative to the revenue already in place. Explore the numbers behind Cleveland-Cliffs's P/S valuation.
The Cleveland-Cliffs Narrative: What Would Justify Today's Price?
Narratives pick up where Cleveland-Cliffs' valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the shares to be worth materially more or materially less than today, on Simply Wall St's Community page. Rather than a single P/S ratio or one model output, each Narrative lays out the assumptions that sit behind its view of fair worth so you can compare those expectations with the results Cleveland-Cliffs reports over time.
Community views on Cleveland-Cliffs are split between those who see more upside in the current setup and others who think expectations already look full.
Bull case: roughly fairly valued
"DOE backed investment at Middletown Works and the Butler Works grain oriented electrical steel expansion, together totaling up to US$1.2b of projects with grant support, are aimed at more efficient and higher value production…"
Discover why this Narrative puts Cleveland-Cliffs at roughly fairly valued.
Bear case: 18% overvalued
"Although Cleveland-Cliffs highlights ongoing unit cost reductions and integration benefits, the first quarter 2026 energy spike that added about US$80 million to costs shows how volatile natural gas, electricity and industrial gases can quickly erode EBITDA and net margins if similar events recur…"
Explore why this Narrative puts Cleveland-Cliffs at 18% overvalued.
One more Cleveland-Cliffs puzzle to check before you move on
Valuation only tells you what Cleveland-Cliffs looks like today. The next layer is what professional analysts think the business could look like a few years from now. Explore where analysts expect Cleveland-Cliffs to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com