


EN
How Investors Are Reacting To NRG Energy (NRG) Ahead Of Earnings Report
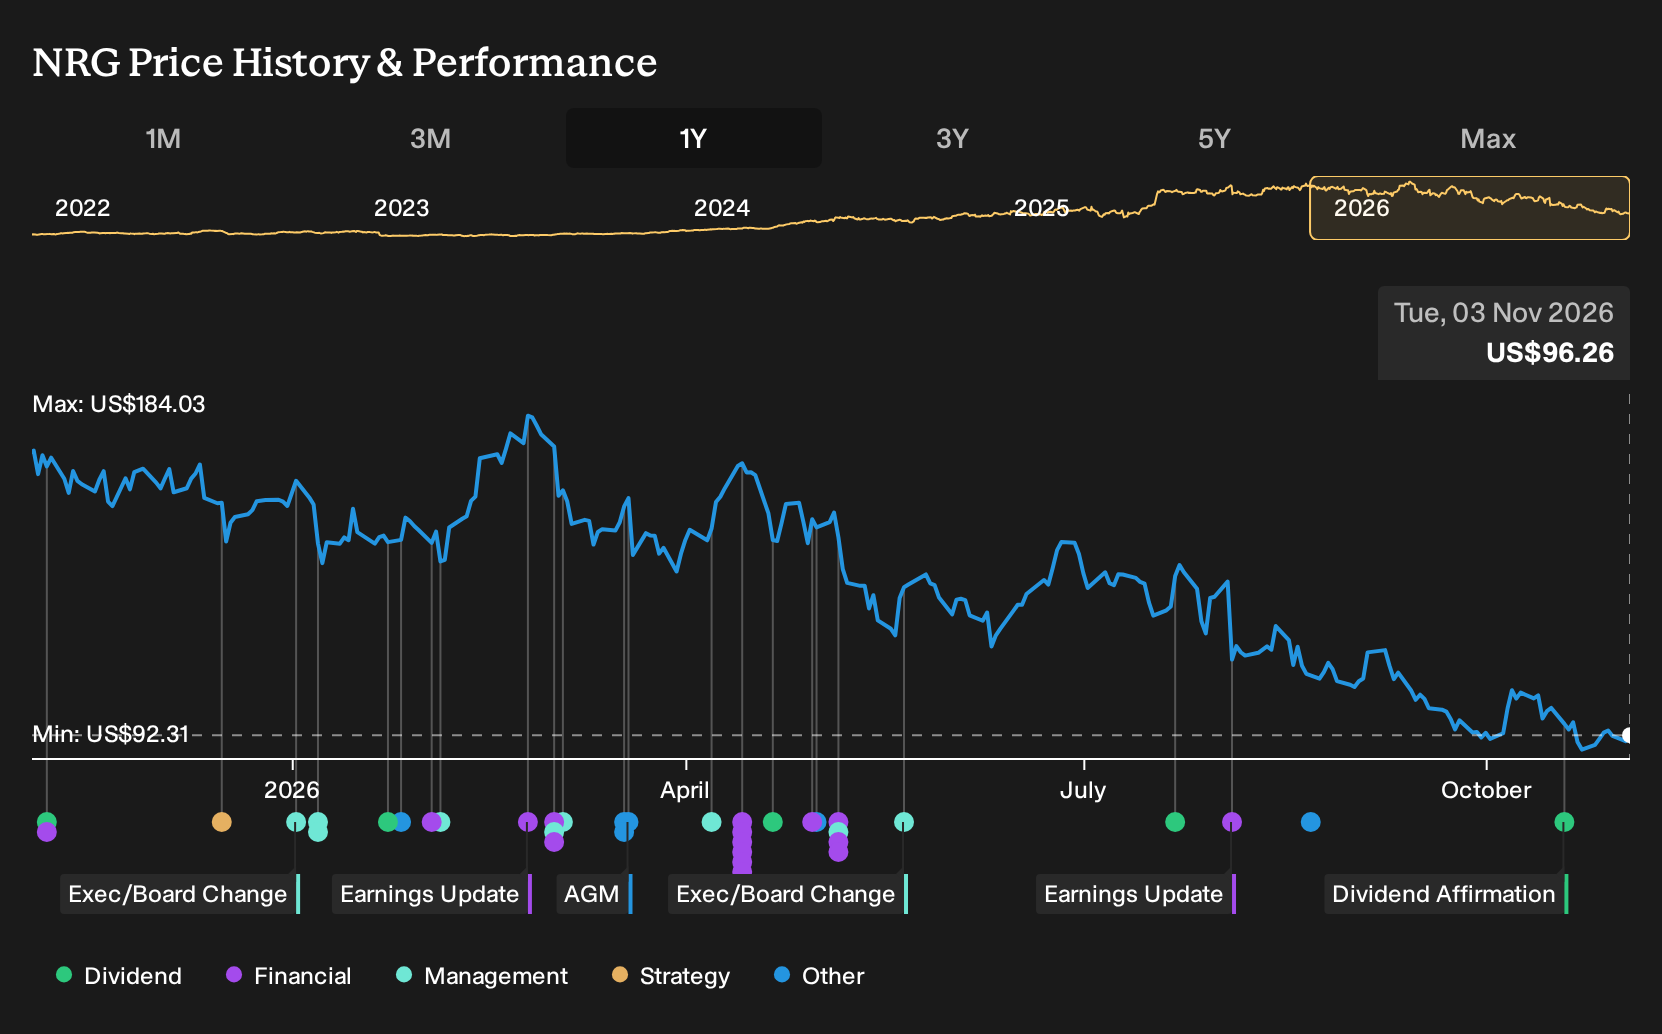
- NRG Energy heads into its November 9, 2026 earnings release with projected EPS of $3.33 and revenue expected to be lower than the prior year, while options on the stock show elevated implied volatility around this catalyst.
- The combination of forecast earnings growth, softer expected sales and unusually high December 2026 call option volatility points to investors focusing less on short term revenue trends and more on how NRG Energy converts its broader power and smart home platform into future cash generation.
- We will now look at how elevated earnings expectations and options volatility might reshape NRG Energy's broader investment narrative.
Scan how traders are positioning around NRG Energy's earnings set up and compare it with other potential movers across 41 power grid technology and infrastructure stocks
NRG Energy Investment Narrative Recap
To own NRG Energy, you need to be comfortable with a gas heavy generation fleet that is being tied to long term AI and data center power needs, plus a growing smart home and retail platform. The near term story revolves around execution on large Texas and PJM gas builds and keeping earnings quality intact as leverage and interest costs stay in focus.
In the short term, the biggest catalyst is the November 9 earnings print, given the projected EPS of $3.33 and softer expected revenue. The key risk is that any earnings miss or weaker Texas profitability, especially with high implied volatility already in options, would raise fresh questions about returns on the large Bring Your Own Power investment.
The most relevant development tied to this setup is the attention on the Dec. 18, 2026 US$45.00 call options, where implied volatility has picked up. That pricing indicates that the market is braced for a sizable move around NRG Energy’s earnings outlook, rather than treating this as just another quarter.
For you as a shareholder or potential shareholder, that options activity matters because it clusters risk around execution milestones on the AI related power projects and near term Texas earnings power. If management can show clear progress on project timelines and contract economics, the elevated volatility becomes more about how quickly the long duration contracts and Vivint driven subscriptions translate into steadier cash generation.
NRG Energy's long term story is anchored to analysts modeling US$38.0b in revenue and US$2.3b in earnings by 2029, based on a 4.7% yearly revenue growth rate. That earnings path represents an increase of about US$1.5b from US$782.0m today, which implies a sizeable step up in profit contribution if the projections play out as expected.
Uncover why NRG Energy's fair value indicates an 86% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
Not every analyst sees the same NRG Energy story. Some of the most optimistic voices lean hard into the AI and data center angle, with bullish forecasts of US$44.7b in revenue and US$2.9b in earnings by 2029, set before this options volatility spike. You should assume those upbeat views could shift after the earnings news.
Explore 5 other NRG Energy fair value estimates, including one that suggests potential upside of up to 400% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns seldom arise from following the herd, so rely on your own analysis and judgment.
- A great starting point for your NRG Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could influence how you think about this company.
- See our latest analysis for NRG Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to review NRG Energy's overall financial profile at a glance.
Looking for more investment ideas beyond NRG Energy?
If the setup around NRG Energy has sharpened your focus on risk, cash flow and balance sheet strength, it can help to line it up against other potential opportunities using a broader stock universe.
- If you want potential mispricings where fundamentals and valuation work together, scan the 35 high quality undervalued stocks and see which businesses fit your checklist.
- If resilience matters more to you than headline growth, compare NRG Energy with a 30 resilient stocks with low risk scores that scores well on financial stability and downside protection.
- If you prefer companies that already show robust finances, widen your watchlist with a list of solid balance sheet and fundamentals (23 results) so you can benchmark NRG Energy against peers with similar balance sheet strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com