


EN
Kadant (KAI) Q3 Results Put Its Undervalued Narrative Back In Focus
Kadant (KAI) just released third quarter results, reporting sales of US$313.16 million and net income of US$35.07 million, giving investors fresh numbers to reassess the stock.
Kadant’s fresh Q3 figures land after a choppy few months for the stock, with the share price down about 16% over the past 90 days but recovering with a 7 day share price return of 5.36% and a 1 year total shareholder return of 3.89%. This points to momentum rebuilding as investors digest both the sector wide rally in specialty industrial machinery and the latest earnings beat narrative from earlier quarters.
Scan how Kadant’s latest quarter stacks up against peers by reviewing a hand-picked group of 19 high quality undiscovered gems in similar capital goods and industrial machinery niches.
The rebound in Kadant after a rough 90 day stretch puts a clear choice in front of you. Is this a reasonable entry point now, or does it make more sense to wait for a cheaper shot at the stock once the valuation work is done?
Most Popular Narrative: 22% Undervalued
Kadant’s most followed narrative pegs fair value at about $361.67 using an 8.7% discount rate, compared with the latest close of $282.79. This puts the current share price at a clear discount to that framework.
The aging installed base that Kadant supports is leading customers to spend more on maintenance and upgrades even when facilities are not running at peak utilization. Record aftermarket parts revenue of US$214.2m in Q2 2026 across segments points to a larger pool of recurring service activity that can support future revenue and earnings quality.
See why 0 investors see Kadant as 22% undervalued.
Result: Fair Value of $361.67 (UNDERVALUED)
Still, the bullish Kadant story can crack if lower gross margins from less favorable mix and acquisition related costs linger, or if Europe’s tougher conditions drag on project conversions.
Find out about the key risks to this Kadant narrative.
Another View: What Kadant’s P/E Is Telling You
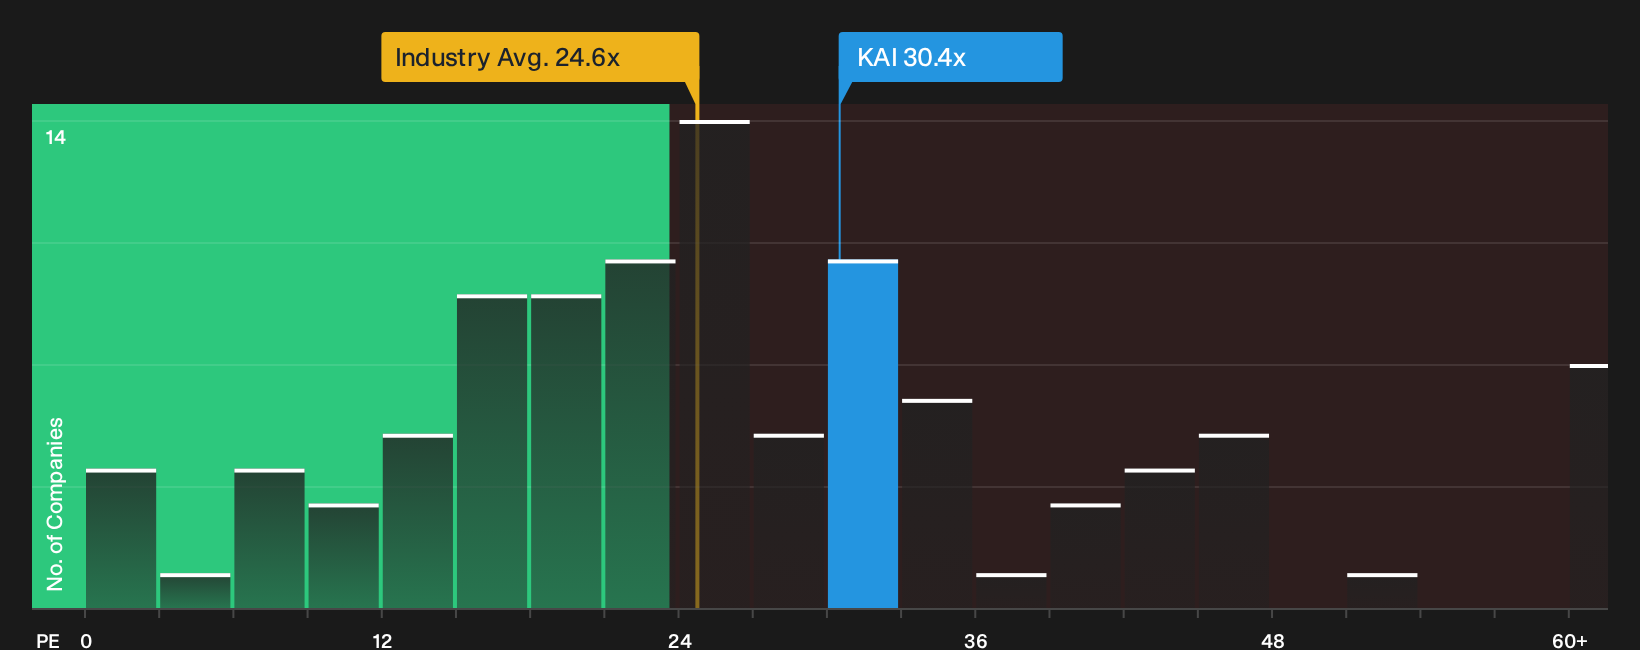
The fair value narrative paints Kadant as undervalued, yet the P/E picture is far less forgiving. The shares trade on 30.4x earnings, compared with 24.4x for the US Machinery group, 21.4x for peers, and a fair ratio of 22.9x. That premium points to valuation risk if growth or margins disappoint.
If you prefer to anchor your work in this earnings multiple view, it is worth stress testing whether Kadant’s premium can hold if sector sentiment cools, or whether the share price could drift back toward that 22.9x fair ratio instead of the bullish target.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone of Kadant’s valuation and P/E debate leaves you on the fence, move quickly to inspect the data and sharpen your own thesis. To see what optimism is already embedded in the story, review the 3 key rewards.
Looking for more investment ideas beyond Kadant?
If Kadant has sharpened your thinking, do not stop here. Broaden your watchlist and pressure test your thesis against other businesses with different strengths.
- Target potential mispricing by scanning a 35 high quality undervalued stocks that blend resilient cash flows with solid balance sheets.
- Build a sturdier core to your portfolio by reviewing a 30 resilient stocks with low risk scores that score well on financial health and volatility.
- Spot tomorrow’s stories early by tracking a 10 elite penny stocks with strong financials that already show stronger fundamentals than most peers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com