


EN
What Is Eli Lilly (LLY) Signaling With Its R&D Reset Beyond Obesity?
- Eli Lilly (NYSE: LLY) pursued US$18.2b of acquisitions in 2026 aimed at reshaping its R&D pipeline beyond obesity treatments.
- New oncology data on first-line KRAS G12C inhibitor olomorasib and antibody drug conjugate sofetabart mipitecan detailed fresh late stage ambitions.
- The group advanced construction of a major US manufacturing site focused on next generation medicines while discontinuing selected gene therapy and autoimmune projects.
- The pivot around olomorasib, sofetabart mipitecan, and pipeline cuts signals a broader Eli Lilly story that is still unfolding. We have also spotted 2 warning signs (1 major) worth knowing about at Eli Lilly.
These shifts in Eli Lilly's R&D mix tie into a wider move toward data heavy drug discovery and production that now extends across 34 healthcare AI stocks.
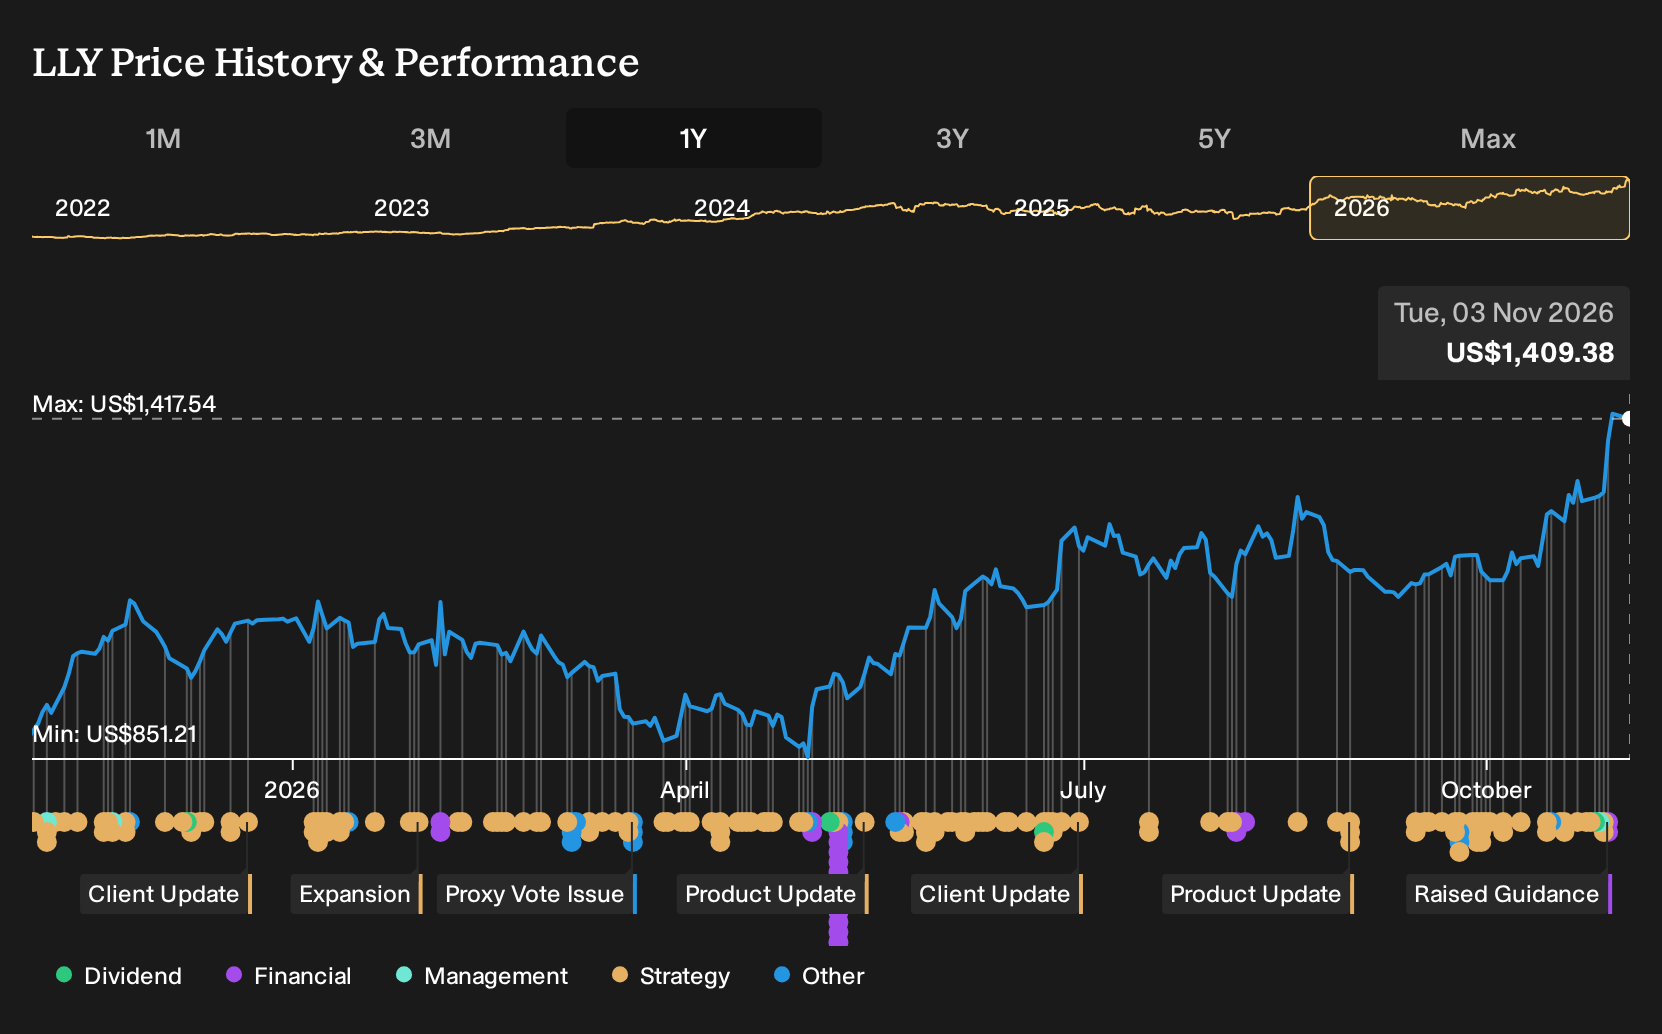
Eli Lilly operates as a large global pharmaceuticals group that discovers, develops, manufactures, and markets human medicines across the US, Europe, China, Japan, and other regions. As a result, shifts in its research priorities and factory build out can reshape multiple treatment areas at once.
Eli Lilly leadership reshuffle has to keep the R&D pivot on track
Eli Lilly's Narrative assumes management can turn GLP-1 demand, a heavier R&D mix in oncology and neuroscience, and a huge factory build into durable earnings power. This recent burst of dealmaking, pipeline pruning and late-stage cancer data only pays off if the new executive structure keeps that execution tight.
"The main thing that has to go right is that Eli Lilly continues to turn strong demand for GLP-1 and related cardiometabolic drugs into durable access and reimbursement, including through programs such as Medicare’s GLP-1 Bridge and expanding self-pay and employer channels, while managing pricing pressure and legal risks..."
See how the full story points towards a $1,397 fair value for Eli Lilly.
The shift to Lilly Global Markets under Ilya Yuffa lines up with this broader R&D reset, because one commercial organisation has to sell not just Mounjaro and Zepbound but future oncology drugs like olomorasib and Sofe M. Retiring long-serving regional leaders while consolidating power raises the bar on execution, particularly with more than US$50b of manufacturing commitments already in motion.
Pipeline cuts in gene therapy and autoimmune disease show management is willing to walk away from projects that do not match this Narrative, which helps focus capital but also leans harder on a smaller set of late-stage bets. For you, this means the leadership transition is not background corporate news, it is a test of whether Eli Lilly can manage access, pricing pressure and a more complex product mix while carrying high debt and significant non cash earnings.
A clear Narrative gives you a yardstick, because it turns scattered headlines about R&D shifts and leadership changes into a coherent decision about whether Eli Lilly's direction still fits your thesis.
One loose thread in the Eli Lilly story sits inside the earnings line
Headline profits tell only part of the Eli Lilly story, because internal checks have raised questions about how clean those reported results really are once you strip them back. See what our checks flag about the quality of Eli Lilly's earnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com