


EN
Knife River (KNF) Issued Fresh Revenue Guidance, Is The Rebound Backed By Fair Value?
Knife River (KNF) just paired its third quarter earnings release with fresh full year 2026 revenue guidance, giving investors an updated read on current trading conditions and management’s expectations.
The earnings release and fresh 2026 revenue outlook arrived alongside a sharp rebound in Knife River’s share price, with a 30 day share price return of 16.29% and a 7 day gain of 6.75%. However, the year to date share price return is still down 19.54% and the 1 year total shareholder return is down 11.61%, which hints that near term momentum is rebuilding after a weaker stretch.
Scan how other materials and construction stocks are reacting to earnings and fresh guidance by reviewing the hand picked list of solid balance sheet and fundamentals (23 results) alongside Knife River’s latest move.
For Knife River, the rebound arrived alongside higher third quarter revenue, lower recent earnings and fresh 2026 guidance. Is the latest share price jump really tracking the underlying business, or just a swing in sentiment that leaves valuation exposed?
Most Popular Narrative: 22% Undervalued
Knife River’s most followed valuation narrative points to a fair value of $75.13 against the latest close at $58.53, which frames the recent rebound as only a partial catch up to that view.
Companywide self help programs such as EDGE and PIT Crew, together with dynamic pricing and process changes that have already lowered per-unit production costs and supported mid single digit aggregate pricing, are set up to further lift gross margins and adjusted EBITDA even as diesel and delivery costs remain a headwind.
See why 7 investors see Knife River as 22% undervalued.
Result: Fair Value of $75.13 (UNDERVALUED)
Still, the story can break if higher diesel costs continue to reduce profitability or if delayed public projects in key regions extend and weaken Knife River’s contracting mix.
Find out about the key risks to this Knife River narrative.
Another View: Knife River Looks Expensive On Earnings
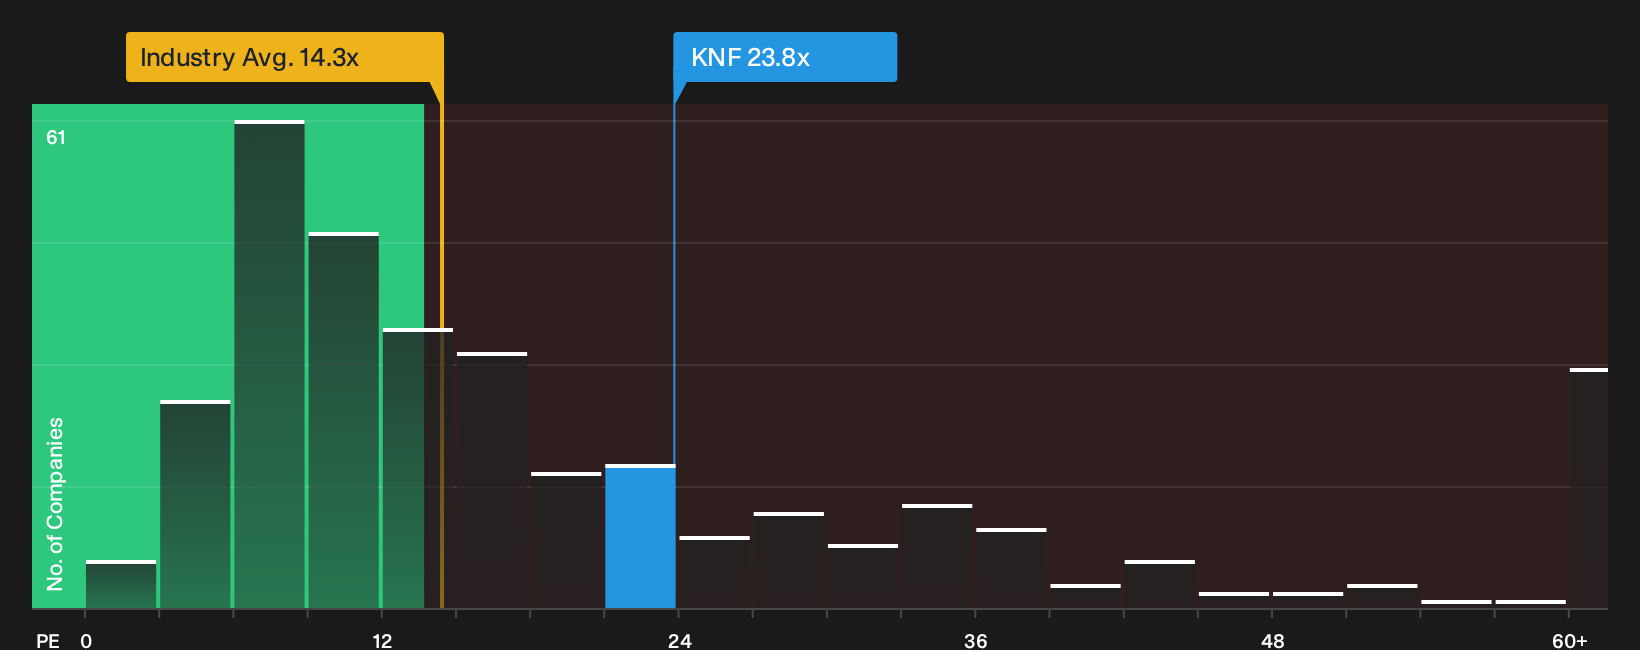
The fair value narrative paints Knife River as undervalued, yet the P/E picture tells a different story. KNF trades at 23.8x earnings versus a fair ratio of 17.3x, the US Basic Materials industry at 18.1x and peers at 22.9x. That premium points to valuation risk if expectations slip. Which signal do you trust more right now?
To see how this earnings multiple gap fits into a fuller valuation picture, including cash flow and other checks, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Knife River’s value case so far. If you want to act while sentiment is in flux and reach your own conclusion, carefully weigh both the potential upside and the watchpoints flagged in the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Knife River?
If you want to keep building on the work you have done with Knife River, use the screener to quickly surface fresh opportunities that fit your style.
- Target steady compounding potential by reviewing a curated 35 high quality undervalued stocks that combine quality fundamentals with prices that sit below their assessed worth.
- Prioritize resilience and sleep better at night by scanning a 30 resilient stocks with low risk scores filtered for stronger balance sheets and milder historical volatility.
- Stay early to potential market favourites by tracking a 19 high quality undiscovered gems that pair solid financials with lower current investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com