


EN
Navigator Holdings (NVGS) Earnings Put Valuation Back In Focus After The Pullback
Navigator Holdings (NYSE:NVGS) just posted third quarter 2026 results, reporting revenue of US$155.03 million and net income of US$78.34 million. The earnings line is now sharply in focus for investors.
Despite the strong third quarter update, Navigator Holdings' recent share price momentum has cooled, with the stock down 15.14% on a 1 month share price return and 5.33% over the past week. However, the year to date share price return of 16.6% and 1 year total shareholder return of 25.24% still point to a solid longer term run shaped by changing expectations around its earnings power and risk profile.
Scan beyond Navigator Holdings and track other gas, energy and infrastructure plays showing sharper earnings momentum with our curated 35 high quality undervalued stocks list.
The share price has cooled just as Navigator Holdings delivered a strong earnings step up. Does that recent pullback offer a reasonable entry now, or does it make more sense to wait for a cheaper price as you weigh valuation?
Most Popular Narrative: 21.2% Undervalued
The most followed narrative values Navigator Holdings at $25.67 per share, well above the last close of $20.23. This frames the recent share price pullback very differently compared with the short-term chart action.
Growing integration of shipping with infrastructure, such as the ethylene export terminal contribution and the ammonia bunkering project supported by a NOK 442 million grant that covers about 80% of the capex for three terminals, is increasing exposure to contracted and fee based cash flows that can affect earnings stability and terminal driven revenue.
See why 10 investors see Navigator Holdings as 21% undervalued.
The narrative anchors this valuation on a discount rate of 7.82% applied to expected future earnings, margins, and capital returns, and then discounts that back to today’s dollars. It effectively argues that the current share price already factors in shrinking revenue and profit margins, while giving limited credit to contract backed cash flows from terminals and a younger fleet.
Result: Fair Value of $25.67 (UNDERVALUED)
Still, the narrative can crack if time charter equivalent rates retreat faster than expected, or if vessel operating costs keep climbing and squeeze Navigator Holdings' cash cushion.
Find out about the key risks to this Navigator Holdings narrative.
Another View: SWS DCF Versus The Narrative Fair Value
A second lens on Navigator Holdings comes from the SWS DCF model, which estimates future cash flow value at just $6.13 per share versus the $25.67 narrative fair value and $20.23 market price today. One framework flags deep overvaluation while the other sees a discount. Which one matches your assumptions?
Before leaning on either approach, it helps to understand how the cash flow based view is built and what it is really saying about long term earnings power. Look into how the SWS DCF model arrives at its fair value.
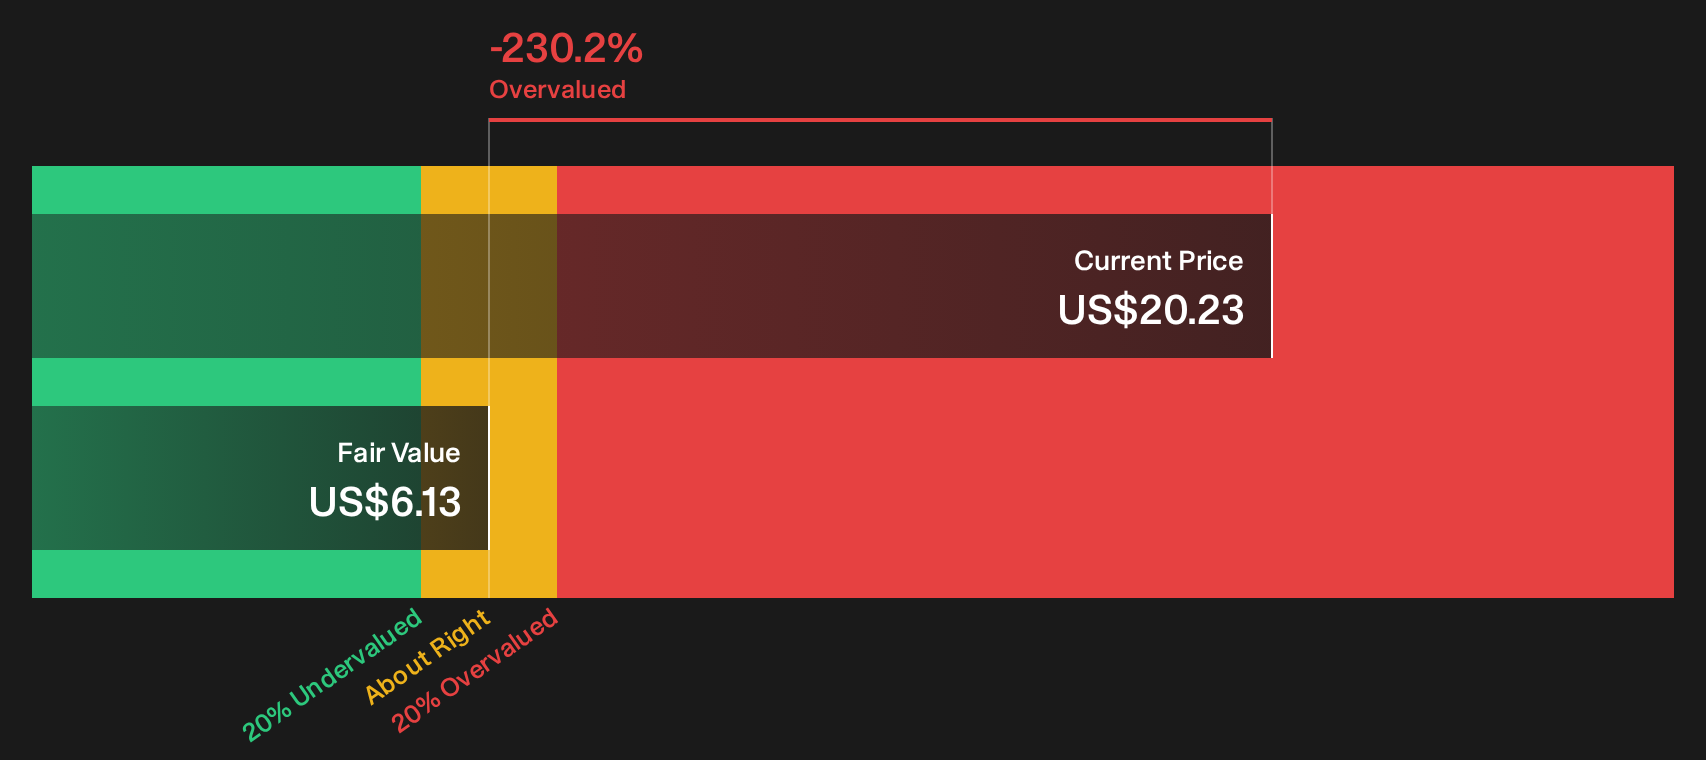
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Navigator Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
There are mixed signals on Navigator Holdings so far. Act while the data is current and consider both sides of the story by reviewing 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond Navigator Holdings?
Do not stop with a single ticker. Broader idea flow helps you spot gaps in your portfolio and uncover opportunities you might otherwise leave on the table.
- Target income resilience by reviewing companies that feature strong payouts in the 4 dividend fortresses.
- Hunt for financial strength by scanning the list of solid balance sheet and fundamentals (23 results) to see which businesses keep their foundations tight.
- Get ahead of the crowd by checking the 19 high quality undiscovered gems before attention and liquidity rush in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com