


EN
Lloyds Stock And UK Bank Shares Facing A Mortgage Rules Reset
UK banking rules are back under the spotlight, and any move to ease capital or mortgage-lending requirements could reshape how risk and reward line up for investors. If regulation shifts, returns on lending, pricing power, and appetite for UK financials might all look very different. This article walks through three UK Domestic Banking Stocks exposed to that policy debate so you can judge where the opportunity or risk may sit.
The stocks highlighted below are just a starter set, and the full screen surfaced 9 more UK banking companies with equally compelling stories that are not covered here. To size up that wider field and identify your own highest conviction ideas, head straight to the UK Domestic Banking Stocks screener.
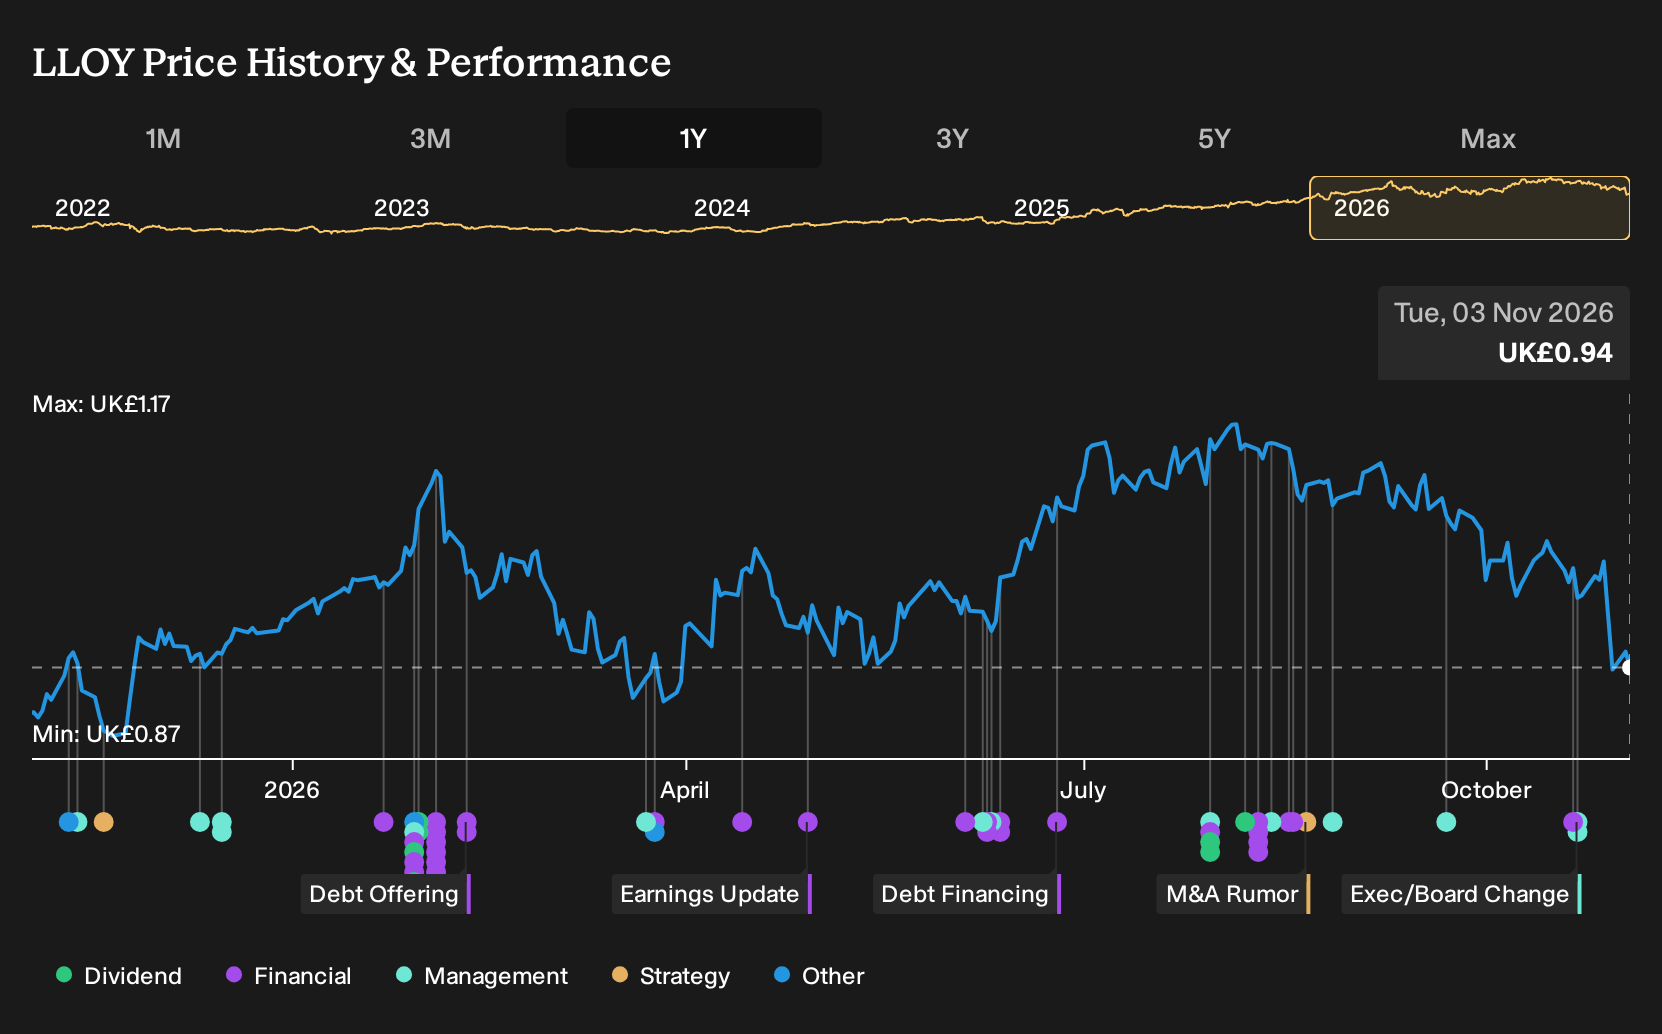
Lloyds Banking Group (LSE:LLOY)
Overview: Lloyds Banking Group is a long-established UK lender focused on everyday banking, mortgages and finance for households and small businesses.
Market Cap: £53.4b
Lloyds Banking Group gives this UK Domestic Banking Stocks screen direct exposure to how any shift in local mortgage and capital rules filters through to a high street banking giant that lives and breathes UK retail and SME lending.
"Lloyds Banking Group is moving into a new four year Accelerate 2030 plan that targets mid single digit net income growth, high single digit fee income growth and a cost income ratio below 45% by 2030."
What happens to those targets if a single pressure on UK funding costs or mortgage pricing breaks differently to management’s playbook?
If that playbook feels finely balanced, read the full narrative for Lloyds Banking Group to see how Lloyds Banking Group’s plan could accelerate or stall under shifting UK rules.
NatWest Group (LSE:NWG)
Overview: NatWest Group is a large UK bank focused on mortgages, everyday retail accounts and SME lending, with added wealth and institutional services.
Operations: NatWest Group generates most of its income from £9.1b Commercial & Institutional, £6.3b Retail Banking and £1.3b Private Banking & Wealth Management.
Market Cap: £45.9b
NatWest Group sits in the middle of this UK Domestic Banking Stocks theme, with its mix of household mortgages and SME lending giving it a front row seat on any recalibration of domestic rules and a growing set of fee businesses changing how it makes money.
"Completion of the Evelyn Partners acquisition at the end of June 2026, which more than doubled NatWest Group assets under management and administration to £131b and is expected to lift group fee income by about 20%, sets up a larger mix of capital light, recurring revenue that could support earnings resilience relative to pure interest income."
What happens to that evolving income mix if a single pressure on UK lending economics or capital requirements moves against expectations?
If that pressure point is on your mind, read the full narrative for NatWest Group to see how NatWest Group could turn shifting rules into accelerating fee power or a temporary stall.

OSB Group (LSE:OSB)
Overview: OSB Group is a UK headquartered specialist mortgage lender focused on buy to let and residential loans that hinge on UK mortgage regulation.
Operations: OSB Group generates about £421.8 million from the OneSavings Bank segment and £233.9 million from Charter Court Financial Services.
Market Cap: £1.6b
OSB Group brings the UK Domestic Banking Stocks theme closer to the housing market itself, because its specialist book depends heavily on how mortgage rules, capital buffers and funding costs evolve from here.
"OSB Group's ongoing cloud, data and AI transformation program is on time and on budget with about £85m still to be invested through 2027, while core operating costs already edged down 0.4% year on year in H1 2026 even as transformation expenses rose. This indicates the potential for further improvement in cost to income ratios and net margins as more of the benefits flow through earnings."
What happens to those margins if a single pressure on UK funding costs or mortgage risk weights breaks differently to OSB Group’s expectations?
If that funding surprise is on your radar, read the full narrative for OSB Group to see whether OSB Group’s transformation is quietly accelerating value or masking fresh risk.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time every headline chases the same theme, the best entry points can be gone. Scan what is breaking out under the radar for now and get in early.
- Spot cash generative businesses before momentum stories crowd them by running the 15 high quality undervalued stocks while pricing still reflects quieter expectations.
- Track the grid behind everything digital and hunt for tomorrow's critical suppliers with the 41 power grid technology and infrastructure stocks while the theme is still forming.
- Target automation leaders reshaping how work gets done by scanning the 93 robotics and automation stocks before the fastest movers are widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com