


EN
How Board Refresh At PVH (PVH) Has Changed Its Investment Story
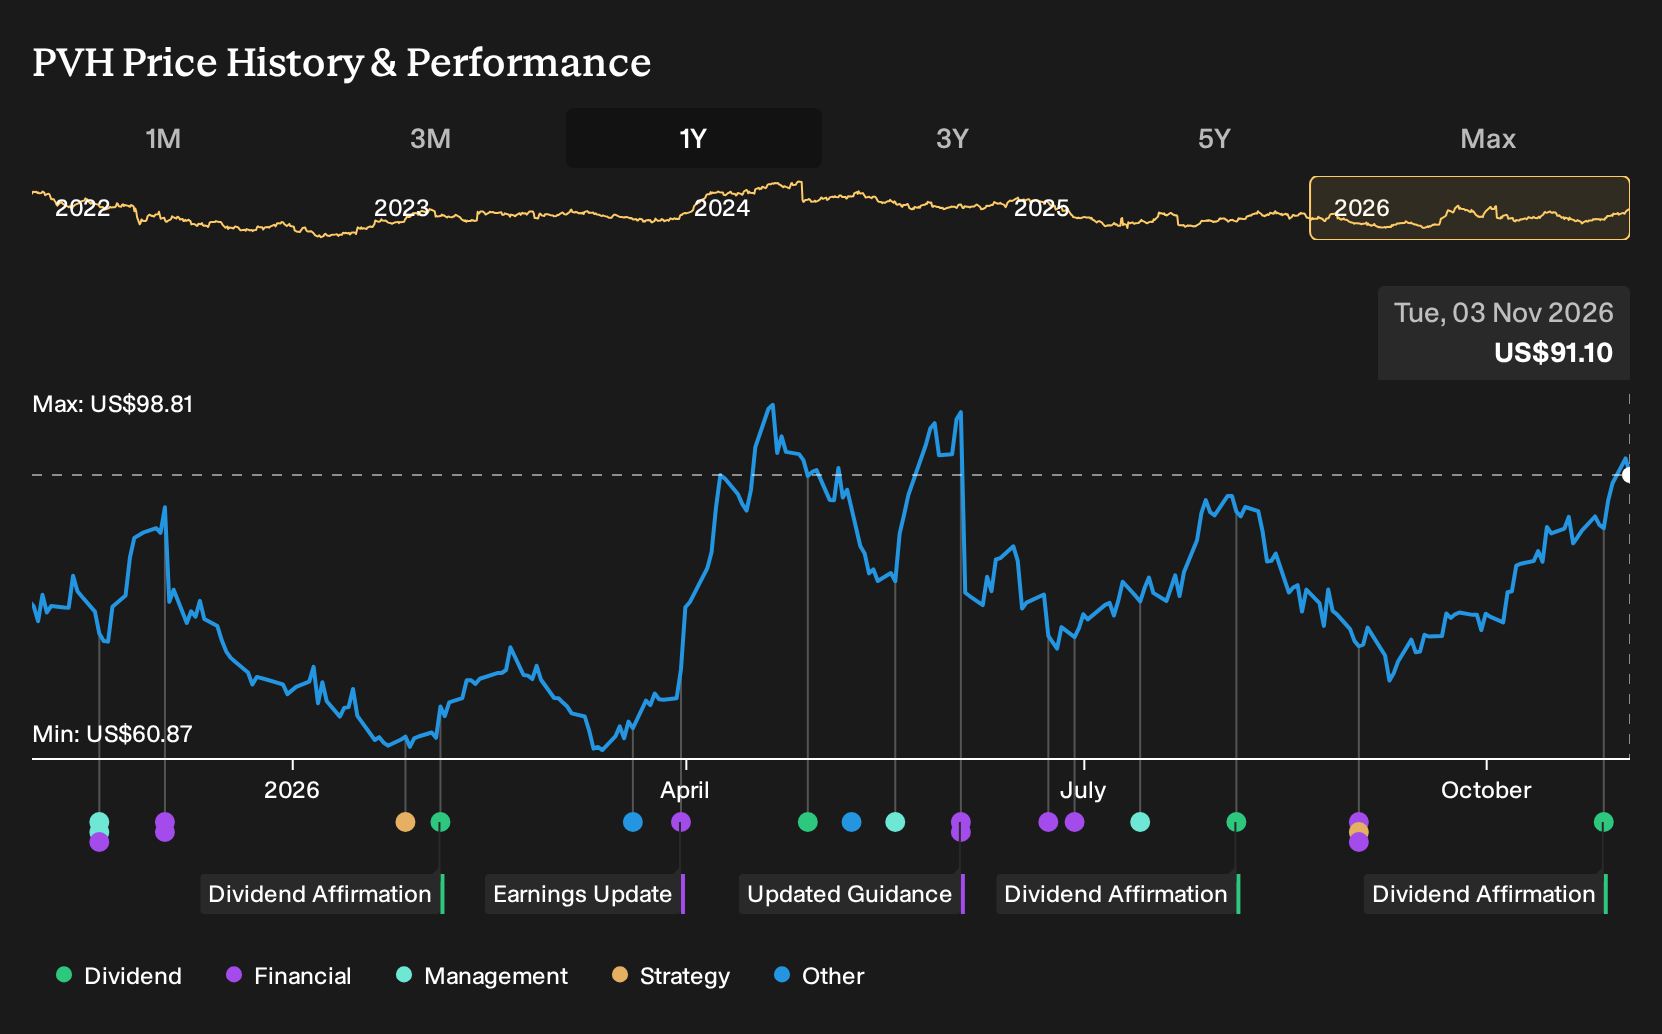
- PVH Corp. recently declared a quarterly cash dividend of $0.0375 per share and added experienced consumer and retail executive Frits Dirk van Paasschen to its Board as part of an ongoing refresh.
- Calvin Klein’s new global underwear campaign with footballer Jude Bellingham gives PVH fresh celebrity reach that aligns directly with its focus on brand heat and direct to consumer demand.
- This article examines how PVH's investment narrative is influenced by the board refresh and Calvin Klein's Jude Bellingham campaign.
PVH Investment Narrative Recap
To own PVH, you need to believe the Calvin Klein and Tommy Hilfiger franchises can keep pulling shoppers into higher margin direct channels, while EMEA pressure and weak wholesale demand are managed rather than allowed to dominate results. The near term swing factor is still execution on cost savings and channel mix, not the share price chart.
The biggest risk right now remains soft demand and geopolitical strain in EMEA that already ties to lower revenue expectations and weaker order books. The new dividend affirmation is small in absolute terms, so it does not materially change the near term story around volume, pricing power or tariff related support.
The appointment of Frits Dirk van Paasschen to the PVH board is the most relevant move for investors assessing execution risk. His background across global consumer and retail boards aligns with the company’s existing focus on direct to consumer, licensing and category focus, rather than signaling a sudden change in direction.
In terms of catalysts, board refresh matters because PVH is juggling EMEA headwinds, tariff refund reliance and heavy investment in e-commerce and stores. Fresh oversight can help management maintain focus on translating higher average unit retail and brand campaigns like Jude Bellingham’s Calvin Klein work into actual unit volume, instead of leaning mainly on pricing and mix to support margins.
What The PVH Analyst Numbers Assume
PVH's narrative projects US$9.4b in revenue and US$647.0m in earnings by 2029. That framework uses a 1.7% yearly increase in sales and expects earnings to move by about US$816.0m from a current loss of US$169.0m.
Uncover why PVH's fair value is consistent with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts see the key catalyst in PVH’s cost and margin story, not just the Calvin Klein campaign or dividend. Before this news, the bullish camp was penciling in revenue of about US$10.0b and earnings of roughly US$709.8 million by 2029. That is far more upbeat than the consensus view. Use that spread in expectations as a prompt to compare several narratives and decide which assumptions feel more realistic to you once these board and marketing moves are fully reflected in forecasts.
Explore 2 other PVH fair value estimates, including one that suggests as much as 85% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your PVH research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for PVH. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PVH's overall financial health at a glance.
Looking For More PVH-Like Investment Ideas?
Once you have formed a view on PVH, it often helps to compare that thesis with a few other companies that share similar quality markers or risk profiles. The Simply Wall St Screener can help you quickly filter the wider market down to a focused watchlist that fits the way you like to invest.
- If you care most about resilient balance sheets and solid fundamentals, start by scanning a list of solid balance sheet and fundamentals (23 results) to focus on companies with financial cushions that may better withstand shocks.
- For investors hunting for quality at a reasonable price, you can filter for a 35 high quality undervalued stocks that matches your return and risk preferences without needing to sift manually through hundreds of tickers.
- Income focused readers who want yield alongside stability can focus on a 4 dividend fortresses that screens for companies offering higher payouts while still meeting basic financial health checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com