


EN
Expected Earnings Beat Could Be A Game Changer For Ross Stores (ROST)
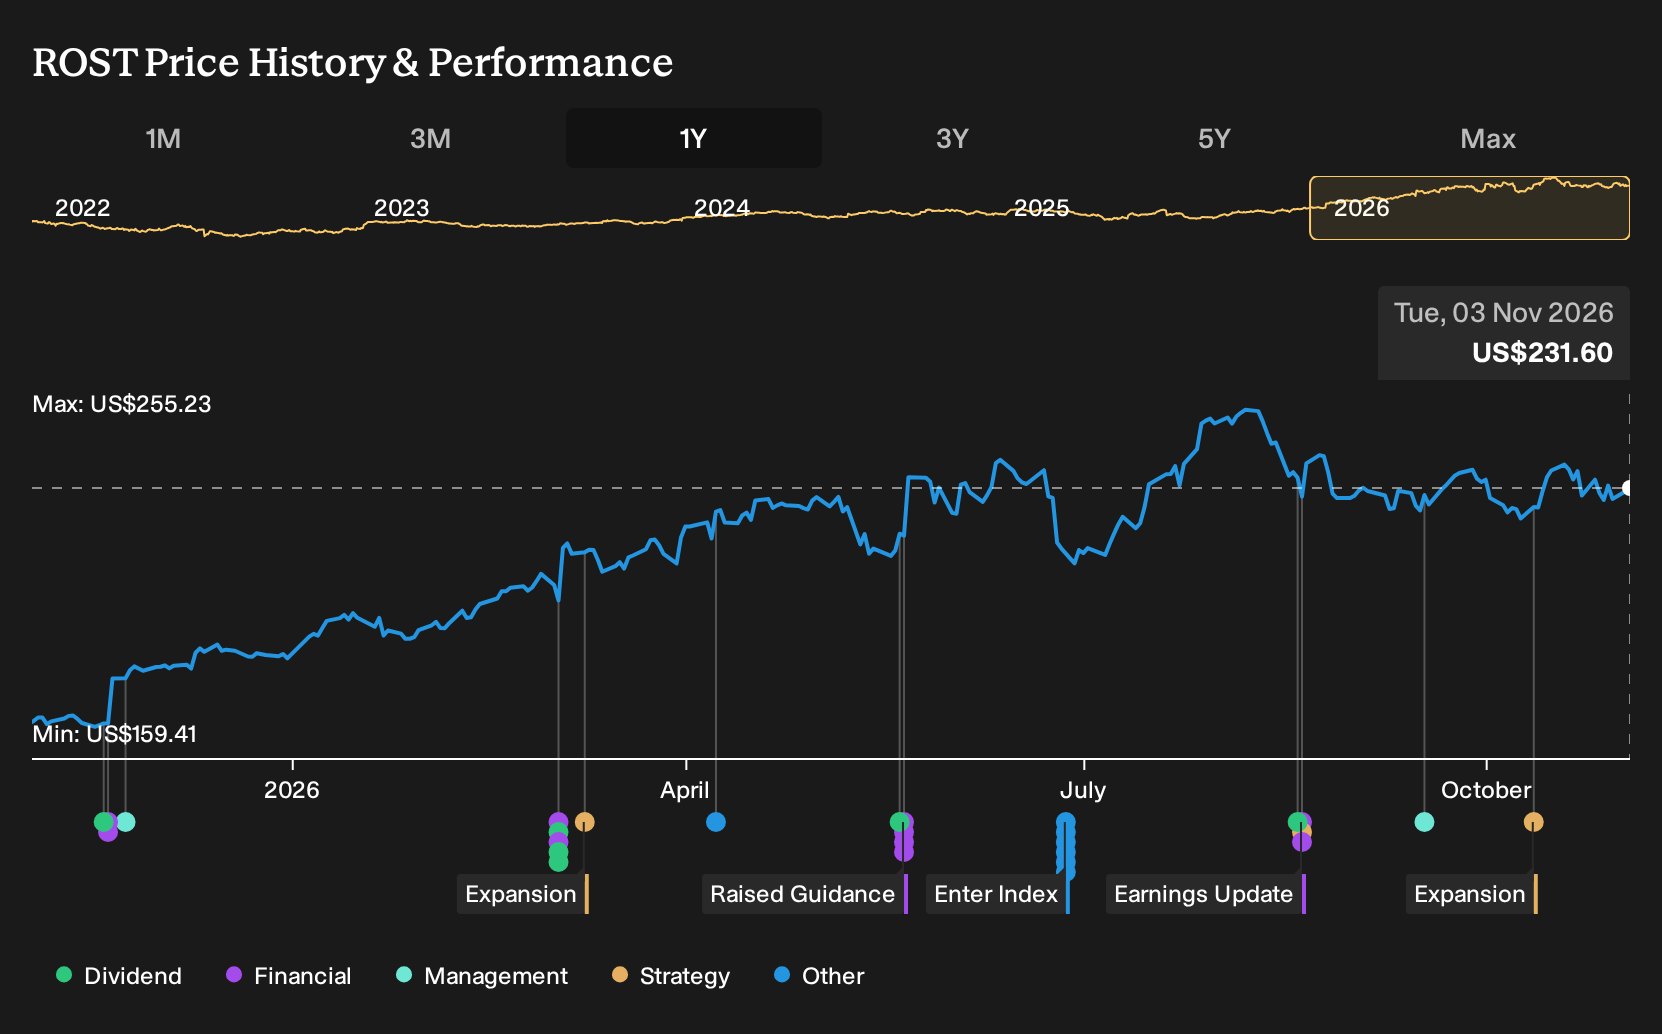
- Ross Stores recently closed at US$230.59, with investors focused on the retailer’s upcoming earnings release that is expected to show earnings of US$1.82 per share on US$6.2b in revenue.
- The projected double digit year over year increases in both earnings and sales highlight how demand, merchandising and store execution remain central pressure points for Ross Stores heading into this report.
- We will now see how Ross Stores’ investment narrative could be affected by expectations for stronger near term earnings and revenue performance.
Explore the broader retail opportunity around Ross Stores by reviewing which peers also report solid earnings and revenue profiles in our curated list of solid balance sheet and fundamentals (23 results)
Ross Stores Investment Narrative Recap
To own Ross Stores, you need to believe its off price model can keep attracting broad customer traffic while merchandise buying and store productivity stay tight enough to support earnings. The latest expectation for higher near term EPS and revenue places the focus squarely on whether that merchandising edge and shopper momentum are still intact.
The key near term catalyst is this earnings print, because it will update you on comparable sales, merchandise margins and any commentary on newer regions. Freight, fuel and higher distribution spend remain the biggest operational risk. If those costs bite harder than expected, the impact on margins could matter more than any headline revenue figure.
The most relevant piece of recent information is the projected US$1.82 in EPS on US$6.2b of sales for the upcoming quarter, alongside full year estimates of US$8.77 per share on US$25.65b. Those figures show that the market is watching whether Ross Stores can keep translating traffic and new stores into consistent profit growth.
For you as an investor, this update ties directly into the existing catalysts and pressure points. Stronger earnings would help support the higher P/E multiple relative to the US Specialty Retail industry, while any hint of freight deleverage, fuel cost pressure or store rollout issues could raise questions about how sustainable current margins and capital spending plans really are.
Ross Stores' current analyst narrative points to revenues of US$30.3b and earnings of US$3.2b by 2029. That profile is based on an assumed 7.4% yearly increase in revenue and an earnings uplift of about US$0.5b from US$2.7b today.
Uncover why Ross Stores' fair value indicates a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative view on Ross Stores focuses strongly on store expansion risk. This is reflected in the more cautious analysts who were pencilling in roughly US$29.9b of revenue and US$2.8b of earnings by 2029, compared to the higher consensus before this latest earnings news. Those lower forecasts show how sharply opinions can diverge, so it is worth exploring both narratives and asking how this new information might shift them.
Explore 3 other Ross Stores fair value estimates, including one that suggests as much as 68% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ross Stores research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ross Stores. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ross Stores' overall financial health at a glance.
Looking for more investment ideas beyond Ross Stores?
If this Ross Stores update has sharpened your thinking but you want a wider watchlist, the Simply Wall St Screener can help you map out where else the numbers look interesting before the next wave of earnings hits.
- If you like backing strength in the balance sheet, you can filter for companies with solid cash positions and manageable debt using the list of solid balance sheet and fundamentals (23 results).
- If value is your starting point, you can look for businesses combining quality fundamentals with potentially attractive pricing through the 35 high quality undervalued stocks.
- If income matters to your plan, you can search for companies offering higher yields with robust payout support via the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com