


EN
Texas Pacific Land (TPL) Earnings Strength Puts Valuation Back In Focus
Texas Pacific Land (TPL) drew fresh attention after reporting quarterly revenue growth of 31.2% and a 32.7% rise in earnings per share, supported by US$112.5 million in net cash and ongoing dividend payments.
Texas Pacific Land’s share price has slipped over the last quarter, with a 90-day share price return down 13.06%, even though the year-to-date share price return is 11.42% and the 3-year total shareholder return sits at 81.93%. This suggests that longer term momentum has been stronger than the recent pullback.
Scan for other land and resource plays that show similar earnings strength to Texas Pacific Land by checking our curated list of 19 high quality undiscovered gems in this corner of the market.
Texas Pacific Land now trades materially below both analyst targets and one intrinsic value estimate, after a sharp recent pullback. So where does a reasonable fair value range actually sit relative to that US$332 share price?
Most Popular Narrative: 25% Undervalued
Texas Pacific Land is framed by the most followed narrative as being worth $445 per share, which sits above the last close at $332. That gap puts the focus squarely on whether its Permian royalties and water operations can sustain the cash flows implied by that target under a 7.1% discount rate.
Reliance on oil royalties and Permian Basin activity faces long-term risks from decarbonization, reserve declines, and regulatory challenges, threatening growth and margin stability.
Investor optimism discounts headwinds from restrictive ESG trends, water scarcity, and rising regulatory scrutiny, jeopardizing valuation and future financial performance.
See why 30 investors see Texas Pacific Land as 25% undervalued.
The narrative effectively argues that for the $445 fair value to hold, investors need to be comfortable underwriting revenue growth assumptions of roughly mid-teens annually and profit margins above 60%, discounted at 7.1%. That framework places a lot of weight on Texas Pacific Land’s ability to keep monetizing its 868,000 acres in the Permian while managing environmental, regulatory and ESG constraints that could pressure both royalty volumes and water-related economics.
On that basis, the current US$332 share price sits meaningfully below the US$445 narrative fair value. However, the quoted risks around decarbonization, water scarcity and future regulation underline why some investors may still treat that gap with caution rather than assuming it must close quickly.
Result: Fair Value of $445 (UNDERVALUED)
Still, that apparent discount to US$445 depends on optimistic expectations for Permian royalty volumes and water revenues, which could be challenged by tighter regulation or shifting ESG capital flows.
Find out about the key risks to this Texas Pacific Land narrative.
Another View on Texas Pacific Land’s Valuation
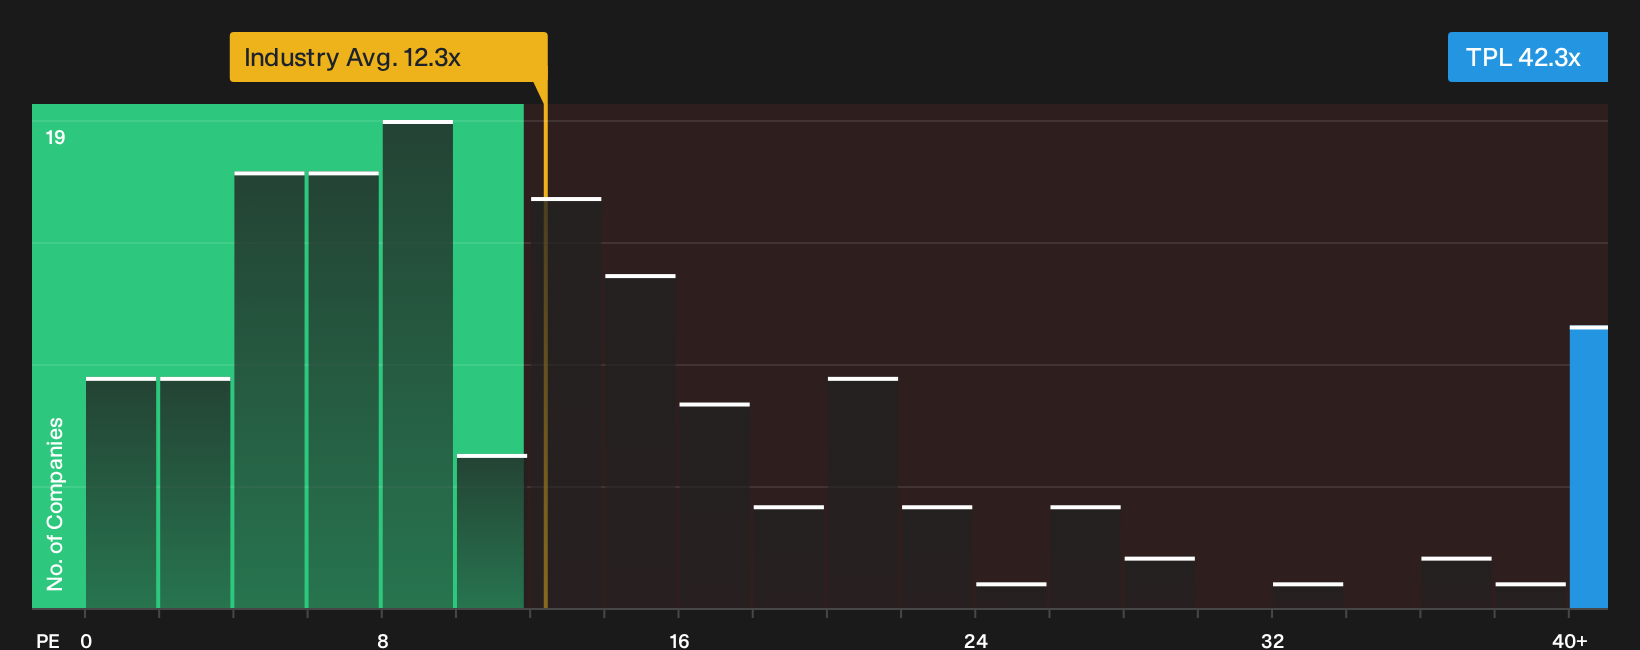
The first narrative pins Texas Pacific Land to a fair value of $445 per share. A second lens tells a harsher story. At a P/E of 42.3x, the stock trades at more than 3x both the US Oil and Gas industry average of 12.3x and peer levels, and well above a fair ratio of 19.1x that the market could drift toward. That sort of gap can reward patience if growth delivers, or punish it sharply if expectations reset. Which outcome feels more realistic to you?
For a closer look at how that earnings multiple compares with fundamentals, valuation history, and peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Pulling these threads together, Texas Pacific Land clearly splits opinion, which is exactly why your own review of the data matters right now. To weigh those cross currents for yourself, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Texas Pacific Land?
If Texas Pacific Land has sharpened your focus on quality and price, do not stop here. Broaden your watchlist now so you are not reacting after the best opportunities have moved.
- Target resilient balance sheets and steady fundamentals by reviewing companies in the list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced quality by scanning the 35 high quality undervalued stocks that combine strong cash generation with supportive financial profiles.
- Prioritise stability with potential downside protection by focusing on 30 resilient stocks with low risk scores that show lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com