


EN
Is Earnings Guidance Altering The Investment Case For AtriCure Stock (ATRC)?
- AtriCure reported third quarter 2026 revenue of US$154.45 million and net income of US$4.06 million, and now guides full year 2026 revenue to a range of US$606 million to US$610 million with projected earnings per share of US$0.21 to US$0.27.
- The shift from losses in the prior year periods to profits in both the quarter and year to date reflects increasing operating scale and gives investors a clearer view of how AtriCure’s cost base is being absorbed by higher procedure volumes.
- We will now assess how AtriCure’s move from losses to profitability could influence its investment narrative and risk reward profile.
Scan other procedure driven opportunities that follow a similar profitability path as AtriCure with our curated list of list of solid balance sheet and fundamentals (23 results)
AtriCure Investment Narrative Recap
For an investor to stay with AtriCure, the core belief is that procedure volumes, product adoption and geographic expansion can support sustained profitability, not just a one year swing into the black. The fresh 2026 guidance, with revenue projected at US$606 million to US$610 million and earnings per share of US$0.21 to US$0.27, provides a clearer reference point for that thesis in the near term.
The key short term catalyst remains execution on higher procedure volumes while keeping SG&A and R&D growth in check so operating leverage holds. The biggest risk is that competitive pressure in minimally invasive ablation or slower international uptake forces heavier commercial spend, which could quickly compress the newly achieved profitability if conditions soften.
The third quarter 2026 earnings release is the most relevant update for thinking about those catalysts. AtriCure reported quarterly revenue of US$154.45 million and net income of US$4.06 million. For the first nine months of 2026, the business generated US$449.3 million of revenue and net income of US$13.13 million, a shift from losses in the prior year period.
That move into the black, combined with the full year guidance, puts more focus on whether the firm can keep absorbing its cost base as it pursues trials like BoxX NoAF and LeAAPS and continues international expansion. If competitive, pricing, or regulatory pressures increase, management may need to choose between protecting margins and funding growth initiatives at the same pace.
AtriCure's narrative projects US$807.8 million revenue and US$36.7 million earnings by 2029, which implies forecast revenue growth of 12.3% per year and an earnings increase of about US$26.1 million from US$10.6 million today.
Uncover why AtriCure's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
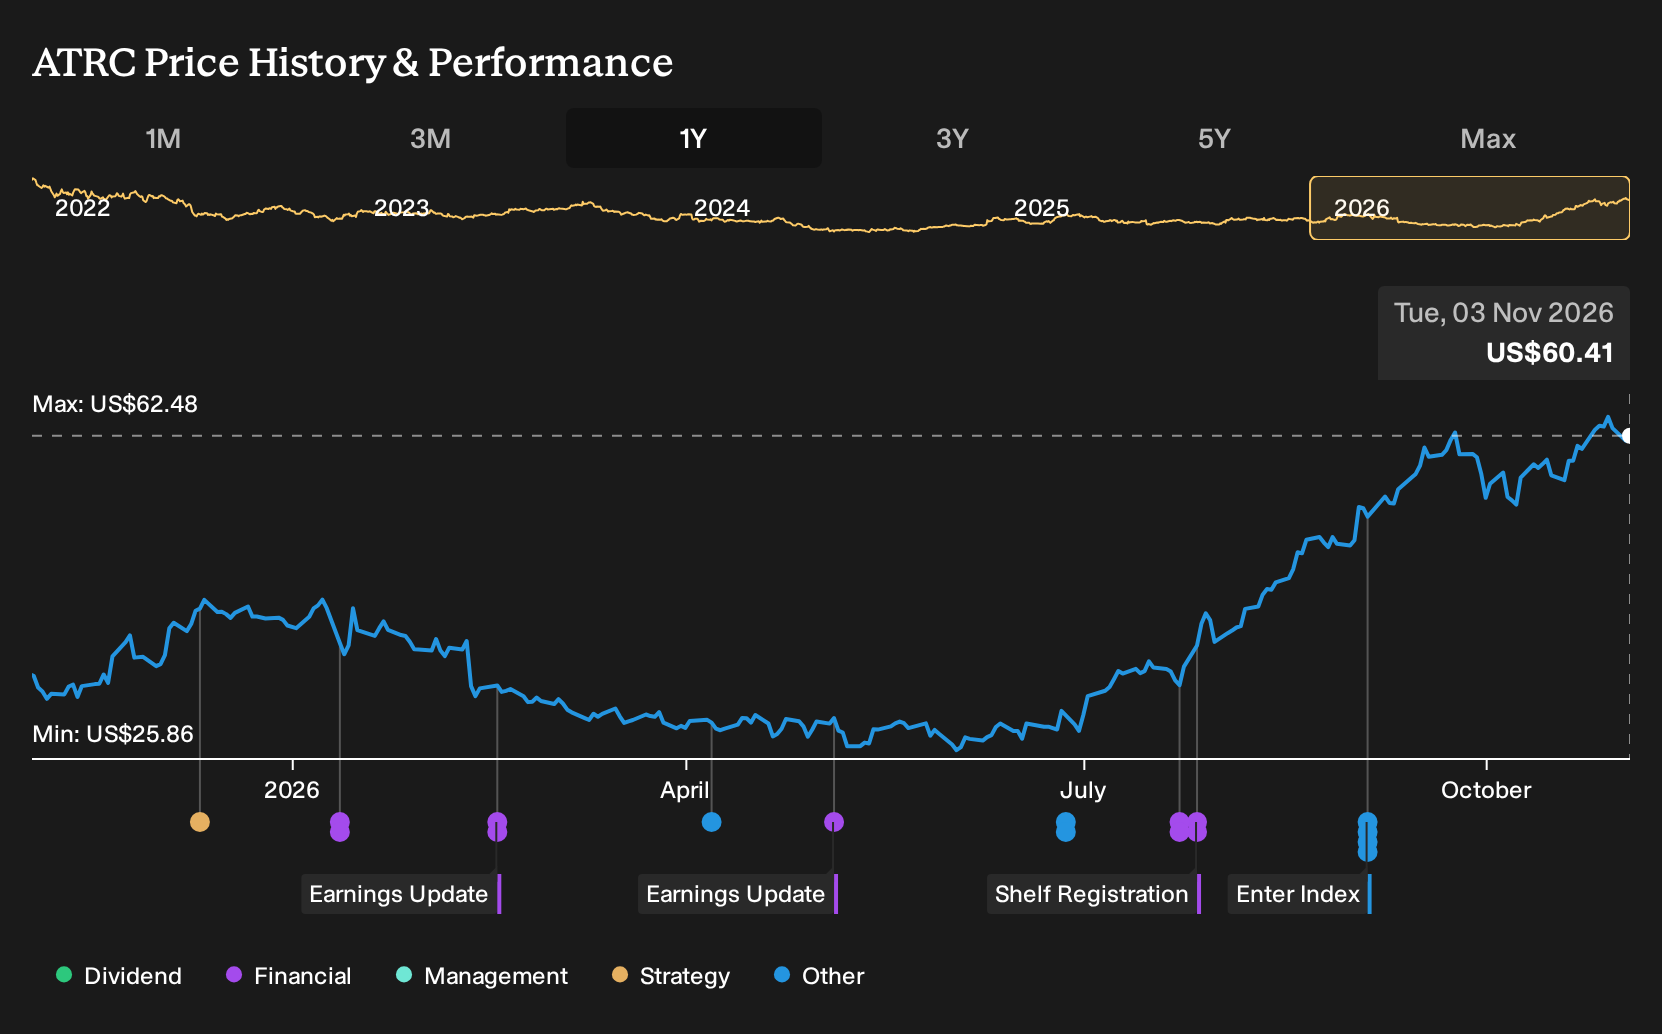
Exploring Other Perspectives
One bearish angle on AtriCure focuses on how sensitive earnings could be to any slowdown once the new manufacturing facility starts to weigh on gross margin. The lowest analysts were only looking for about US$820.2 million of revenue and US$26.6 million of earnings by 2029. That is a much more cautious story. These forecasts were set before this guidance and earnings news, so treat them as moving pieces and compare several viewpoints before deciding what this profitability step means for you.
Explore another AtriCure fair value estimate, including one that suggests as much as 99% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your AtriCure research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AtriCure. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AtriCure's overall financial health at a glance.
Looking for more AtriCure like investment ideas?
If AtriCure's shift into profitability has you thinking about portfolio upgrades, it can help to line it up against other companies with different risk and income profiles. The Simply Wall St Screener lets you move from this single stock to a broader watchlist that fits your own return goals and risk tolerance.
- If you want income to do more of the heavy lifting, scan for companies that combine higher yields with balance sheet strength through 4 dividend fortresses.
- If capital preservation matters most to you, focus on businesses with steadier risk characteristics using our 30 resilient stocks with low risk scores.
- If you are hunting for underappreciated opportunities with solid fundamentals, widen your search beyond AtriCure with a curated pool of 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com